COMPANY PROFILE / DRUG DISCOVERY & DDS
Arrowhead Pharmaceuticals
— An RNAi biotech combining TRiM licensing partnerships with its own medicines
Arrowhead Pharmaceuticals specializes in siRNA therapeutics (RNA interference). Its first proprietary product, REDEMPLO (plozasiran), received U.S. approval in November 2025. Revenue for the fiscal year ended September 30, 2025 was US$829.448 million, generated primarily by collaboration and licensing agreements, including Sarepta. This profile examines the TRiM delivery platform, Arrowhead's in-house siRNA drug-substance manufacturing, and the partnership model that helps fund its own development and commercialization programs.
- Arrowhead at a glance and its position in drug discovery and DDS
- Logo and company name
- Where Arrowhead fits in the industry
- Company scale and financial results
- Resources for drug discovery and delivery
- Development and partnership milestones
- Plans and development pipeline
- Interpreting Arrowhead's strategy
- Partnership map
- Technologies, products and services
- Principal risks
- Glossary, references and claim-to-source audit
1. Arrowhead at a glance
(specialist in siRNA)First proprietary product approved in 2025
Arrowhead's 10-K distinguishes between medicines it intends to commercialize itself and programs licensed to partners. Partners include Sarepta, Amgen, Takeda, GSK and Novartis. Arrowhead describes partnership proceeds as non-dilutive funding for its own development and commercialization activities Facts. Sarepta-related revenue was US$696.8 million in FY2025, approximately 84.0% of total revenue of US$829.448 million Our calculation. This means that licensing its RNAi design and delivery capabilities was the main revenue driver, while sales of its own approved product were still at an early stage in the later reporting period.
2. Logo and company name
The Arrowhead logo belongs to Arrowhead Pharmaceuticals. The displayed logo is an existing image asset, not an AI-generated recreation. The corporate name is
Arrowhead Pharmaceuticals, Inc.
Reporting conventions: Arrowhead Pharmaceuticals, Inc. has a fiscal year ending September 30. FY2025 therefore covers October 1, 2024 through September 30, 2025. Some agreements involve group entities, including Visirna Therapeutics, a consolidated variable-interest entity; the contracting entity is distinguished where relevant.
Official Site:https://arrowheadpharma.com/3. Where Arrowhead fits in drug discovery and DDS
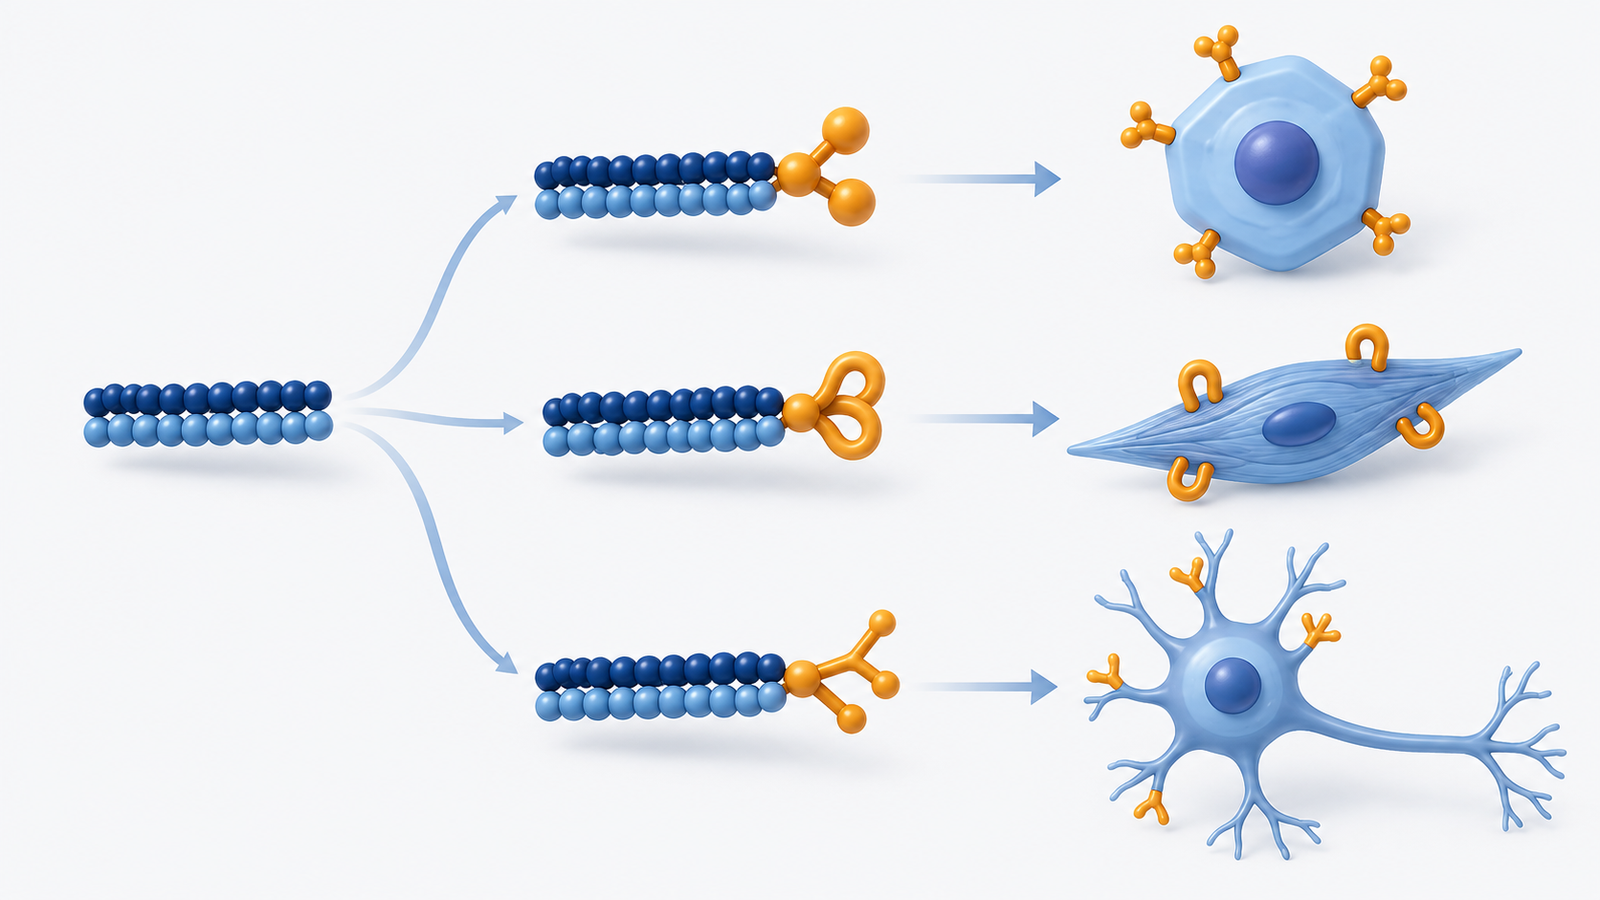
Arrowhead's category is drug-discovery biotech, specializing in siRNA. Its medicines use RNA interference to reduce expression of selected disease-related genes. The company combines RNA chemistry with tissue-targeted delivery Facts. Its delivery platform is TRiM (Targeted RNAi Molecule), a ligand-conjugated siRNA approach. Company filings describe delivery to seven cell/tissue targets; that platform-capability claim does not imply approved medicines for all seven Facts. The related technology guides explain oligonucleotide therapeutics and the principles of drug delivery and targeting.
4. Company scale and financial results
| Metric (U.S. GAAP; US$ million, rounded) | FY2024 | FY2025 | Nine months ended June 30, 2026 |
|---|---|---|---|
| Revenue | 3.6 | 829.4 | 413.0 |
| Collaboration and licensing revenue | ― | 829.4 | 409.5 |
| R&D expenses | 505.9 | 607.2 | 548.7 |
| Net income / (loss) attributable to Arrowhead | (599.5) | (1.6) | (296.2) |
FY2025 revenue included US$696.8 million from Sarepta, US$130.0 million from Sanofi through Visirna, and approximately US$2.6 million from GSK. The table rounds figures to one decimal place. A detailed FY2024 revenue breakdown is not reproduced here.
Arrowhead reported 711 full-time employees at September 30, 2025, across four U.S. facilities Facts. At June 30, 2026, cash, cash equivalents and restricted cash totaled US$54.8 million, with a further US$1,547.2 million in available-for-sale securities Facts. Revenue of US$413.023 million for the nine months ended June 30, 2026, less US$409.522 million of collaboration and licensing revenue, leaves approximately US$3.5 million. This is a residual calculation, not a separately quoted REDEMPLO product-sales disclosure Our calculation.
The FY2025 net loss attributable to Arrowhead was US$1.631 million. The near-break-even result reflected substantial partnership revenue, including recognition related to Sarepta's US$500 million upfront payment; it did not establish a mature, product-sales-led earnings base. For the nine months ended June 30, 2026, the net loss attributable to Arrowhead was US$296.205 million Facts.
5. Resources for drug discovery and delivery
| Resource | What the filings disclose | Evidence |
|---|---|---|
| People: research facilities | Laboratories in San Diego and Madison with more than 251,000 square feet in total. Capabilities include AI-assisted analysis of human genetics data and the discovery, synthesis and analysis of oligonucleotides, peptides, antibodies and small molecules. | Facts |
| People: workforce | 711 employees at September 30, 2025. Substantial clinical-trial work is outsourced to CROs, and some drug manufacturing is outsourced to contract manufacturers. | Facts |
| Funding: R&D | FY2025 R&D expense was US$607.159 million. Candidate costs were US$347.571 million, or approximately 57.2% of that total. | Facts |
| Assets: manufacturing | An approximately 300,000-square-foot GMP oligonucleotide manufacturing facility and support laboratories in Verona, Wisconsin. Full occupancy certification was obtained in August 2024, and expansion continued in the first quarter of FY2025. The company describes maximum annual capacity in the hundreds of kilograms of GMP drug substance; this is capacity, not verified production output. | Facts |
| External: financing | A US$500 million secured term-loan facility with Sixth Street (August 2024); the sale of future olpasiran royalties to Royalty Pharma (November 2022); and US$700 million of convertible senior notes issued in January 2026, among other financing activities. | Facts |
| External: investments | Visirna Therapeutics is consolidated as a variable-interest entity. The June 2026 10-Q also reports an equity-method investment in Bisirna Therapeutics. These structures should not be described as a verified acquisition of a drug-discovery company. | Facts |
| Universities and research institutions | Primate research uses the Wisconsin National Primate Research Center and other CROs. The Madison research facility is leased from University Research Park. | Facts |
| Public funding | A separate total for government research grants is not established in this profile. | Not established here |
6. Development and partnership milestones
| Date | Event | Significance for drug discovery and DDS |
|---|---|---|
| September 2016 | Licensed olpasiran, targeting lipoprotein(a), to Amgen. | A major cardiovascular program entrusted to a larger partner. |
| October 2018 | Licensed a hepatitis B program, then JNJ-3989, to Janssen. The program subsequently moved to GSK under the December 2023 agreement. | Expansion into infectious disease. |
| October 2020 | Agreed to co-develop fazirsiran with Takeda for liver disease associated with alpha-1 antitrypsin deficiency, with a 50/50 U.S. profit-sharing structure if commercialized. | A co-development and potential co-commercialization model. |
| November 2021 | Licensed ARO-HSD to GSK for liver-disease development. | A further liver-disease partnership. |
| November 2022 | Sold future olpasiran royalties to Royalty Pharma. | Converted potential future royalty income into financing. |
| August 2024 | Obtained full occupancy certification for the Verona facility and entered the Sixth Street financing agreement. | Expansion of in-house drug-substance manufacturing. |
| November 2024 | Entered a broad Sarepta partnership covering rare diseases of muscle, the central nervous system and the lungs. After closing in February 2025, Arrowhead received a US$500 million upfront payment and a US$325 million equity investment. | A major partnership built partly on delivery beyond the liver. |
| August 2025 | Visirna transferred Greater China rights to plozasiran to Sanofi. Arrowhead also agreed to collaborate with Novartis on ARO-SNCA and other targets; a US$200 million upfront payment followed closing in October 2025. | Licensing that includes central-nervous-system delivery programs. |
| November 2025 | REDEMPLO (plozasiran) received U.S. approval for adults with familial chylomicronemia syndrome (FCS). Arrowhead also earned a US$200 million Sarepta milestone that month. | First approved proprietary product. |
| December 2025 | Entered a clinical-materials manufacturing and supply agreement with Sarepta. | Manufacturing for a development partner at Arrowhead's own facility. |
| October 2025 - June 2026 | The June 2026 10-Q reports REDEMPLO approvals in the EU, China, Canada and Australia, and clinical initiation of ARO-DIMER-PA, designed to silence two genes with one molecule. | Clinical testing of a two-target RNAi approach. |
| May 2026 | Licensed clinical-stage ARO-PNPLA3 worldwide to Madrigal for US$25 million upfront, with up to US$975 million in potential milestones plus royalties. | Continued partnering of clinical-stage programs. |
| After June 30, 2026 | The 10-Q reports that Phase 3 SHASTA-3 and SHASTA-4 in severe hypertriglyceridemia (sHTG) met their primary endpoints. | Evidence supporting development in a broader patient population. |
Clinical-trial example: PALISADE (REDEMPLO)
PALISADE supported the November 2025 U.S. approval. The study information below comes from U.S. prescribing information and is not a treatment recommendation Facts.
| Item | Details |
|---|---|
| Study name and identifier | PALISADE (NCT05089084), randomized, double-blind and placebo-controlled |
| Participants | Adults with genetically confirmed or clinically diagnosed FCS, maintained on a low-fat diet. |
| Trial regimen and comparator | Four subcutaneous doses of REDEMPLO 25 mg every three months (26 participants), compared with placebo (25 participants), over 12 months. The figures here refer to the approved-dose comparison described in the label. |
| Primary endpoint | Percent change from baseline in fasting triglycerides at month 10. |
| Result | Median between-group difference in percent change: −58.7% (95% confidence interval: −89.6% to −27.9%). This is a trial result, not an expected outcome for an individual patient. |
7. Plans and development pipeline
For sHTG, a larger potential patient population, the company described a phased expansion of commercial capabilities Forward-looking. Selected programs described in the filings are listed below. Investigational status does not guarantee approval.
| Program | Target indication | Stage | Status |
|---|---|---|---|
| plozasiran (sHTG) | Severe hypertriglyceridemia | Investigational for sHTG; Phase 3 SHASTA-3, SHASTA-4, SHASTA-5 and MUIR-3 development. U.S. Breakthrough Therapy designation is not marketing approval. | Forward-looking |
| zodasiran | Homozygous familial hypercholesterolemia (HoFH) | Phase 3 YOSEMITE; the June 2026 10-Q reports completion of enrollment at 70 participants. | Forward-looking |
| ARO-DIMER-PA | Mixed hyperlipidemia; designed to silence PCSK9 and APOC3 simultaneously. | Phase 1/2a in the cited filing. | Forward-looking |
| ARO-MAPT | Tauopathies, including Alzheimer's disease. | Phase 1/2a in the cited filing. | Forward-looking |
| ARO-DM1 (SRP-1003) | Myotonic dystrophy type 1; licensed to Sarepta. | Phase 1/2a in the June 2026 10-Q. | Forward-looking |
The following are not independently established in this profile Forward-looking.
SHASTA-3 and SHASTA-4 results at a specified assessment time point (the cited 10-Q summary does not identify that time point here); the subsequent filing and approval dates for sHTG; clinical and commercial validation across all seven TRiM cell/tissue targets; and the Verona facility's actual utilization, production output and total capital investment. Unverified estimates are not substituted for disclosed figures. Program stages above are tied to the cited filings rather than presented as a complete October 2026 pipeline update.
8. Interpreting Arrowhead's strategy
This section includes editorial interpretation rather than only direct company statements. Each interpretation is tied to the cited evidence; it should not be read as a confirmed company forecast.
| Interpretation | Evidence in primary sources | Evidence type |
|---|---|---|
| Cardiometabolic programs may support in-house commercialization, while some rare muscle and neurological diseases are developed with specialist partners. | REDEMPLO and zodasiran remain proprietary programs; Sarepta licenses muscle, CNS and lung programs, while Novartis collaborates on ARO-SNCA and other targets. | Editorial interpretation |
| Delivery differentiation extends beyond the liver. | The 10-K identifies extrahepatic delivery as important to RNAi's potential. Sarepta and Novartis agreements include muscle and CNS targets. | Facts |
| In-house drug-substance manufacturing may contribute to competitiveness | The Verona GMP facility has stated capacity in the hundreds of kilograms annually, and Arrowhead entered a clinical-materials supply agreement with Sarepta. | Editorial interpretation |
| One molecule can be designed to silence multiple genes | The company describes ARO-DIMER-PA as its first clinical candidate targeting two genes simultaneously in one molecule. | Facts |
The 10-K identifies simpler manufacturing and lower costs as potential benefits of the TRiM platform Facts. It also describes Verona's maximum annual capacity as hundreds of kilograms of GMP drug substance Facts. The labeled REDEMPLO regimen is 25 mg every three months, equivalent to 100 mg of active ingredient per patient-year. As a purely illustrative mass balance, 100 kg of active-ingredient equivalent would correspond to approximately one million patient-years at that regimen, before formulation, testing and other manufacturing losses Our calculation. This is not a production forecast, a demand estimate or a statement of available treatment supply. The facility could support broader indications such as sHTG and manufacturing for partners; that strategic reading remains an editorial interpretation Forward-looking.
9. Partnership map
10. Technologies, products and services
The 10-K describes four elements of the TRiM platform: targeting ligands, linker chemistry, structures that improve pharmacokinetics, and sequence-specific stabilization of siRNA. These are combined and tailored for each candidate Facts. The company presents smaller, simpler molecules with only the necessary modifications as a way to simplify manufacturing and potentially reduce metabolite accumulation. These are platform claims, not a guarantee of clinical safety or performance.
| Product or technology | Description | Evidence |
|---|---|---|
| REDEMPLO (plozasiran) | An APOC3-directed siRNA conjugated to a ligand with three GalNAc residues for hepatocyte delivery. The U.S. label specifies 25 mg subcutaneously every three months as an adjunct to diet for adults with FCS. The June 2026 10-Q reports approvals in the United States, EU, China, Canada and Australia; local indications and labeling should be checked separately. | Facts |
| TRiM platform | Ligand-conjugated siRNA delivery. The company describes seven cell/tissue targets; this is not the same as seven approved therapeutic applications. | Facts |
| Manufacturing and supply | Under the Sarepta clinical supply agreement, Arrowhead manufactures and supplies specified clinical materials to its partner. | Facts |
| Patent | Approximately 643 issued patents, including 404 relating to RNAi trigger molecules and 159 to targeting groups or compounds, plus approximately 833 pending applications, as reported in the FY2025 10-K. | Facts |
The U.S. prescribing information describes plozasiran's ribose 2′ positions as modified with fluorine (2′F) or methoxy groups (2′O-Me), with multiple phosphorothioate linkages in each strand. The plozasiran sodium molecular formula contains 11 fluorine, 7 sulfur and 43 phosphorus atoms Facts. The sulfur-to-phosphorus ratio is therefore 7/43, or approximately 0.16. This calculation describes composition; it is not a direct measure of stability, efficacy or safety. For this molecule, 2′ modifications and selected backbone modifications both contribute to the chemical design Our calculation. Manufacturing requires the relevant 2′F- and 2′O-Me-modified phosphoramidite building blocks, ligand synthesis and conjugation, and separate strand synthesis followed by annealing. Scaling production therefore raises a practical question: can specialized raw materials be sourced consistently at the required scale? This is an editorial supply-chain consideration, not a finding that Arrowhead currently has a shortage Forward-looking.
11. Principal risks
| Risk | Description | Evidence type |
|---|---|---|
| Dependency on partner income | Sarepta-related revenue represented approximately 84.0% of FY2025 revenue. Collaboration revenue can fluctuate with upfront payments, milestone achievement and accounting recognition. | Our calculation |
| Losses and financing obligations | Net loss attributable to Arrowhead was US$296.205 million for the nine months ended June 30, 2026. Financing includes the Sixth Street facility and US$700 million of convertible senior notes. Debt terms and financing obligations create risks described in the filings. | Facts |
| Early commercialization | Total revenue less collaboration and licensing revenue leaves approximately US$3.5 million for the nine months ended June 30, 2026. This residual should not be confused with a mature commercial revenue base or a separately verified product-sales line. | Our calculation |
| Competition at the same target | Ionis reported U.S. approval of TRYNGOLZA (olezarsen), an APOC3-targeted antisense medicine, for adults with sHTG in June 2026. This identifies a competing modality and is not a head-to-head comparison. | Facts |
| Sale of future royalties | Royalty Pharma is entitled to the olpasiran royalties otherwise payable by Amgen to Arrowhead. The FY2025 10-K states that Arrowhead remained eligible for up to US$485 million of additional development, regulatory and sales milestones from Amgen and Royalty Pharma; this is conditional future value, not current revenue. | Facts |
| Extrahepatic clinical validation | Muscle and CNS programs were at early clinical or preclinical stages in the cited filings. Delivery-platform potential does not establish regulatory approval or clinical success for those indications. | Forward-looking |
12. Glossary
- siRNA
- Small interfering RNA: a short RNA duplex that engages the RNA-interference pathway to reduce a selected messenger RNA and its encoded protein.
- TRiM
- Targeted RNAi Molecule: Arrowhead's platform combining siRNA with targeting ligands and selected chemical modifications for delivery and activity.
- GalNAc
- N-acetylgalactosamine, a sugar used in multivalent ligands that bind hepatocyte receptors and facilitate delivery to the liver.
- APOC3
- The gene encoding apolipoprotein C-III, a protein involved in slowing triglyceride clearance. APOC3 is the RNA target discussed in this profile.
- Familial chylomicronemia syndrome (FCS)
- A rare disorder of triglyceride clearance associated with very high circulating triglycerides. The U.S. REDEMPLO indication is for adults with FCS as an adjunct to diet.
- Severe hypertriglyceridemia (sHTG)
- A category of elevated triglycerides, generally at least 500 mg/dL in the development context cited here. It is not interchangeable with FCS.
- Royalty monetization
- Financing obtained by transferring rights to potential future royalty payments in return for cash; it reduces the seller's participation in those future royalties.
- GMP
- Good Manufacturing Practice: requirements for controlled pharmaceutical manufacturing and quality systems. Stated GMP capacity should not be equated with actual output or product demand.
 AI-generated conceptual illustration
13. References
- Arrowhead Pharmaceuticals FY2025 Form 10-K, filed November 25, 2025. Used for the corporate overview, TRiM, partnerships, facilities, employees, patents, financial results and financing. Financial tables are reported in thousands of U.S. dollars; figures in this profile are converted to millions where stated. https://www.sec.gov/Archives/edgar/data/879407/000087940725000029/arwr-20250930.htm
- Arrowhead Pharmaceuticals Form 10-Q for the quarter ended June 30, 2026, filed August 4, 2026. Used for nine-month results, collaboration revenue, liquidity, financing, partnerships, regulatory developments and pipeline descriptions. The document also contains subsequent events; reporting-period data and later developments are distinguished. https://www.sec.gov/Archives/edgar/data/879407/000087940726000057/arwr-20260630.htm
- U.S. National Library of Medicine — DailyMed REDEMPLO (plozasiran) U.S. prescribing information. Used for the labeled indication and regimen, molecular composition, chemical modifications, and the PALISADE study comparison. This profile does not replace the prescribing information. https://dailymed.nlm.nih.gov/dailymed/drugInfo.cfm?setid=7fd37993-f85a-4af1-8bbe-133299f226ed
- Ionis Pharmaceuticals SEC-filed company announcement dated June 24, 2026 reporting U.S. approval of TRYNGOLZA (olezarsen) in adults with sHTG. Used to identify an APOC3-targeted competitor, not to infer comparative efficacy. https://www.sec.gov/Archives/edgar/data/874015/000114036126026232/ef20076807_ex99-1.htm
- Arrowhead Pharmaceuticals Official corporate website, used to identify the company and its logo. https://arrowheadpharma.com/
14. Claim-to-source audit
| Claim or topic | Evidence type | Source |
|---|---|---|
| Legal name, Delaware incorporation, headquarters, Nasdaq listing and September 30 fiscal year-end. | Facts | Source 1 https://www.sec.gov/Archives/edgar/data/879407/000087940725000029/arwr-20250930.htm |
| Partnering of programs not intended for in-house commercialization, non-dilutive funding strategy and clinical-stage candidate count. | Facts | Source 1 https://www.sec.gov/Archives/edgar/data/879407/000087940725000029/arwr-20250930.htm |
| FY2024 and FY2025 revenue, FY2025 revenue composition, R&D expense and net results attributable to Arrowhead. | Facts | Source 1 https://www.sec.gov/Archives/edgar/data/879407/000087940725000029/arwr-20250930.htm |
| Nine-month revenue, collaboration and licensing revenue, R&D expense, net loss attributable to Arrowhead and liquidity at June 30, 2026. | Facts | Source 2 https://www.sec.gov/Archives/edgar/data/879407/000087940726000057/arwr-20260630.htm |
| 711 employees, research facilities, Verona GMP capacity, research arrangements and patent counts. | Facts | Source 1 https://www.sec.gov/Archives/edgar/data/879407/000087940725000029/arwr-20250930.htm |
| TRiM platform design, company-reported cell/tissue targets and extrahepatic delivery strategy. | Facts | Source 1 https://www.sec.gov/Archives/edgar/data/879407/000087940725000029/arwr-20250930.htm |
| Agreements involving Amgen, Janssen/GSK, Takeda, Royalty Pharma, Sarepta, Sanofi/Visirna, Novartis and Sixth Street. | Facts | Source 1 https://www.sec.gov/Archives/edgar/data/879407/000087940725000029/arwr-20250930.htm |
| U.S. approval of REDEMPLO on November 18, 2025. | Facts | Source 1 https://www.sec.gov/Archives/edgar/data/879407/000087940725000029/arwr-20250930.htm |
| US$200 million Novartis upfront payment; US$200 million Sarepta milestone; clinical supply agreement; Madrigal licensing; REDEMPLO regulatory developments; SHASTA, YOSEMITE, ARO-DIMER-PA and ARO-MAPT; financing; and up to US$16.2 billion in potential future milestones. | Facts | Source 2 https://www.sec.gov/Archives/edgar/data/879407/000087940726000057/arwr-20260630.htm |
| REDEMPLO composition, GalNAc conjugation, 2′ modifications, phosphorothioates, labeled regimen and PALISADE trial information. | Facts | Source 3 https://dailymed.nlm.nih.gov/dailymed/drugInfo.cfm?setid=7fd37993-f85a-4af1-8bbe-133299f226ed |
| Ionis announcement of U.S. TRYNGOLZA approval for adults with sHTG in June 2026. | Facts | Source 4 https://www.sec.gov/Archives/edgar/data/874015/000114036126026232/ef20076807_ex99-1.htm |
| Sarepta share of FY2025 revenue (approximately 84.0%); revenue residual (approximately US$3.5 million); illustrative patient-years per 100 kg of active ingredient; sulfur-to-phosphorus ratio (7/43). | Our calculation | Calculated from Sources 1–3 using the assumptions and limitations stated in the text; not additional company disclosures. |
| Three editorial industry categories: pharmaceutical companies, drug-discovery biotechs and contract research/manufacturing providers. | Our analysis | Editorial classification. Company examples are selected from this guide series. |
| Planned sHTG filing, anticipated YOSEMITE completion and phased commercial expansion, as described in the cited filings. | Forward-looking | Sources 1 and 2. Company plans are not confirmed outcomes or a complete current-status update. https://www.sec.gov/Archives/edgar/data/879407/000087940726000057/arwr-20260630.htm |
| Unverified details: SHASTA assessment time point, subsequent sHTG filing/approval dates, validation across all cell/tissue targets and actual Verona utilization/output/capital investment. | Forward-looking | Limits of this profile's source review. Unverified details are not inferred from capacity statements or development plans. |
| Interpretation of the division between proprietary cardiometabolic programs and partnered rare muscle/CNS programs. | Editorial interpretation | Editorial interpretation of the partnership structure in Sources 1 and 2. |
| Interpretation of in-house manufacturing as a capability relevant to broader indications and partner supply. | Editorial interpretation | Editorial interpretation of the facility and manufacturing-supply disclosures in Sources 1 and 2; not a disclosed demand forecast. |
| Supply-chain considerations for obtaining specialized raw materials at manufacturing scale. | Editorial interpretation | Editorial explanation informed by Sources 1 and 3; not a finding of an actual supply shortage. |
English text and figures checked: October 17, 2026 / Troy Technical
This profile draws on Arrowhead's SEC filings and U.S. prescribing information; the reporting periods and source dates are stated above. The competitor approval reference is an SEC-filed Ionis announcement. Calculations and editorial interpretations are identified separately from company disclosures. Historical pipeline descriptions are not presented as a complete current-status update. This article is for technology and company research, not medical or investment advice, and does not recommend a medicine or a treatment decision.