COMPANY PROFILE / SEMICONDUCTOR BACK-END
ASMPT
The company shipping more of the tools that stack AI chips than anyone else
ASMPT builds the equipment used to assemble and package semiconductors, and the equipment used to mount components onto circuit boards. By the standards of the equipment industry its revenue is modest. It nonetheless appears in every discussion of HBM and large AI packages, because it is a principal supplier of thermo-compression bonding (TCB) tools, which join chips under heat and pressure. In 2025 its TCB revenue grew roughly 2.5 times, even as it was divesting and reviewing other businesses.
- ASMPT in 30 seconds
- The logo and how the name is written
- What the company actually does: selling the tools, not the chips
- Scale: five years of revenue
- Company category and position in the back-end industry
- Sites and the countries where it manufactures
- Leading products and share in semiconductor back-end work
- Current investment plans and the reshaping of the business
- Major corporate partners
- Where the company is heading in this field
- The risks this company carries
- Glossary, references and claim-to-source audit
1. ASMPT in 30 seconds
(US$1,762m)Continuing operations, up 10.0% year on year
(back-end and SMT equipment)It does not make chips; it makes the machines that assemble them
on SG&A and R&DMainly advanced packaging R&D and infrastructure
ASMPT does not make semiconductors. It sells the equipment used to assemble them. Its customers are therefore manufacturers such as TSMC and Samsung, and OSATs such as ASE and Amkor. Revenue of HK$13.7bn, about US$1.8bn, is an order of magnitude smaller than Applied Materials or Lam Research. But in the specific step of assembling a large AI package, it occupies a position that is hard to substitute. That shape, small in scale yet holding one particular point in the process, is the axis on which to read this company.
2. The logo and how the name is written
The ASMPT logo is a trademark of the company. This article does not reproduce it with generated imagery or illustration; where it is displayed, the genuine logo file obtained from the official website should be placed in the frame above. A logo drawn by an AI would be wrong both as a trademark and as a matter of fact.
A note on the name: the former name was ASM Pacific Technology Limited. Following a shareholder resolution on 10 May 2022, it became ASMPT Limited on 1 June that year, and the stock short name changed from ASM PACIFIC to ASMPT on 4 July. The stock code 0522 did not change. Note also that this is a different company from ASM International N.V. of the Netherlands, which held 24.65% of ASMPT at the end of 2025. The similar names are easily confused.
Official site: https://www.asmpt.com/en/3. What the company actually does: selling the tools, not the chips
It helps to place ASMPT in the sequence of steps that produce a finished semiconductor.
| Step | What happens | Who does it | ASMPT |
|---|---|---|---|
| Front end | Circuits are built into a silicon wafer | TSMC, Samsung, Intel | Not involved |
| Back end (assembly) | Wafers are diced, dies are placed on substrates, stacked and encapsulated | ASE, Amkor, in-house plants | Supplies the equipment |
| Board assembly (SMT) | Finished packages are soldered onto circuit boards | EMS companies, equipment makers | Supplies this equipment too |
The business is divided in two Sourced. One is SEMI, or Semiconductor Solutions: die bonders, wire bonders, TCB tools and other back-end equipment. The other is SMT, or Surface Mount Technology: placement machines and solder printers that put components onto boards. In 2025 SEMI brought in HK$7,380m and SMT HK$6,356m, close to an even split.
The company describes itself as "the only company in the world able to provide integrated solutions across all major steps of electronics manufacturing" Sourced. That claim to uniqueness is the company's own and has not been verified here.
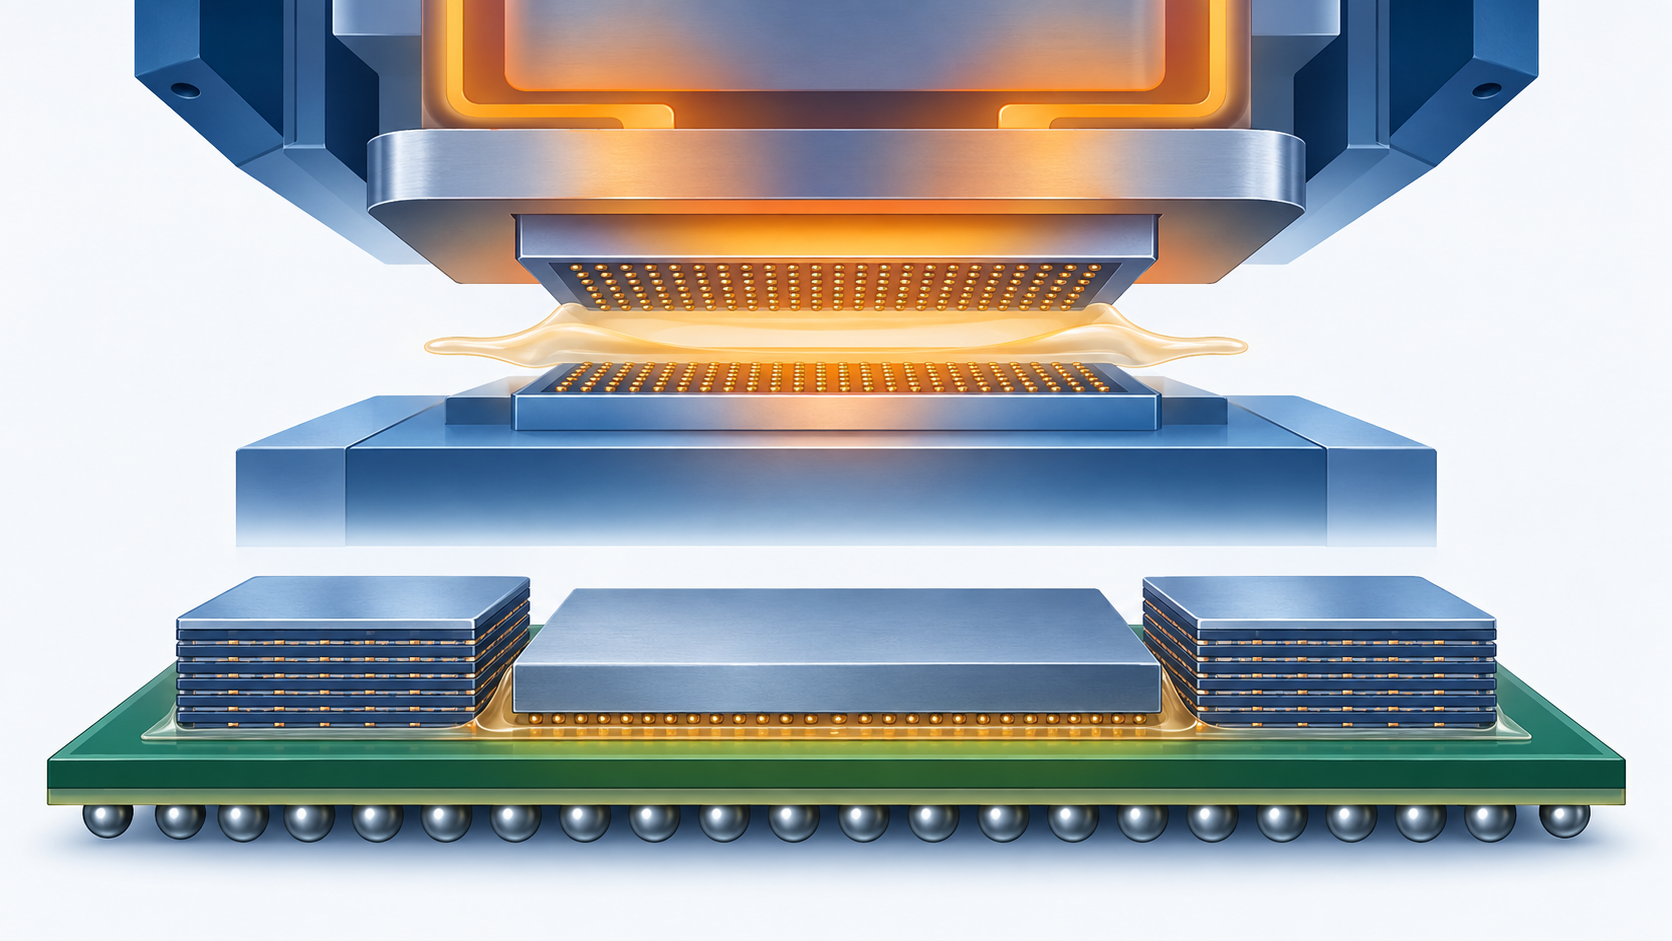
Seen from the materials side, a back-end equipment maker is the party that sets the conditions. A TCB tool places the die and then heats it while a head presses down on it. The melting point of the solder bumps, the cure temperature and viscosity of the underfill (non-conductive film, for instance), and the warpage of the substrate are all tuned to the tool's temperature and force profiles. In other words, the specification a material has to meet is usually worked backwards from a recipe that the tool fixes first. When ASMPT says it took first orders from several customers for TCB tools aimed at 12-high HBM4 Sourced, that also means the specification for that generation of non-conductive film and bonding material is starting to settle. For a materials supplier, an equipment generation change is the development calendar.
4. Scale: five years of revenue
| Year | Revenue (HK$m) | Profit before tax (HK$m) | Profit for the year (HK$m) | Note |
|---|---|---|---|---|
| 2021 | 21,948 | 4,092 | 3,175 | No split |
| 2022 | 19,363 | 3,413 | 2,618 | No split |
| 2023 | 14,697 | 1,036 | 712 | No split |
| 2024 | 12,483 | 456 | 291 | Continuing operations, restated |
| 2025 | 13,736 | 1,216 | 1,085 | Continuing operations |
All figures are on a continuing-operations basis. Separately, the discontinued NEXX operation produced a loss of HK$182m in 2025, so the combined consolidated profit was HK$902m. The group revenue figure the company announced for 2025, continuing plus discontinued, was HK$14.52bn (US$1.86bn), up 9.8%.
How much it spends on R&D and capital equipment
| Item | 2024 | 2025 |
|---|---|---|
| R&D investment | about HK$1.92bn | about HK$1.93bn |
| Purchases of property and equipment | HK$461.7m | HK$447.0m |
| Total staff costs | HK$4.90bn | HK$4.93bn |
| Dividend per share for the year | HK$0.67 | HK$1.39 |
Even with revenue nearly 40% below its peak, R&D investment was held essentially flat Sourced. The company describes this as a policy of investing in R&D across the industry cycle. Capital spending, by contrast, runs at HK$400m to HK$500m a year, barely 3% of revenue Our calculation. This is a company that uses capital in a completely different way from a chipmaker building fab after fab.
Where the roughly 9,000 employees are
| Country or region | Approximate headcount | Share |
|---|---|---|
| Mainland China | about 4,000 | about 44% |
| Germany | about 1,000 | about 11% |
| Singapore | about 900 | about 10% |
| Hong Kong | about 700 | about 8% |
| Malaysia | about 700 | about 8% |
| Portugal | about 400 | about 4% |
| United Kingdom | about 300 | about 3% |
| Other | the remainder | - |
The shares are approximations obtained by dividing the headcounts the company gave by roughly 9,000 Our calculation. A further 1,600 or so temporary and outsourced people work alongside them, and the company states that more than 2,200 staff work in research and development.
5. Company category and position in the back-end industry
The category is a manufacturer of semiconductor back-end and SMT equipment. Not a university, not a government body, and not a maker of semiconductors. Within the structure of the back-end industry it stands on the side that delivers equipment to OSATs and chipmakers.
Alongside the SEMI and SMT segments, ASMPT also explains its revenue along an advanced packaging versus mainstream axis. AP covers TCB, hybrid bonding, photonics, high-accuracy flip chip and the high-accuracy SMT tools used for AI server boards. Mainstream covers conventional wire bonders, die bonders and general-purpose placement machines. In 2025 AP grew 30.2% and mainstream 3.3%, so almost all of the growth came from the AP side Sourced. When ASMPT's name appears in back-end coverage, it is almost always about AP.
6. Sites and the countries where it manufactures
Headquarters in Singapore, listing in Hong Kong, incorporation in the Cayman Islands: the company is deliberately split across three places Sourced. Manufacturing and development are spread across Asia and Europe.
| Country or region | Main entities | Role |
|---|---|---|
| Singapore | ASMPT Singapore Pte. Ltd.; ASMPT SMT Singapore Pte. Ltd. | Head office. Manufacture and sale of semiconductor and SMT equipment. The core R&D site for SEMI advanced packaging |
| Mainland China | Entities in Huizhou, Shenzhen and Shanghai | Manufacturing and R&D for both semiconductor and SMT equipment. The largest country by headcount |
| Hong Kong | ASMPT Technology Hong Kong Limited and others | Semiconductor equipment manufacturing and R&D, plus group investment and procurement functions |
| Malaysia | ASMPT Malaysia Sdn. Bhd. | Manufacture of semiconductor and SMT equipment |
| Germany | ASMPT GmbH & Co. KG; ASMPT AMICRA GmbH | Manufacture of SMT placement and printing equipment. Munich is the core R&D site for SMT. AMICRA makes high-accuracy die bonders |
| Netherlands | ASMPT ALSI B.V. | R&D, manufacture and sale of laser dicing equipment |
| United Kingdom | ASMPT SMT UK Limited | Manufacture and sale of SMT printers, the former DEK business |
| Portugal | Critical Manufacturing, S.A. | Development and sale of manufacturing execution system (MES) software |
| Japan, United States, Taiwan, Korea | ASMPT Japan Limited and others | Sales and marketing only; no manufacturing |
This table is drawn from the principal subsidiaries listed in the 2025 Annual Report, focusing on those with manufacturing or development functions. That list covers only significant subsidiaries and is not a complete record of every site.
The company states plainly that SEMI advanced packaging R&D sits in Singapore and SMT R&D in Munich Sourced. For a materials supplier that means evaluation samples go to two different places. Non-conductive film, underfill and flux for TCB and hybrid bonding are evaluated on the Singapore side; solder paste and board-level materials on the German side. The point of contact differs. Manufacturing, meanwhile, is spread across mainland China, Malaysia and Hong Kong, so development and volume production sit in different countries. Anyone seeking qualification for a consumable that goes into the tool, such as a bonding tool tip, a heater or a stage material, should be aware that a specification approved at the development site does not automatically flow into procurement at the production site.
7. Leading products and share in semiconductor back-end work
The product family
- TCB (thermo-compression bonding)
- The die is placed, then heated under pressure so that many fine bumps join at once. Used for HBM stacking and AI logic assembly. The product driving ASMPT's AP revenue.
- Hybrid bonding
- Joining copper and dielectric surfaces directly, without solder. ASMPT is rolling out a second-generation tool; as of the first half of 2026 it is at the customer sampling stage.
- Photonics assembly tools
- Equipment for building optical transceivers. The company calls its position in 800G "dominant"; first-half 2026 revenue was close to three times the year-earlier level.
- Wire and die bonders
- Conventional back-end tools, classified by the company as mainstream. Chinese OSAT demand is the main outlet.
- SMT equipment
- Placement machines and solder printers. Growing on AI server boards and electric vehicles.
On market share, with the distinctions that matter
ASMPT does not disclose an actual market share. What it does publish about TCB is its own estimate that "the market will grow from about US$760m in 2025 to US$1.6bn in 2028" and that it is "targeting a 35 to 40% share" Not yet confirmed. Those are a company forecast and a company target, not an achieved share. This article does not use research-firm share estimates either. Three things can be stated from primary material.
- TCB revenue rose roughly 146% in 2025, a record, in the company's own words Sourced
- AP revenue was US$532.1m, up 30.2%, and 30% of group revenue against 26% a year earlier Sourced
- The company states it won first orders from several customers for TCB tools for 12-high HBM4 Sourced
There is one further number that can stand in for share: the geographic mix of revenue. TCB tools ship to the manufacturers and OSATs that handle leading-edge logic and HBM, so the share taken by Asia excluding China tracks TCB.
| End market | Share of 2025 revenue | What the company says |
|---|---|---|
| Computing | about 22% | The largest end market, with TCB the biggest part of it |
| Consumer | about 17% | Driven by mainstream products sold in China |
| Communications | about 16% | Photonics and high-end smartphones |
| Automotive | close to 16% | Mostly Chinese electric vehicles |
| Industrial | 10% | Down from 13% a year earlier on soft market conditions |
8. Current investment plans and the reshaping of the business
on SG&A and R&DMainly advanced packaging R&D and infrastructure
Closed 3 June 2026Buyer: Applied Materials, Inc.
For this company, "investment plans" do not mean new plants. They take the form of reshaping the portfolio. Three moves were disclosed across 2025 and 2026.
| Date | Event | Amount and substance | Status |
|---|---|---|---|
| 27 November 2025 | Sale of the 49% interest in Advanced Assembly Materials International (AAMI) | Received in cash and in newly issued shares of a company listed on the Shanghai Stock Exchange under code 603991. Gain on disposal HK$1.11bn | Completed. ASMPT held 18.99% of that company at the end of 2025, carried at HK$2.076bn |
| 21 January 2026 | Review of strategic options for the SMT business began | Sale, joint venture, spin-off with a listing, or retention are all under consideration | No conclusion published Not yet confirmed |
| 30 April 2026 and 3 June 2026 | Sale of NEXX, the U.S. plating equipment business, to Applied Materials | Consideration US$120m in cash, including the transfer of about US$6.7m of inventory | Closed on 3 June 2026. Estimated net gain about HK$11m |
NEXX is a U.S. electroplating and deposition equipment maker that ASMPT acquired in 2018. The company gives its reasons for selling as sharpening its focus on the back-end packaging business and letting NEXX gain continued investment and operating synergies under a new owner Sourced. ASMPT had already written off the entire HK$217.39m of goodwill allocated to NEXX in its 2025 accounts, so this was not a sale at a high price. The HKEX announcement says the US$120m was the highest bid in a competitive process and that the estimated net gain was only about HK$11m Sourced. It reads most naturally as an exit.
At the same time, the review of strategic options for SMT has been running since January 2026. Were SMT to be separated, ASMPT would lose close to half its revenue and become, in effect, a pure back-end equipment company. Which option will be taken has not been published Not yet confirmed.
9. Major corporate partners
In ASMPT's case, what is published under the heading of partnership is mostly shareholding and transactions. Technology partners are almost never named.
| Kind | Counterparty | Substance | Primary source |
|---|---|---|---|
| Major shareholder | ASM International N.V. (Netherlands) | Holds 103,003,000 shares, 24.65%, through its subsidiary ASM Pacific Holding B.V. It is the company from which ASMPT originally grew | Stated in the 2025 Annual Report Sourced |
| Associate | A lead-frame and back-end materials company listed on the Shanghai Stock Exchange under code 603991 | Shares received as consideration for the AAMI stake, giving ASMPT 18.99%. The company makes and sells lead frames and back-end materials and equipment | Stated in the 2025 Annual Report Sourced |
| Buyer of a divested business | Applied Materials, Inc. (United States) | Share purchase agreement for NEXX signed 30 April 2026, closed 3 June. A disposal, not a partnership | Stated in the HKEX announcement Sourced |
| Wholly owned subsidiary | Critical Manufacturing, S.A. (Portugal) | Manufacturing execution system software, sold in combination with the equipment | Stated in the 2025 Annual Report Sourced |
| Industry body | Semiconductor Climate Consortium | A founding member | Stated in the 2025 Annual Report Sourced |
The annual and interim reports use only phrases such as "the leading advanced logic customer", "HBM makers", "a major IDM" and "OSAT partners". Names such as TSMC, SK hynix, Samsung and Micron do not appear anywhere in ASMPT's own disclosure Not yet confirmed. The only concentration figure published is that the top five customers together are about 16% of revenue. This article does not fill the gap with press reports or guesswork.
10. Where the company is heading in this field
Anything said here is a forecast, so the established facts and the outlook drawn from them are kept apart.
What is established
| Fact | What it implies for the back end |
|---|---|
| TCB revenue grew about 146% in 2025, and AP reached 30% of group revenue | AI assembly equipment has become the company's growth engine |
| First-half 2026 continuing revenue was HK$8,903m, up 42.5% year on year | The 2025 rise was not a one-off spike; it is continuing |
| First-half 2026 bookings were HK$12,754m, up 85.1% | Bookings grew faster than revenue, so the pipeline is thickening |
| In July 2026 an OSAT customer placed a single order for more than 50 C2S TCB tools | Repeat orders are coming through on the logic side for large dies |
| Third-quarter 2026 revenue guidance is US$630m to US$690m | The company itself assumes the upswing continues |
| NEXX has been sold and SMT is under strategic review | The focus on back-end packaging equipment is tightening |
| The hybrid bonding tool is at the customer sampling stage | Volume adoption of the next-generation method is not yet settled |
Outlook
Not yet confirmed Read plainly, the facts above point towards ASMPT's position in the back end strengthening for now. The reason is that as AI chips grow larger, the number of joints in a single package grows with them, and conventional mass reflow, which melts all the solder at once, struggles to hold yield. TCB, which manages flatness and temperature one unit at a time, is being chosen as the answer.
Not yet confirmed Two things could unsettle that. One is a faster than expected move to hybrid bonding: ASMPT's second-generation tool is still at the sampling stage and no volume adoption has been announced. The other is slippage in the HBM generation schedule. In its first-half 2026 interim report the company itself says the timing of new memory tool purchases depends on "customers' HBM4 product ramp schedules" Sourced. Because an equipment maker's revenue follows its customers' investment decisions with a lag, the swings are wider here than at a chipmaker.
11. The risks this company carries
| Risk | Substance | Supporting figures |
|---|---|---|
| The portfolio is in flux | NEXX has been sold and SMT is under strategic review. The outline of the company itself could change | Announced 21 January 2026; no conclusion published Not yet confirmed |
| Strong cyclicality | Revenue fell 43% between 2022 and 2024. Equipment demand tracks customer capital spending and swings widely | HK$19,363m down to HK$12,483m Our calculation |
| Thin margins | The adjusted net margin in 2025 was 3.4%. Revenue is growing but profit is still slim | Adjusted net profit HK$466.7m against revenue HK$13,736m |
| Gross margin decline | The 2025 adjusted gross margin of 38.3% was 172 basis points below the prior year, with both SEMI and SMT down | Company disclosure Sourced |
| Geographic concentration | China is 41% of revenue, and about 44% of employees are in mainland China | Regional revenue mix and headcount distribution Our calculation |
| Customer investment timing | The company states explicitly that memory tool purchases depend on the HBM4 ramp schedule | Stated in the 2026 interim report Sourced |
| Currency | Most revenue and cost is in U.S. dollars, euros and renminbi, while the reporting currency is the Hong Kong dollar | The company discloses that it hedges with forward contracts |
| Borrowings | Debt is mainly a syndicated loan repayable in instalments to February 2029. The gearing ratio is 0.140 | Disclosed as at the end of 2025 |
For a materials supplier, the bookings and backlog of an equipment maker such as ASMPT are unusually convenient leading indicators. It takes time from installing a tool to ramping volume production, so an order taken now corresponds to consumption of non-conductive film, underfill and flux roughly a year later. First-half 2026 bookings were HK$12,754m, up 85.1% year on year, well ahead of the 42.5% rise in revenue Sourced. A state in which bookings exceed revenue, a book-to-bill above one, is a reasonable basis for pulling a materials production plan forward. Conversely, in a period like 2023 and 2024 when bookings thin out, enquiries for materials tend to stop before the tools do.
12. Glossary
- TCB
- Thermo-Compression Bonding. Joining a die under simultaneous heat and pressure. Used where a package has many fine joints.
- Hybrid bonding
- Joining copper electrodes and dielectric surfaces directly, without solder in between, which allows a finer joint pitch.
- C2S and C2W
- Chip-to-Substrate and Chip-to-Wafer, the two destinations for a TCB process.
- HBM
- High Bandwidth Memory. DRAM stacked vertically to gain bandwidth. TCB is used in the stacking step.
- OSAT
- Outsourced Semiconductor Assembly and Test. A dedicated back-end contractor, and a customer from ASMPT's point of view.
- SMT
- Surface Mount Technology, the step in which finished packages are soldered onto a circuit board.
- Book-to-bill
- Bookings divided by revenue. Above one means backlog is building.
- Discontinued operations
- An accounting presentation that separates a business being sold from the rest. At ASMPT this is NEXX.
 AI-generated concept
13. References
- ASMPT Limited Annual Report 2025 (filed with the Hong Kong Stock Exchange, 5 April 2026). Revenue, segment results, the five-year financial summary, R&D investment, equipment purchases, headcount and its distribution by country, staff costs, dividends, the principal subsidiary list, major shareholders, the classification of NEXX as a discontinued operation and its goodwill impairment, the AAMI disposal, the business review of TCB, hybrid bonding and photonics, revenue by region and end market, the top-five customer share, and the position on borrowings and currency. https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf
- ASMPT Limited Interim Report 2026 (27 August 2026). First-half revenue, bookings and profit, AP revenue of US$339m, C2S and C2W TCB order trends, the comments on HBM4, progress on hybrid bonding, completion of the NEXX sale and the breakdown of consideration, and third-quarter revenue guidance. https://www.asmpt.com/site/assets/files/85541/e_00522ir-20260827.pdf
- ASMPT Limited Full-year 2025 results announcement (HKEX filing, 4 March 2026). Segment results for the full year and fourth quarter, bookings and backlog, dividends, and the announcement of the SMT strategic options review. https://www.asmpt.com/site/assets/files/84503/e0522_results_announcement_2025_q4.pdf
- ASMPT Limited HKEX announcement, "Discloseable Transaction - Disposal of a Wholly-Owned Subsidiary" (4 May 2026). The share purchase agreement for ASMPT NEXX, Inc. signed with Applied Materials, Inc. on 30 April 2026, consideration of US$120m, and the transfer of about US$6.7m of inventory. https://doc.irasia.com/listco/hk/asmpt/announcement/a260504.pdf
- ASMPT Limited HKEX announcement, "Closing of Discloseable Transaction in Relation to Disposal of a Wholly-Owned Subsidiary" (4 June 2026). Completion on 3 June 2026, the basis on which the price was set, and the estimated net gain of about HK$11m. https://doc.irasia.com/listco/hk/asmpt/announcement/a260604.pdf
- ASMPT Limited HKEX announcement, "Change of Company Name and Stock Short Name" (24 June 2022). The change from ASM Pacific Technology Limited to ASMPT Limited effective 1 June 2022, the date the stock short name changed, and the retention of stock code 0522. https://doc.irasia.com/listco/hk/asmpt/announcement/a220624.pdf
- ASMPT Company history page on the official website: founding in 1975, the 1989 Hong Kong listing, the 2011 move of headquarters to Singapore, and the acquisition years for DEK, ALSI, NEXX and AMICRA. https://www.asmpt.com/en/company/history/
- ASMPT Official website, used to check the corporate profile and the brand wordmark. https://www.asmpt.com/en/
14. Claim-to-source audit
| Claim in the article | Category | Source |
|---|---|---|
| Legal name, incorporation in the Cayman Islands, Singapore head office address, stock code 0522 | Sourced | Reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| The name change effective 1 June 2022 and the stock short name change on 4 July 2022 | Sourced | Reference 6 https://doc.irasia.com/listco/hk/asmpt/announcement/a220624.pdf |
| Founded 1975, listed in Hong Kong 1989, headquarters moved to Singapore 2011 | Sourced | Reference 7 https://www.asmpt.com/en/company/history/ |
| Revenue, profit before tax and profit for the year, 2021 to 2025, continuing operations | Sourced | The five-year summary in reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| 2025 segment revenue: SEMI HK$7,380m and SMT HK$6,356m | Sourced | References 1 and 3 https://www.asmpt.com/site/assets/files/84503/e0522_results_announcement_2025_q4.pdf |
| Segment shares of 53.7% and 46.3%, capex as a share of revenue, and the 43% revenue decline from 2022 to 2024 | Our calculation | Derived from the amounts disclosed in reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| AP revenue of US$532.1m, up 30.2%, at 30% of group revenue against 26% a year earlier | Sourced | Reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| TCB revenue up about 146%, and first orders for 12-high HBM4 from several customers | Sourced | Reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| R&D investment of about HK$1.93bn, equipment purchases of HK$447.0m, staff costs of HK$4.93bn | Sourced | Reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| About 9,000 employees and their approximate distribution by country, about 1,600 temporary and outsourced workers, more than 2,200 in R&D | Sourced | Reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| The country shares, such as about 44% in mainland China | Our calculation | The headcounts in reference 1 divided by roughly 9,000 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| Sites and principal subsidiaries by country and function, and the R&D centres in Singapore and Munich | Sourced | Reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| Revenue by region (China 41%, Asia excluding China 34%, Europe 13%, Americas 11%) and by end market | Sourced | Reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| The top five customers at about 16% of revenue | Sourced | Reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| 2025 bookings of HK$14,478m, backlog of HK$6.17bn, book-to-bill of 1.05, dividend of HK$1.39 | Sourced | References 1 and 3 https://www.asmpt.com/site/assets/files/84503/e0522_results_announcement_2025_q4.pdf |
| First-half 2026 revenue of HK$8,903m (+42.5%), bookings of HK$12,754m (+85.1%), and third-quarter guidance | Sourced | Reference 2 https://www.asmpt.com/site/assets/files/85541/e_00522ir-20260827.pdf |
| The July 2026 order from an OSAT customer for more than 50 C2S TCB tools, and AP revenue of US$339m | Sourced | Reference 2 https://www.asmpt.com/site/assets/files/85541/e_00522ir-20260827.pdf |
| That the hybrid bonding tool is at the sampling stage and that timing depends on the HBM4 ramp | Sourced | Reference 2 https://www.asmpt.com/site/assets/files/85541/e_00522ir-20260827.pdf |
| The sale of NEXX to Applied Materials for US$120m, completed 3 June 2026, with an estimated net gain of about HK$11m | Sourced | References 4 and 5 https://doc.irasia.com/listco/hk/asmpt/announcement/a260604.pdf |
| The full HK$217.39m goodwill impairment on NEXX, the HK$1.11bn gain on the AAMI disposal and the resulting 18.99% holding | Sourced | Reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| That ASM International N.V. holds 24.65% as a major shareholder | Sourced | Reference 1 https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| The TCB market growing from US$760m in 2025 to US$1.6bn in 2028, and the 35 to 40% share target | Not yet confirmed | Reference 1. A company estimate and target, not an achieved result https://www.asmpt.com/site/assets/files/84854/e_00522ar-20260405.pdf |
| The conclusion of the SMT strategic options review | Not yet confirmed | Reference 3 records only that the review began; no decision has been published https://www.asmpt.com/site/assets/files/84503/e0522_results_announcement_2025_q4.pdf |
| ASMPT's actual market share in TCB, die bonders or SMT | Not yet confirmed | Not disclosed, and this article does not use research-firm estimates |
| The names of customer companies such as TSMC, SK hynix or Samsung | Not yet confirmed | Absent from ASMPT's own disclosure, and this article does not guess at them |
| Any new plant construction planned from 2026 | Not yet confirmed | No specific plan appears in the published material, so this article says nothing about it |
| The outlook in section 10 | Not yet confirmed | An interpretation by this article, drawn from the seven items in the facts table |
Last updated 21 September 2026 / Troy Technical
Every figure in this article comes from ASMPT Limited's statutory filings with the Hong Kong Stock Exchange or from the company's own announcements. No research-firm estimates or press-based figures have been used.