COMPANY PROFILE / SEMICONDUCTOR BACK-END
Besi
The Dutch company that became a principal supplier of hybrid bonding equipment
"BESI" and "BE Semiconductor Industries" are the same company. BESI is the abbreviation of BE Semiconductor Industries N.V., and the company writes itself as "Besi" in its annual report. It is a Dutch manufacturer that builds semiconductor assembly equipment and nothing else. It appears constantly in back-end coverage because it has become one of the few suppliers of hybrid bonding equipment, which joins a die to a wafer copper to copper, with no solder in between.
- Besi in 30 seconds
- The logo and the name: BESI and BE Semiconductor Industries are one company
- What the company actually does: assembly equipment only
- Scale: five years of revenue
- Company category and position in the back-end industry
- Sites and the countries where it manufactures
- Leading products and share in semiconductor back-end work
- Current investment plans
- Major corporate partners
- Where the company is heading in this field
- The risks this company carries
- Glossary, references and claim-to-source audit
1. Besi in 30 seconds
(back-end assembly equipment)In the company's words, "one line of business". It makes no front-end tools
Revenue of EUR 591m and slightly under two thousand staff make Besi a mid-sized equipment maker. It nonetheless sits at the centre of the back end because it is ahead in the equipment for hybrid bonding, the next way chips will be connected. The company says cumulative orders since launch in 2021 have passed 150 tools Sourced. At EUR 2m to 3.5m each the unit count is small but the money is not, and more to the point there are chips that cannot be built without this tool.
2. The logo and the name: BESI and BE Semiconductor Industries are one company
In article indexes and tag lists, "BESI" and "BE Semiconductor Industries" sometimes appear as two separate entries. They are the same company. The opening of the annual report defines the entity as "BE Semiconductor Industries N.V. ('Besi' or the 'Company')" Sourced, and the ticker on Euronext Amsterdam is BESI. From here on this article follows the company's own usage and writes "Besi".
The Besi logo and its product brands, among them Datacon, Esec, Fico and Meco, are registered trademarks or trademarks of the company.
A note on the names: Datacon (die bonders), Fico (moulding and singulation) and Meco (plating) all came into Besi through acquisitions and are still used as product brands.
Official site: https://www.besi.com/3. What the company actually does: assembly equipment only
The company defines its activity as "one line of business" Sourced: developing, manufacturing, marketing and servicing advanced packaging solutions for the semiconductor and electronics industries, with a focus on next-generation wafer-level assembly solutions for AI applications.
The annual report divides semiconductor manufacturing into front end (wafer processing) and back end (assembly and test), and states plainly that Besi's equipment is used in the back end. The specific steps are these Sourced.
| Step | What happens |
|---|---|
| Die sorting (pick and place) | Good dies are separated from rejects |
| Die bonding | A die is attached and electrically connected to a lead frame, a substrate, a wafer or another chip |
| Moulding | The assembled die is covered in resin to protect it from outside contamination |
| Plating | Chemical plating that gives the required physical properties at various stages of assembly |
| Trim and form, singulation | Cutting and shaping lead frames, and separating substrates or wafer-level devices into individual units |
The company also writes that in the 2.5D, 3D and chiplet architectures used for generative AI, hybrid bonding and thermo-compression bonding have moved into the front-end manufacturing process Sourced. A back-end equipment maker now ships tools into front-end fabs. That is the shift contained in the sentence.
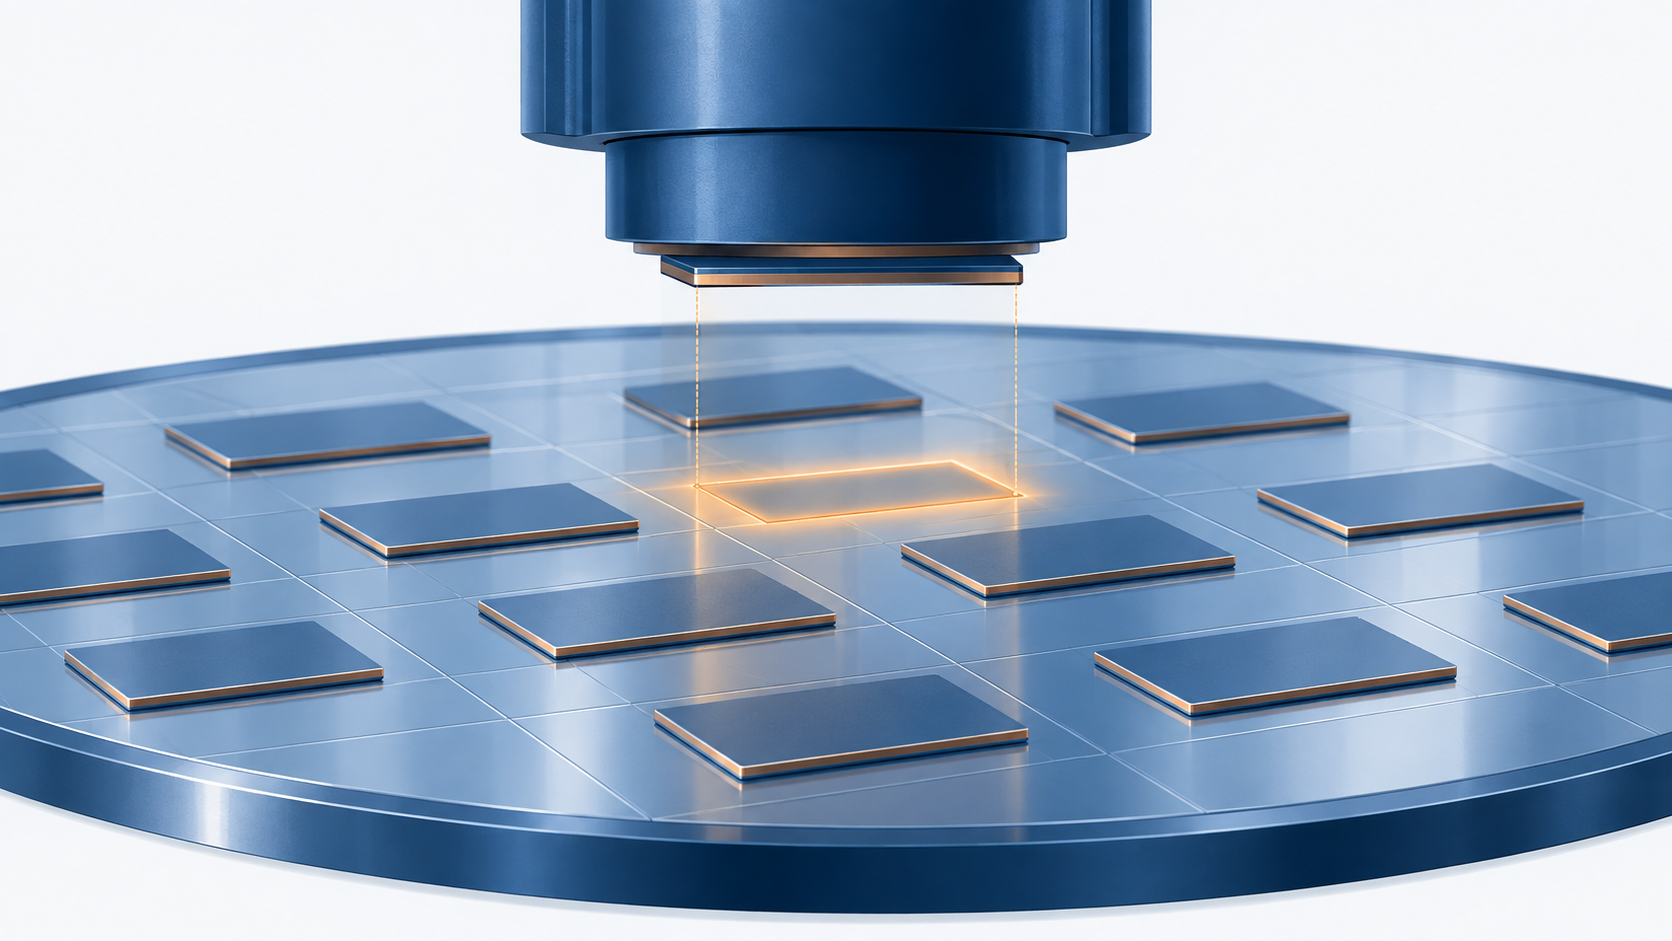
The company describes hybrid bonding like this: it "replaces the reflowed flip chip solder bumps with a direct copper-to-copper connection between chip and wafer" Sourced. Seen from the materials side, that is a quiet tectonic shift. If the solder bump goes, so do the flux, the underfill and the whole thermal history of the reflow oven. What is needed instead is a surface flat at the atomic scale, cleanliness that tolerates not one particle, and an oxide design that accounts for the thermal expansion of copper. The company lists the benefits as substantially higher data transfer rates and chip density, with lower power consumption, heat dissipation and cost of ownership. Turned around, that means a move to a method in which variation previously absorbed by the material is absorbed instead by surface preparation and machine accuracy. For suppliers of underfill and flux the demand structure itself changes; for materials used in post-CMP cleaning, planarisation and surface activation, a new market opens.
4. Scale: five years of revenue
| Year | Revenue (EUR m) | Bookings (EUR m) | Operating income (EUR m) | Net income (EUR m) | R&D expense (EUR m) |
|---|---|---|---|---|---|
| 2021 | 749.3 | 939.1 | 317.6 | 282.4 | 36.4 |
| 2022 | 722.9 | 663.7 | 294.1 | 240.6 | 53.9 |
| 2023 | 578.9 | 548.3 | 213.4 | 177.1 | 56.4 |
| 2024 | 607.5 | 586.7 | 195.6 | 182.0 | 74.3 |
| 2025 | 591.3 | 685.0 | 173.1 | 131.6 | 81.0 |
Gross margin rose from 59.6% in 2021 to 63.3% in 2025, while the operating margin fell from 42.4% to 29.3%. The main reason is that R&D expense multiplied 2.2 times in four years Our calculation.
Revenue fell 21.1%, from EUR 749.3m in 2021 to EUR 591.3m in 2025 Our calculation, because this was the period in which conventional assembly tools for smartphones and cars were weak. Throughout it the company kept raising R&D expense, from EUR 36.4m to EUR 81.0m. What that decision, to multiply development spending 2.2 times while revenue shrank, was aimed at becomes clear from the hybrid bonding numbers in section 7 Our calculation.
The sharp turn in 2026
| Measure | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue (EUR m) | 292.1 | 434.7 | +48.8% |
| Bookings (EUR m) | 259.9 | 562.6 | +116.5% |
| Net income (EUR m) | 63.6 | 140.6 | +121.1% |
| Net margin | 21.7% | 32.3% | +10.6 points |
The H1 2025 amounts are reference values worked backwards from the H1 2026 results and percentage changes the company disclosed Our calculation. The percentage changes are the company's own. Second-quarter 2026 revenue alone was EUR 249.9m with net income of EUR 89.0m, and trailing twelve-month bookings reached a record EUR 987.6m.
For the third quarter of 2026 the company guides revenue 10 to 15% above the second quarter, with gross margin easing to 63 to 65% on product mix Not yet confirmed.
5. Company category and position in the back-end industry
The category is a manufacturer of back-end assembly equipment. It makes no chips, assembles no packages and supplies no materials. It stands as the party delivering tools into the plants of OSATs, IDMs and foundries.
One thing matters a great deal in understanding this company: the price of a single tool differs enormously by process Sourced.
| Type of product | Price per tool | Lead time from order to delivery |
|---|---|---|
| Conventional assembly tools | Products with an average selling price above EUR 400,000 make up a large part of revenue | Roughly 4 to 12 weeks |
| Sub-micron accuracy wafer-level tools (hybrid bonding, TC Next) | EUR 2m to 3.5m | 6 to 9 months |
The company states that growth in hybrid bonding and TC Next raises both its average selling price and its lead times. Because the gap between order and revenue recognition lengthens, quarterly results swing more widely.
6. Sites and the countries where it manufactures
The company's own description is simple: headquarters in Duiven in the Netherlands, eight development and production sites across Asia and Europe, and thirteen sales and service sites in Europe, Asia and North America Sourced.
| Region | Sites the company names | Role as stated in the text |
|---|---|---|
| Netherlands | Duiven (head office), Den Bosch | Head office. The company bought the Duiven building for EUR 15.7m in 2025 |
| Austria | Radfeld | Development headcount substantially increased. A cleanroom is in place |
| Switzerland | Steinhausen | Listed in the operating profile |
| China | Leshan, Suzhou, Chengdu, Shenzhen, Shanghai | Leshan is named as a site running on renewable energy |
| Malaysia | n/a | A 125,000 square foot site opened in 2023. Cleanroom capacity doubled in 2025 |
| Singapore | n/a | A cleanroom is in place. Advanced packaging capacity expanded in 2025, and development headcount increased |
| Vietnam | n/a | A production site was established in 2024. Construction of a new plant is planned to start in 2026 |
| Elsewhere | Chandler (United States), Taiwan, Korea, Thailand, the Philippines, India | Listed in the operating profile. Service support was strengthened in Taiwan and North America |
Which sites are production and which are sales and service is shown only as a map in the annual report, and could not be read reliably from the PDF used here Not yet confirmed. Rows that give only a country do so because the company gives only a country.
What stands out in that table is that Besi, an equipment maker, operates cleanrooms in three places: Austria, Malaysia and Singapore Sourced. The company gives the purpose as meeting future hybrid bonding demand and supporting customers' processes. Hybrid bonding is a step in which wafer surface cleanliness and flatness decide the yield directly. Before a tool ships, conditions have to be established in the maker's own cleanroom using the customer's wafers. In other words this company is not only selling machines; it is developing the bonding process jointly with the customer. For a materials maker that means the specification for surface preparation, cleaning and CMP slurry may well be settled here.
7. Leading products and share in semiconductor back-end work
What hybrid bonding is
The company's own words, reproduced directly Sourced.
"Hybrid bonding is the most important evolution in die-to-die interconnect technology in wafer-level assembly. It replaces the reflowed flip chip solder bumps with a direct copper-to-copper connection between chip and wafer. Compared with flip chip assembly it substantially increases data transfer speeds and chip density while reducing power consumption, heat dissipation and cost of ownership. It also facilitates the development of 3D chip architectures, increasing performance, functionality and complexity in both logic and memory."
Used alongside it is thermo-compression bonding (TCB), which does use solder bumps but joins them under heat and pressure in a 2.5D assembly process. The company describes the two as "interchangeable and complementary, used according to the size, accuracy, density, complexity and throughput required, and the cost of ownership" Sourced.
How far adoption has gone
| Measure | Figure | As of |
|---|---|---|
| Cumulative hybrid bonder orders | More than 150 tools | Since launch in 2021, through the end of 2025 |
| Customers that have adopted it | 15, rising to 21 | End of 2025, then end of Q2 2026 |
| Integrated hybrid bonding line | 6 platforms with 30 hybrid bonders | First installed at a major logic customer in 2025 |
| Next-generation prototype | Placement accuracy of 50 nanometres | Completed in 2025 and available for customer qualification |
| TC Next adopters | 5 customers, in logic, memory and photonics | 2025 |
The 2025 Annual Report says adoption expanded to 18 customers, a group that includes the largest global logic and memory producers, foundries, subcontract assemblers and research institutes, while the first-half 2026 report says 15 as of the end of 2025. The counting basis evidently differs, but neither document explains the difference Not yet confirmed. This article uses the latter for the time-series comparison.
On market share, plainly
Besi does not officially disclose a market share for hybrid bonding equipment. The annual report does cite third-party research estimates of the size of the assembly equipment market, but this article does not use research-firm estimates and therefore does not reproduce those figures Not yet confirmed. What the company itself states goes no further than a qualitative claim: that it holds a leadership position in developing and selling hybrid bonding equipment to the industry's principal producers.
Where the customers are concentrated
Unlike most equipment makers, this company lists its customers by name in the annual report Sourced. That is unusual.
| Category | Customers the company names |
|---|---|
| Customers listed, alphabetically | Amkor, ASE, Fabrinet, Forehope, Huatian, Infineon, InnoLight, Intel, LG Innotek, JCET, Luxshare, Nvidia, STMicroelectronics, TDK, Texas Instruments, Tongfu, Unisem, TSMC |
| Concentration measure | 2024 | 2025 |
|---|---|---|
| Customers accounting for 10% or more of revenue | One, at 14.7% | None |
| Top ten customers as a share of revenue | n/a | About 44% |
| Asian customers as a share of revenue | 67.0% | 76.0% |
How much each customer bought is not disclosed Not yet confirmed. The list gives the names of companies it does business with, not an order of size.
8. Current investment plans
As an equipment maker its capital spending is small, and the fuel for growth goes into R&D and capacity instead. The capacity expansions carried out and disclosed in 2025 were these Sourced.
- Cleanroom capacity in Malaysia doubled, at the 125,000 square foot site opened in 2023
- Advanced packaging capacity in Singapore expanded, with the cleanroom facility completed
- Production capacity in Vietnam expanded, following the establishment of a site in 2024, with construction of a new plant planned to begin in 2026
- Development headcount substantially increased in Austria and Singapore, and service support added in Taiwan and North America
Total capital allocated in 2025 was EUR 254.8m, more than the EUR 131.6m of net income earned that year Sourced. It went to dividends and buybacks: a dividend of EUR 1.58 per share, a payout ratio of 95%, a completed EUR 100m buyback programme and a new EUR 60m programme begun. The company returns more than it earns while still increasing R&D spending Our calculation.
9. Major corporate partners
The most important relationship is the one with Applied Materials. Here there is no question of the primary source being silent: the company sets it out clearly in the annual report Sourced.
| Kind | Counterparty | Substance | Primary source |
|---|---|---|---|
| Equity stake | Applied Materials | Acquired 9% of Besi's shares. The company frames this as strengthening advanced packaging collaboration and product strategy | 2025 Annual Report Sourced |
| Technical collaboration | Applied Materials | Promoting adoption of an integrated hybrid bonding production line built around Besi's hybrid bonders. In 2025 a first installation of six platforms with 30 tools went to a major logic customer | As above Sourced |
| Joint selling | Applied Materials | The collaboration was widened in 2025 to include joint marketing of the integrated hybrid bonding solution and technical exploration of other applications | As above Sourced |
| Customers | Amkor, ASE, Intel, Nvidia, TSMC and 13 others | Named individually in the annual report (section 7). Transaction values and contract terms are not disclosed | As above Sourced |
Applied Materials is, in the company's words, the leader in front-end wafer fabrication equipment and processes. That company holds 9% of a mid-sized back-end maker and sells a production line jointly with it. This is a sign that hybrid bonding is starting to be bought not as one back-end step but as part of front-end capital spending. Before two surfaces can be bonded, the wafer needs front-end treatment: chemical mechanical planarisation, cleaning, activation, control of dishing on the copper pads. Bonding yield is not decided by the bonder alone. So the pre-bond processing and the bonding itself are now sold as a single line. For a supplier of materials, that means the person on the other side of the table moves from back-end equipment engineering to front-end integration.
Besi's annual report does not name any competitor. Competition, price pressure and industry consolidation appear as risk items, but no company names do. This article therefore names no specific competitors in this field Not yet confirmed.
10. Where the company is heading in this field
What is established
| Fact | What it implies for the back end |
|---|---|
| Hybrid bonding adopters went from 15 at the end of 2025 to 21 at the end of Q2 2026 | It is spreading from trials into volume production |
| More than 150 cumulative orders, at EUR 2m to 3.5m each | The unit count is small but the money is becoming material to the company's future |
| Applied Materials took 9% and sells the integrated line jointly | A front-end giant has taken an equity position in back-end bonding technology |
| Trailing twelve-month bookings hit a record EUR 987.6m | 2026 revenue is likely to grow further |
| The long-term revenue target was raised from above EUR 1bn to EUR 1.5bn to 1.9bn | The company itself now assumes structural growth |
| The strategy names penetration of CoWoS, CoPoS and photonics as its focus | It is aiming at both AI accelerator packaging and optical interconnect |
Outlook
Not yet confirmed Read plainly, the facts above point towards Besi's position in the back end strengthening for now. The reason is that hybrid bonding is no longer a nice-to-have. Once chips are stacked in three dimensions, it becomes a step that has to be passed through. And by partnering with the largest front-end company, Besi has arranged to sell a line rather than a standalone machine.
Not yet confirmed Two cautions are worth holding on to. The first is that 80% of revenue is still die attach, and most of that is conventional assembly equipment. The 21.1% fall in revenue from 2021 to 2025 came from that conventional part. Growth in hybrid bonding does not make its cycle disappear. The second is the double-edged nature of the Applied Materials relationship. A company that is both a 9% shareholder and a joint-selling partner is a counterparty whose position could change if the direction of the technology changes. As of this article, the terms and duration of that collaboration have not been published Not yet confirmed.
11. The risks this company carries
What follows is the subset of the items in the company's own risk management chapter that matters in a back-end context Sourced.
| Risk | Substance | Supporting figures |
|---|---|---|
| Cyclical demand | The company names "the cyclical and seasonal nature of semiconductor demand" and seasonal and cyclical variation in orders as risks | EUR 749.3m in 2021 down to EUR 578.9m in 2023, a fall of 22.7% Our calculation |
| Customer concentration | Concentration is listed as a risk, together with the possibility that consolidation and alliances concentrate it further | 2025: top ten about 44%. In 2024 one customer was 14.7% |
| Order volatility and long lead times | Sub-micron accuracy tools carry lead times of 6 to 9 months, and bookings are recorded only when a firm order is received and accepted, so quarterly results swing widely | Stated by the company |
| Dependence on Asia | About 76% of 2025 revenue came from Asian customers and 68% of employees are in Asia, with a substantial part of production capacity in the Asia-Pacific region | Disclosed in the annual report |
| Operating conditions in China | The company cites government pressure to use local suppliers, demands to transfer intellectual property, and preferential treatment of local competitors, noting that these challenges apply particularly in China | Risk management section of the annual report |
| Tariffs and export controls | The first-half 2026 report states that tariffs, additional levies, trade restrictions and export controls could weigh on end-user demand and customer investment, and add supply chain complexity and manufacturing cost | First-half 2026 report |
| Concentration in Europe | "Significant operations in Europe" is listed as a risk. The development core sits in the Netherlands, Austria and Switzerland | Risk management section of the annual report |
| Investment in R&D | Investment in research and development is itself listed as a risk. R&D expense multiplied 2.2 times in four years, from EUR 36.4m to EUR 81.0m, pushing down the operating margin | Operating margin from 42.4% to 29.3% Our calculation |
With Besi the first thing to look at is not revenue but bookings. Sub-micron accuracy tools carry lead times of 6 to 9 months, so bookings tell you what revenue will be doing more than half a year ahead. In 2025 revenue fell, yet bookings turned up first at +16.8%, and first-half 2026 revenue then rose 48.8% Our calculation. The second thing to watch is the number of hybrid bonding adopters, which the company updates every half year: 15 at the end of 2025 and 21 at the end of the second quarter of 2026. Unit counts and amounts are not disclosed, but the customer count works as a proxy for whether companies that were trying the technology have become companies that keep using it.
12. Glossary
- Hybrid bonding
- Joining the copper pads of a die and a wafer directly, without solder bumps. It allows finer, denser wiring and suits three-dimensional stacking.
- TCB
- Thermo-Compression Bonding. Joining solder bumps under heat and pressure, used in 2.5D assembly.
- Die attach
- The step of placing and joining a die onto a lead frame, a substrate or another chip. About 80% of Besi's revenue comes from this product group.
- Wafer-level assembly
- Placing dies or chiplets directly onto a high input-output density wafer, without a lead frame or substrate in between. Required below the 3 nanometre generation.
- Singulation
- Cutting packages that were built together into individual units.
- Lead frame
- The metal frame that carries a die and becomes its external terminals. The most traditional assembly approach.
- Bookings
- The value of firm orders received in a period. For an equipment maker it leads revenue. Besi records bookings only when a firm order is received and accepted.
- AEX index
- The headline share index of Euronext Amsterdam. Besi is a constituent.
 AI-generated concept
13. References
- BE Semiconductor Industries N.V. Annual Report 2025 (the PDF corresponding to the ESEF filing with the Dutch Authority for the Financial Markets). Company profile, legal name and abbreviation, year of incorporation and listing, five years of revenue, bookings, operating income, net income, R&D expense and headcount, revenue by product group, the list of customer names, customer concentration, revenue by region, sites and capacity expansion, capital expenditure, capital allocation, the collaboration with Applied Materials and its 9% stake, the state of hybrid bonding adoption, and risk management. https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf
- BE Semiconductor Industries N.V. Unaudited Interim Consolidated Financial Statements for the six months ended June 30, 2026. First-half and second-quarter revenue, bookings and net income, trailing twelve-month bookings, the progression of hybrid bonding adopters, third-quarter guidance, the comments on tariffs and export controls, and the registered office address. https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Half_Year_2026_Report.pdf
- BE Semiconductor Industries N.V. Official website, used to check the company name and the product brands. https://www.besi.com/
14. Claim-to-source audit
| Claim in the article | Category | Source |
|---|---|---|
| That BESI and Besi are abbreviations of BE Semiconductor Industries N.V. and denote one company | Sourced | The definition in the company profile of reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Head office address, incorporation May 1995 and listing December 1995, Euronext Amsterdam BESI, AEX constituent, ADR BESIY | Sourced | References 1 and 2 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| 2025 revenue 591.3, bookings 685.0, operating income 173.1, net income 131.6 and R&D 81.0 (EUR m) | Sourced | "Key Highlights" in reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Revenue, bookings, operating income, net income and R&D expense for 2021 to 2024 | Sourced | "Key Highlights" in reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| The 21.1% revenue decline from 2021 to 2025, the 22.7% decline to 2023, the 2.2 times growth in R&D and R&D at 13.7% of revenue | Our calculation | Derived from the figures in reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Gross margin 63.3%, operating margin 29.3% and net margin 22.3% in 2025, and the five-year progression | Sourced | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| 1,964 employees (1,856 fixed plus 108 temporary), 66% in Asia | Sourced | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| The company's definition of its business and the back-end steps its tools address | Sourced | "Company Profile" in reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| The definition of hybrid bonding, its benefits and its relationship to TCB | Sourced | "Company Profile" in reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Revenue by product group: die attach about 80%, packaging about 17%, plating about 3% | Sourced | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| The company estimates that about 70% of revenue was advanced packaging and about 60% needed sub-7-micrometre accuracy | Sourced, though a company estimate | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| AI-related system bookings at about 60% in the first half of 2026 | Sourced, though a company estimate | Reference 2 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Half_Year_2026_Report.pdf |
| Tool prices (conventional above EUR 400,000 on average, sub-micron EUR 2m to 3.5m) and lead times of 4 to 12 weeks and 6 to 9 months | Sourced | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| More than 150 cumulative hybrid bonder orders, the first integrated line of six platforms and 30 tools, the 50 nanometre prototype and five TC Next adopters | Sourced | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Adopters rising from 15 at the end of 2025 to 21 at the end of the second quarter of 2026 | Sourced | Reference 2 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Half_Year_2026_Report.pdf |
| The discrepancy between "18 customers including research institutes" in the annual report and "15" in the interim report | Not yet confirmed | References 1 and 2 differ and neither document explains the difference https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| The list of 18 named customers including Amkor, ASE, Intel, Nvidia and TSMC | Sourced | "Our customers" in reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Customer concentration (no customer above 10% in 2025, top ten about 44%, one at 14.7% in 2024) and Asian customers at 76.0% | Sourced | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| The structure of sites: head office in Duiven, eight development and production sites, thirteen sales and service sites | Sourced | References 1 and 2 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| 2025 capex of EUR 21m including EUR 15.7m for the Duiven building, and the 2026 plan of EUR 10m to 12m for Vietnam | Sourced | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Cleanrooms in Austria, Malaysia and Singapore, the 125,000 square foot Malaysian site of 2023, and the Vietnamese site of 2024 | Sourced | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Capital allocation of EUR 254.8m, a dividend of EUR 1.58 per share, a 95% payout ratio, the completed EUR 100m buyback and the new EUR 60m programme | Sourced | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| The observation that shareholder returns exceeded net income | Our calculation | Comparing the capital allocation figure with net income in reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Applied Materials' 9% stake, the integrated hybrid bonding line collaboration and its widening into joint marketing | Sourced | Reference 1 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| The long-term revenue target raised to EUR 1.5bn to 1.9bn for 2025 to 2029 | Not yet confirmed | Reference 1. A company target, not an achieved result https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| First-half 2026 revenue 434.7, bookings 562.6 and net income 140.6 (EUR m), a 32.3% net margin, second-quarter revenue 249.9 and net income 89.0, and trailing twelve-month bookings of 987.6 | Sourced | Reference 2 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Half_Year_2026_Report.pdf |
| The first-half 2025 amounts of 292.1, 259.9 and 63.6 (EUR m) | Our calculation | Worked backwards from the first-half 2026 results and percentage changes in reference 2 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Half_Year_2026_Report.pdf |
| Third-quarter 2026 guidance of revenue 10 to 15% above the second quarter and gross margin of 63 to 65% | Not yet confirmed | Reference 2. A company forecast https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Half_Year_2026_Report.pdf |
| The risk items: cyclicality, customer concentration, concentration in Europe, conditions in China, R&D investment, tariffs and export controls | Sourced | References 1 and 2 https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Market share in hybrid bonding equipment | Not yet confirmed | Not disclosed, so this article states no figure |
| The size of the assembly equipment market | Not yet confirmed | The annual report cites third-party research estimates, which this article does not adopt |
| The names of competitors | Not yet confirmed | Absent from reference 1, so this article names none https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| Transaction values per customer, the breakdown of the eight production sites and the capacity of each | Not yet confirmed | None of these is disclosed, so this article states nothing about them |
| The terms and duration of the Applied Materials collaboration | Not yet confirmed | Reference 1 records only that the collaboration exists; details are unpublished https://www.besi.com/fileadmin/data/Investor_Relations/_Semi__Annual_Reports/Annual_Report_2025.pdf |
| The outlook in section 10 | Not yet confirmed | An interpretation by this article, drawn from the six items in the facts table |
Last updated 21 September 2026 / Troy Technical
Every figure in this article comes from the annual report and interim financial statements published by BE Semiconductor Industries N.V. The company is listed in the Netherlands and has no U.S. SEC filing obligation, so no SEC documents exist. No research-firm estimates or press-based figures have been used.