COMPANY PROFILE / SEMICONDUCTOR BACK-END
KLA Corporation
US$13.6bn of revenue from finding things, not making them
KLA is an equipment maker that specialises in inspection and metrology. With one narrow exception it does not build the tools that create circuits. It looks at what has been built and finds the defects and the dimensional drift. That is the whole business. In the back end, where chips are stacked on top of one another, a defect nobody sees turns the entire finished package into scrap, and the value of that finding work rises sharply as a result. This profile uses published material only to explain why, of the three equipment makers, KLA is the one with the most explicit back-end product line.
- KLA in 30 seconds
- The logo and how the name is written
- What the company actually does: the business of process control
- Scale: five years of revenue
- Company category and position in the back-end industry
- Sites and the countries where it manufactures
- Leading products and share in semiconductor back-end work
- Current investment plans
- Major corporate partners
- Where the company is heading in this field
- The risks this company carries
- Glossary, references and claim-to-source audit
1. KLA in 30 seconds
Ticker KLACA ten-for-one stock split took effect on 11 June 2026
(inspection and metrology)Three reporting segments, every one of which carries back-end products
Of the three equipment makers, KLA alone gives "Packaging Manufacturing" a line of its own in its product listing Sourced. Under it sit inspection, metrology and chemical process control tools for wafer-level packaging (WLP), panel-level packaging (PLP) and IC substrates, named model by model. In other words the back end is not something KLA does on the side of its front-end business: it has been a named business area from the start. What is not published is how much revenue it produces Not yet confirmed.
2. The logo and how the name is written
The KLA logo is a registered trademark of the company. This article does not redraw it or generate an imitation. Where it is displayed, the frame above should hold the genuine logo file taken from the official site. A logo traced by an AI model is wrong both as a trademark and as a matter of fact.
A note on style: material published before 2019 uses the old hyphenated name, KLA-Tencor. Statutory filings now use KLA Corporation consistently, but the old name survives in older documents, such as the indentures for notes issued in 2014. The three letters are always said separately, K-L-A, never run together as a word.
Official site: https://www.kla.com/3. What the company actually does: the business of process control
The tools in a semiconductor plant divide broadly into two kinds.
| Kind | Job | Does it touch the wafer? | Examples |
|---|---|---|---|
| Process equipment | Deposits films, removes them, exposes them to light, plates them | Yes | Applied Materials, Lam Research, ASML, Tokyo Electron |
| Process control equipment | Looks at the result and measures defects and dimensions | No | KLA, Onto Innovation, Hitachi High-Tech |
KLA is the leading example of the second kind. It describes its business as process control and yield management solutions Sourced. Wafers, reticles (the masters used in lithography), ICs, IC substrates, printed circuit boards and packages: for every one of them, KLA sells a machine whose job is to find what has gone wrong.
There are three reporting segments Sourced.
| Segment | What it contains | FY2026 revenue | Share | Year on year |
|---|---|---|---|---|
| Semiconductor Process Control | Semiconductor inspection, metrology, chemical process control and software. The company proper | US$12,244.73m | 90% | +12% |
| Specialty Semiconductor Process | Vacuum deposition and etch tools under the SPTS brand. The one place where KLA does make things | US$584.06m | 4% | -1% |
| PCB and Component Inspection | Board imaging and inspection under the Orbotech brand, and packaged-IC inspection under the ICOS brand | US$750.42m | 6% | +21% |
The shares are this article's own arithmetic Our calculation. Segment revenue excludes internal allocations and currency effects, so the three figures add up to slightly less than consolidated revenue.
One more number shapes this company's character: 23% of revenue is service income Sourced. The company describes it as arising from subscription-like arrangements. A tool is not sold once and forgotten; maintenance revenue keeps arriving for as long as the installed tool runs. FY2026 service revenue was US$3,125.94m, up 16% year on year.
In the front end, a defect found part way through a wafer costs you that one chip. In the back end, the problem surfaces after several already-good chips have been assembled into a single package. On an AI accelerator with two HBM stacks, one bad joint can send a dozen or more expensive known-good dies to the bin. The economics of checking before you stack are of a different order from the front end. The same logic holds on the materials side: voids in the underfill, incomplete mould-compound fill, thickness variation in a plated layer, none of them can be seen from outside once the package is sealed. KLA's chemical monitoring tools (QualiSurf, Quali-Fill Libra and the rest) appear in the product listing as instruments that analyse and monitor the wet chemistries used in WLP, PLP and IC substrates precisely because the demand to measure things before they disappear from view is real Sourced.
4. Scale: five years of revenue
| Fiscal year (year end) | Revenue (US$k) | Net income (US$k) | R&D expense (US$k) | Capex (US$k) |
|---|---|---|---|---|
| FY2022 (30 June 2022) | 9,211,883 | 3,321,807 | 1,105,254 | 307,320 |
| FY2023 (30 June 2023) | 10,496,056 | 3,387,277 | 1,296,727 | 341,591 |
| FY2024 (30 June 2024) | 9,812,247 | 2,761,896 | 1,278,981 | 277,384 |
| FY2025 (30 June 2025) | 12,156,162 | 4,061,643 | 1,360,334 | 335,259 |
| FY2026 (30 June 2026) | 13,579,476 | 4,830,771 | 1,532,118 | 375,945 |
KLA's income statement carries no operating income line; it runs straight from revenue and costs to income before taxes, so net income is shown here instead. The FY2024 decline includes a US$239.10m impairment of goodwill and intangible assets.
What stands out about this company is how profitable it is. FY2026 gross margin was 61.3% and net margin 35.6% Our calculation. A company that measures earns more than a company that makes, because a measuring tool connects directly to customer yield, a benefit that converts into money without argument. R&D expense ran at 11.3% of revenue and capital expenditure at 2.8%, which next to Applied Materials (capex at 8.0% of revenue) is a notably light footprint in its own plants Our calculation.
How the 17,000 employees break down
| Dimension | Breakdown |
|---|---|
| Region | Asia about 50% / United States about 31% / Europe and the Middle East about 19% |
| Function | Customer service about 27% / R&D about 27% / manufacturing about 21% / other about 21% / sales and marketing about 4% |
| Unions | No employees are represented by a union, although there is a union delegation in Belgium and works councils at two German business units |
As of 30 June 2026. That customer service is the same size as R&D is consistent with service income being 23% of revenue.
5. Company category and position in the back-end industry
The category is a manufacturer, of inspection and metrology equipment. What sets its back-end position decisively apart from Applied Materials and Lam Research is that all three of its segments touch the back end.
KLA does not disclose its back-end (advanced packaging) revenue Not yet confirmed. The Form 10-K goes no further than three qualitative statements.
- "The increasing complexity and value of semiconductor packages, led by AI and HPC, is driving significant growth in our advanced packaging business" Sourced
- On the 12% growth of Semiconductor Process Control, the company cites strong customer adoption of its advanced packaging products as one contributing factor Sourced
- On the 21% growth of PCB and Component Inspection, it says the main driver was higher demand from customers investing in advanced packaging technology Sourced
Revenue by product category is disclosed, and is given below for reference Sourced. But every one of these categories contains some back-end business, and it cannot be separated out.
| Product category | FY2024 | FY2025 | FY2026 | FY2026 share |
|---|---|---|---|---|
| Wafer inspection | 4,333,296 | 6,198,815 | 6,630,813 | 49% |
| Patterning (reticle and metrology) | 2,054,442 | 2,196,347 | 2,706,763 | 20% |
| Service | 2,329,568 | 2,683,308 | 3,125,939 | 23% |
| Specialty Semiconductor Process | 470,565 | 517,201 | 502,519 | 4% |
| PCB and component inspection | 291,161 | 355,891 | 460,320 | 3% |
| Other | 333,215 | 204,600 | 153,122 | 1% |
Figures in US$ thousands. The shares are as stated in the Form 10-K.
6. Sites and the countries where it manufactures
| Function | Main countries | Notes |
|---|---|---|
| Headquarters | United States | Milpitas, California |
| Principal manufacturing sites | United States, Singapore, Israel, China, several European countries | Unlike Applied Materials, KLA also manufactures in China |
| Principal R&D sites | United States, United Kingdom, India, China, Singapore, Israel | The UK site is the home of SPTS, the Specialty Semiconductor Process business |
| Sales and service sites | Every major semiconductor manufacturing region | 27% of employees work in customer service |
The company states explicitly that it does not allocate assets to segments, because many of its facilities support several businesses and technologies at once Sourced.
What stands out in FY2026 is Taiwan up 13.7% and Korea up 26.2% Sourced. The company attributes the Taiwanese growth to leading-edge investment in foundry and logic, memory and advanced packaging, and the Korean growth to memory customers investing to support their HBM and advanced DRAM roadmaps. Seen from the materials side, both of those are demand around interposers and HBM stacking. China, by contrast, was flat, and the company states why in plain terms. Regional revenue movements can therefore be read directly as a signal of where materials demand is migrating.
7. Leading products and share in semiconductor back-end work
The products listed under "Packaging Manufacturing"
In the product listing of the Form 10-K, KLA places a row called "Packaging Manufacturing" alongside Chip Manufacturing, Wafer Manufacturing and Reticle Manufacturing inside the Semiconductor Process Control segment Sourced. The technologies and products named there are as follows.
| Technology | How the company describes it | Products |
|---|---|---|
| Wafer inspection and metrology | For advanced wafer-level packaging. Lets packaging houses detect, resolve and monitor excursions, and so manage quality better | Kronos series, Micro-SR, CIRCL-AP, irArcher series, PWG5 (with the XT option), eDR7xxxAP, OmniMap RS-xxx series |
| Chemical process control | Analyses and monitors the wet chemistries used in WLP (wafer-level packaging), PLP (panel-level packaging) and IC substrates | QualiSurf series, Quali-Fill Libra series, QualiLab Elite series |
| In-situ process control | Measures the wafer environment, temperature among other things, directly during processing | The SensArray product family |
The other two segments carry back-end products as well Sourced.
| Segment | Role in the back end | Products |
|---|---|---|
| Specialty Semiconductor Process | Wafer processing technologies including etch, plasma dicing and deposition. Plasma dicing separates a wafer with plasma rather than a blade, and is a back-end step outright | SPTS Omega, Sigma, Delta and Osprey series; Primaxx series; Xactix series; SPTS Mosaic series; MVD series |
| PCB and Component Inspection (PCB side) | Direct imaging, inspection, optical shaping and inkjet additive printing for the PCB and IC substrate markets | Orbotech Corus, Infinitum, Nuvogo, Diamond, Sprint and Neos series; Serena; Lumina; the Frontline product family and others |
| PCB and Component Inspection (component side) | Inspection and metrology for quality control and yield improvement in the advanced and traditional semiconductor packaging markets | ICOS F26x, ICOS Tx series, Zeta-5xx/6xx |
On market share, plainly
No primary source could be found for KLA's share of the process control market or of back-end inspection Not yet confirmed. Figures of the form "X per cent of the world process control market" are research-firm estimates, and this article does not use them. The company's own wording carries no share figure at all: it says that the strength of its competitive position in many of its served markets is primarily attributable to its advanced technology Sourced.
Three things can be stated with confidence from primary sources.
- In each of FY2024, FY2025 and FY2026, TSMC was the only customer above 10% of revenue Sourced. KLA is the only one of the three equipment makers that names a customer outright
- "Packaging Manufacturing" stands as its own row in the product listing — primary evidence that the company treats the back end as a business area in its own right Sourced
- The FY2026 R&D description names the development of process control and process enabling solutions for front-end semiconductors and advanced packaging as a principal activity Sourced
8. Current investment plans
Against FY2026 R&D expense of US$1,532.12m, capital expenditure was US$375.95m. Shareholder returns, meanwhile, came to US$3.35bn, more than R&D and capex combined Our calculation. This is a business that does not need large plants of its own, so the cash it earns goes to development and to shareholders. On existing capacity the Form 10-K says that it is sufficient, together with planned expansions and operational improvements, to meet current requirements and anticipated near-term growth Sourced. No plan for a new plant has been published Not yet confirmed.
9. Major corporate partners
KLA names almost no specific partners in its statutory filings Not yet confirmed. It discloses in a different style from Applied Materials, which announces named joint-research counterparties every quarter. The table below is the whole of what could be confirmed from primary sources.
| Counterparty | Kind of relationship | What the primary source says |
|---|---|---|
| TSMC | Customer | Named outright in the Form 10-K as the only customer above 10% of revenue in each of FY2024, FY2025 and FY2026, chiefly in the Semiconductor Process Control segment. The exact ratio and the transaction value are not disclosed |
| The former Orbotech | Acquired brand | The Orbotech name survives across the product line of the PCB and Component Inspection segment, covering direct imaging and inspection of IC substrates |
| The former SPTS | Acquired brand | The SPTS name carries the product line of the Specialty Semiconductor Process segment, tied to the R&D site in the United Kingdom |
| The former Tencor Instruments | Merger counterparty | Merged with KLA Instruments in April 1997 to form KLA-Tencor Corporation. Tencor began operating in 1976 |
The companies commonly mentioned alongside KLA in the back-end supply chain, meaning the OSATs, the substrate makers and the materials suppliers, do not appear in KLA's own primary material, so this article does not treat them as partnerships Not yet confirmed.
10. Where the company is heading in this field
What is established
| Fact | What it implies for the back end |
|---|---|
| The Form 10-K states that the advanced packaging business is growing significantly | The company itself positions the back end as a growth area |
| "Packaging Manufacturing" exists as its own row in the product listing | The back end is a named product line, not an adjunct |
| PCB and Component Inspection grew 21%, driven mainly by customer investment in advanced packaging | Demand for IC substrate and packaged-IC inspection is genuinely rising |
| Taiwan up 13.7% and Korea up 26.2%, with advanced packaging and HBM cited as the reasons | The two regions where the back end is fought over are both growing |
| TSMC has been the only customer above 10% for three years running | The company is tied directly to the buyer of the most advanced packaging |
| First-quarter FY2027 revenue is guided at US$4.0bn plus or minus US$200m | The company is planning on growth continuing |
Outlook
Not yet confirmed Read plainly, the facts above point towards KLA's presence in the back end strengthening. The logic is simple: the more layers a package contains, the more value is locked inside it, and the more a failure costs. Inspection equipment behaves like insurance, and demand for it rises in proportion to the value of the asset it protects. Chief executive Rick Wallace said as much in the fourth-quarter release: the build-out of AI infrastructure is creating new growth opportunities in advanced packaging, where KLA's market-leading process control portfolio is well positioned Sourced.
Not yet confirmed Inspection equipment also has a structural weakness: inspection is a step you can skip. The company writes as much in its own risk factors: if changing a manufacturing process becomes very costly for customers, they may reduce their process control equipment budgets by lowering the sampling rate of inspection and metrology for certain technologies Sourced. Once yield settles, inspecting everything gives way to inspecting a sample. How far the yield of advanced packaging eventually stabilises is what sets the ceiling on this business.
11. The risks this company carries
| Risk | Substance | Supporting figures or wording |
|---|---|---|
| Export controls on China | Rules from the U.S. Commerce Department's Bureau of Industry and Security affect the company's ability to sell to and service Chinese customers. Entity lists, the foreign direct product rule and licensing requirements for advanced-node plants are all listed | FY2026 revenue from China was US$4,048.36m, 29.8% of the total. The company states that export controls affected part of its leading-edge business |
| Tariffs and trade restrictions | Tariffs, retaliatory trade measures, and uncertainty about the authority for tariffs, how they are implemented and how refunds work are all listed as risks | Set out in the summary risk list at the head of the Form 10-K |
| Customer concentration | TSMC alone has been above 10% of revenue for three years running. The ratio itself is not disclosed | Stated in the Form 10-K Not yet confirmed |
| Inspection being skipped | The company states that if process changes become costly, customers may cut process control budgets by lowering inspection sampling rates | Set out in the Form 10-K risk factors. A risk peculiar to a pure-play inspection company |
| AI making its own products obsolete | The company states that AI-driven design, verification and test, chiplets, advanced packaging and new materials could change inspection and metrology requirements and reduce the value of existing product lines and intellectual property | Set out in the Form 10-K risk factors. Notably, advanced packaging appears as a risk as well as an opportunity |
| Industry cyclicality | Revenue follows customers' capital expenditure plans, and it did fall in FY2024 | FY2023 US$10.496bn to FY2024 US$9.812bn, down 7% Our calculation |
It is striking that advanced packaging sits inside the same risk paragraph as obsolescence. The company's argument is that AI-driven design and new packaging schemes may change the requirements for inspection and metrology themselves. The same thing happens on the materials side. Move from solder bumps to hybrid bonding and whole steps disappear, flux and underfill among them. A technology shift in the back end brings expanding demand and the extinction of existing products at the same moment, for equipment makers and materials makers alike. That KLA writes this down as a risk factor is, if anything, honest disclosure.
12. Glossary
- Process control
- Inspecting and measuring what has been manufactured, finding defects and dimensional drift, and feeding that back into the process. It does not touch the wafer.
- Yield
- The proportion of material put in that comes out as good product. It is the single strongest driver of semiconductor profitability.
- WLP
- Wafer level packaging. Building the package while the wafer is still whole, before it is diced. Processing happens on the round wafer.
- PLP
- Panel level packaging. Building packages on a large rectangular substrate rather than a round wafer, so that more units come off each sheet.
- IC substrate
- The intermediate board that carries the chip and connects it to the printed circuit board. Build-up materials such as ABF film are used in it.
- Plasma dicing
- Separating a wafer with plasma instead of a rotating blade. It produces less chipping and suits very thin dies.
- Reticle
- The master pattern loaded into a lithography tool. A defect on it makes every wafer printed from it defective.
- Form 10-K
- The annual report a U.S.-listed company files with the Securities and Exchange Commission. It is audited and carries legal liability for its contents.
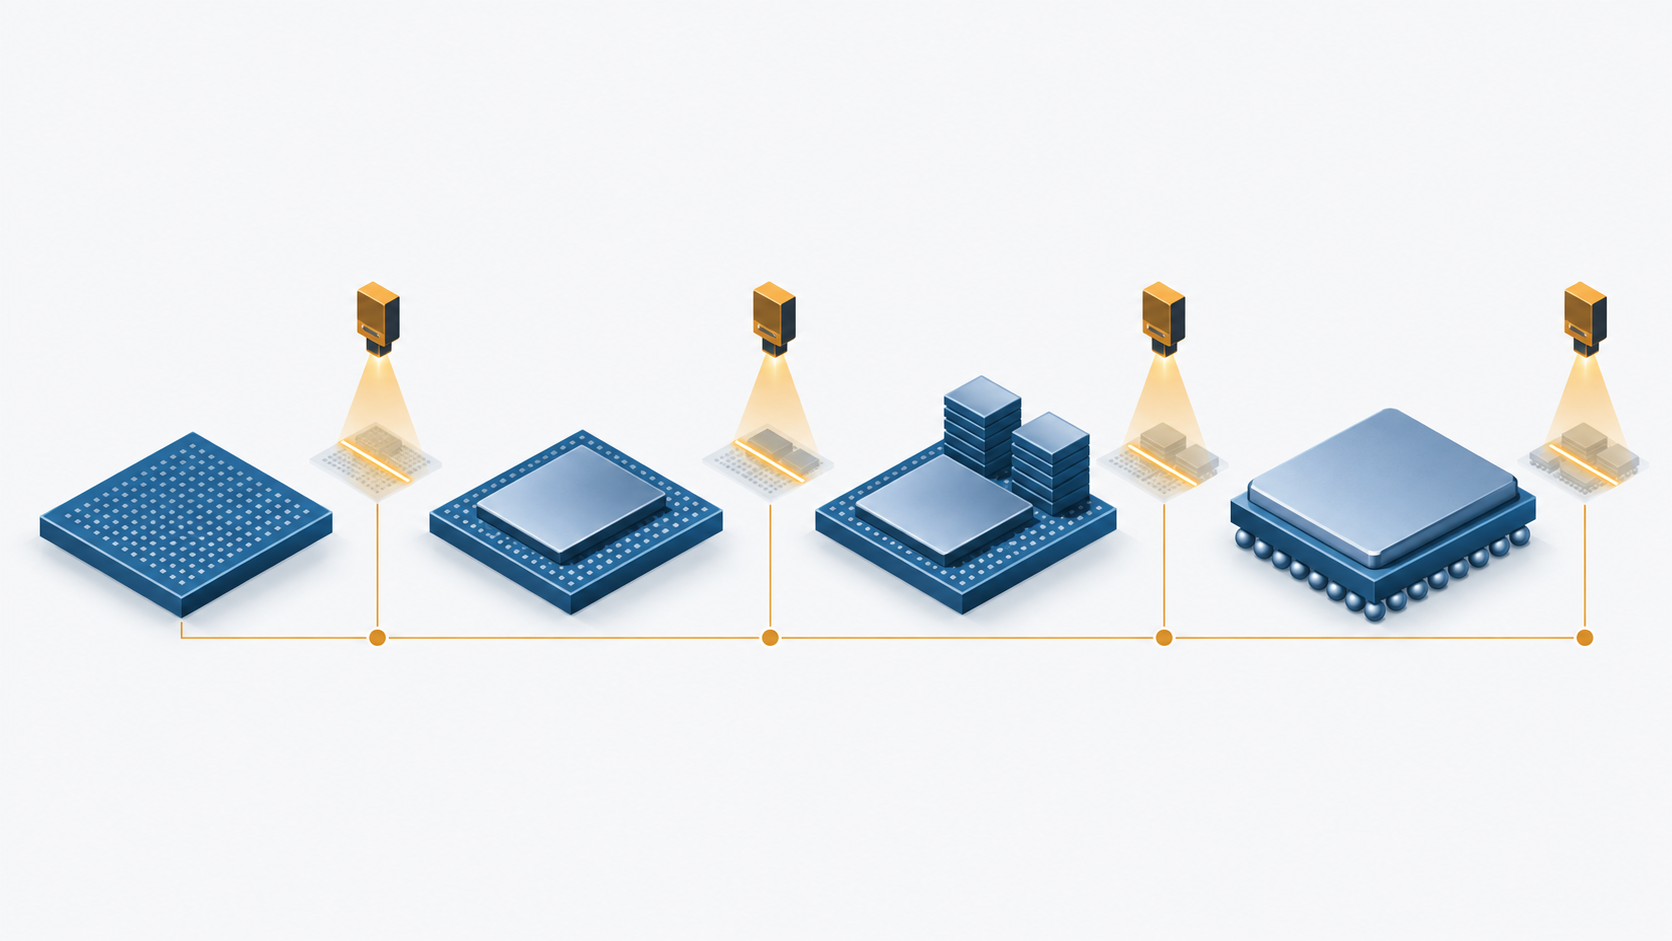 AI-generated concept
13. References
- KLA Corporation Form 10-K for the fiscal year ended June 30, 2026 (filed with the U.S. SEC on 6 August 2026). Revenue, net income, R&D expense and capital expenditure; revenue by segment, by product category and by region; headcount and its composition; customer concentration (TSMC); the product listing including Packaging Manufacturing; sites; the stock split; dividends; and risk factors. https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm
- KLA Corporation Fourth quarter and full year FY2026 earnings release (Form 8-K, Exhibit 99.1, 28 July 2026). Fourth-quarter revenue of US$3.658bn, full-year revenue of US$13.58bn, shareholder returns, first-quarter FY2027 guidance, the chief executive's comments and the ten-for-one stock split. https://www.sec.gov/Archives/edgar/data/319201/000031920126000024/exhibit991earningsrelease7.htm
- KLA Corporation Form 10-K for the fiscal year ended June 30, 2025 (filed with the U.S. SEC on 8 August 2025). Revenue, net income, R&D expense and capital expenditure for FY2025 and earlier years. https://www.sec.gov/Archives/edgar/data/319201/000031920125000024/klac-20250630.htm
- U.S. SEC EDGAR XBRL company facts API (CIK 0000319201). Revenue, net income, cost of revenue, R&D expense and capital expenditure for FY2022 to FY2026, as tagged in each year's Form 10-K. https://data.sec.gov/api/xbrl/companyfacts/CIK0000319201.json
14. Claim-to-source audit
| Claim in the article | Category | Source |
|---|---|---|
| Legal name, head office address, Delaware incorporation, NASDAQ listing (KLAC) | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| Formed in April 1997 by the merger of KLA Instruments and Tencor Instruments, which began operating in 1975 and 1976 | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| The fiscal year ends on 30 June; FY2026 ran 1 July 2025 to 30 June 2026 | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| Revenue, net income, cost of revenue, R&D expense and capex for FY2022 to FY2026 | Sourced | References 4 and 3 https://data.sec.gov/api/xbrl/companyfacts/CIK0000319201.json |
| Year-on-year percentages, 61.3% gross margin, 35.6% net margin, R&D at 11.3% and capex at 2.8% of revenue, and the segment shares | Our calculation | Derived from the figures in references 1 and 4 https://data.sec.gov/api/xbrl/companyfacts/CIK0000319201.json |
| Segment revenue and growth, revenue by product category and its shares, service at 23% of revenue | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| About 17,000 employees, the regional and functional splits, and the position on unions | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| Revenue by region (China 29.8%, Taiwan 26.8% and the rest) and the reasons given for Taiwan up 13.7% and Korea up 26.2% | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| TSMC as the only customer above 10% of revenue for three years running | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| The "Packaging Manufacturing" product listing (Kronos, CIRCL-AP, QualiSurf and the rest) | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| How the SPTS products (plasma dicing included), the Orbotech products and the ICOS products are positioned | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| Countries of manufacture and R&D, and the statement that facilities are not allocated to segments | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| The three statements about growth in the advanced packaging business | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| The ten-for-one stock split of 11 June 2026 and the quarterly dividend of US$0.230 | Sourced | References 1 and 2 https://www.sec.gov/Archives/edgar/data/319201/000031920126000024/exhibit991earningsrelease7.htm |
| Fourth-quarter revenue of US$3.658bn, shareholder returns of US$3.35bn, first-quarter FY2027 guidance and the chief executive's comments | Sourced | Reference 2 https://www.sec.gov/Archives/edgar/data/319201/000031920126000024/exhibit991earningsrelease7.htm |
| The risk factors (BIS rules, tariffs, lower inspection sampling rates, obsolescence through AI, cyclicality) | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/319201/000031920126000027/klac-20260630.htm |
| Revenue from back-end work (advanced packaging) | Not yet confirmed | Not disclosed. Only qualitative statements exist, so this article states no figure |
| Share of the process control market or of back-end inspection | Not yet confirmed | No primary source exists, so this article states no figure |
| The exact share of revenue TSMC represents, and the names of other customers | Not yet confirmed | The company says only "more than 10%", and this article does not guess |
| When the name changed from KLA-Tencor to KLA Corporation | Not yet confirmed | Absent from the FY2026 Form 10-K; this article could not confirm it |
| Plans for new plants and the scale of any capacity expansion | Not yet confirmed | Only "planned expansions" is published, with no scale or timing, so this article states no figure |
| Trading relationships with OSATs, substrate makers and materials suppliers | Not yet confirmed | Absent from KLA's own primary material, so this article does not treat them as partnerships |
| The outlook in section 10 | Not yet confirmed | An interpretation by this article, drawn from the six items in the facts table |
Last updated 21 September 2026 / Troy Technical
Every figure in this article comes from KLA Corporation's statutory filings with the U.S. Securities and Exchange Commission or from the company's own announcements. No research-firm estimates or press-based figures have been used.