COMPANY PROFILE / SEMICONDUCTOR BACK-END
Ibiden
From a Gifu power company to one of the world's leading makers of the base an AI chip sits on
Ibiden makes IC package substrates, the small multilayer boards that carry a semiconductor die and connect it to the circuit outside. In FY2025 it reached the point where a single customer, NVIDIA, accounted for 29.4% of revenue. Ibiden buys dielectric films such as Ajinomoto's ABF and builds them into substrates; it is not an OSAT, which mounts and encapsulates the die. This profile places the company using only figures from its statutory filings and its own investor material.
- Ibiden in 30 seconds
- The logo and how the name is written
- What the company actually does: the package substrate
- Scale: five years of revenue
- Company category and position in the back-end industry
- Sites and the countries where it manufactures
- Leading products and share in semiconductor back-end work
- Current investment plans
- Major corporate partners, meaning the customers it discloses
- Where the company is heading in this field
- The risks this company carries
- Glossary, references and claim-to-source audit
1. Ibiden in 30 seconds
Nagoya Stock Exchange Premier MarketCode 4062. 281,721,114 shares issued as of 31 March 2026
(416,201 JPY m)Operating profit JPY 62.0bn. The year ends 31 March
(IC package substrates)It makes no materials and assembles no chips. It builds the substrate itself
Of Ibiden's FY2025 revenue, NVIDIA accounted for JPY 122,470m, or 29.4%, and Intel for JPY 75,319m, or 18.1%. Those two alone are 47.5% of revenue Our calculation. And these are not estimates: the customer names and the amounts appear in the Annual Securities Report Sourced. In a supply chain where most companies say nothing about who they sell to, Ibiden names its customers because Japanese disclosure rules require it for any counterparty above 10% of total sales. It is one of the few companies where you can follow "who actually builds the substrate under an AI chip" in primary material.
2. The logo and how the name is written
The Ibiden logo is a registered trademark of the company.
A note on the name: in English the company writes itself IBIDEN CO.,LTD. The word is a contraction of Ibigawa Denki, the Ibi River electricity business it was founded as in 1912 under the name Ibigawa Electric Power. The contracted form became the official corporate name in 1982.
Official site: https://www.ibiden.co.jp/3. What the company actually does: the package substrate
Ibiden reports three segments. Measured by external revenue in FY2025, they break down as follows Sourced.
| Segment | Main products | Revenue (JPY m) | Share | Operating profit (JPY m) |
|---|---|---|---|---|
| Electronics | IC package substrates | 243,316 | 58.5% | 45,248 |
| Ceramics | Diesel particulate filters (DPF), catalyst support mats (AFP), specialty carbon products (FGM), safety components for EV batteries | 82,554 | 19.8% | 7,646 |
| Other | Construction and building materials, plastics processing, food processing, information services, transport, power generation | 90,330 | 21.7% | 8,964 |
| Total | - | 416,201 | 100% | 62,027 |
Total operating profit includes JPY 168m of adjustments. The share column is as the company presents it in its supplementary material.
Semiconductors sit in the first of these, the Electronics segment, and it makes exactly one thing: IC package substrates. The segment description in the filing is a single line, that Electronics manufactures and sells package substrates. No materials, no equipment Sourced.
What a package substrate is
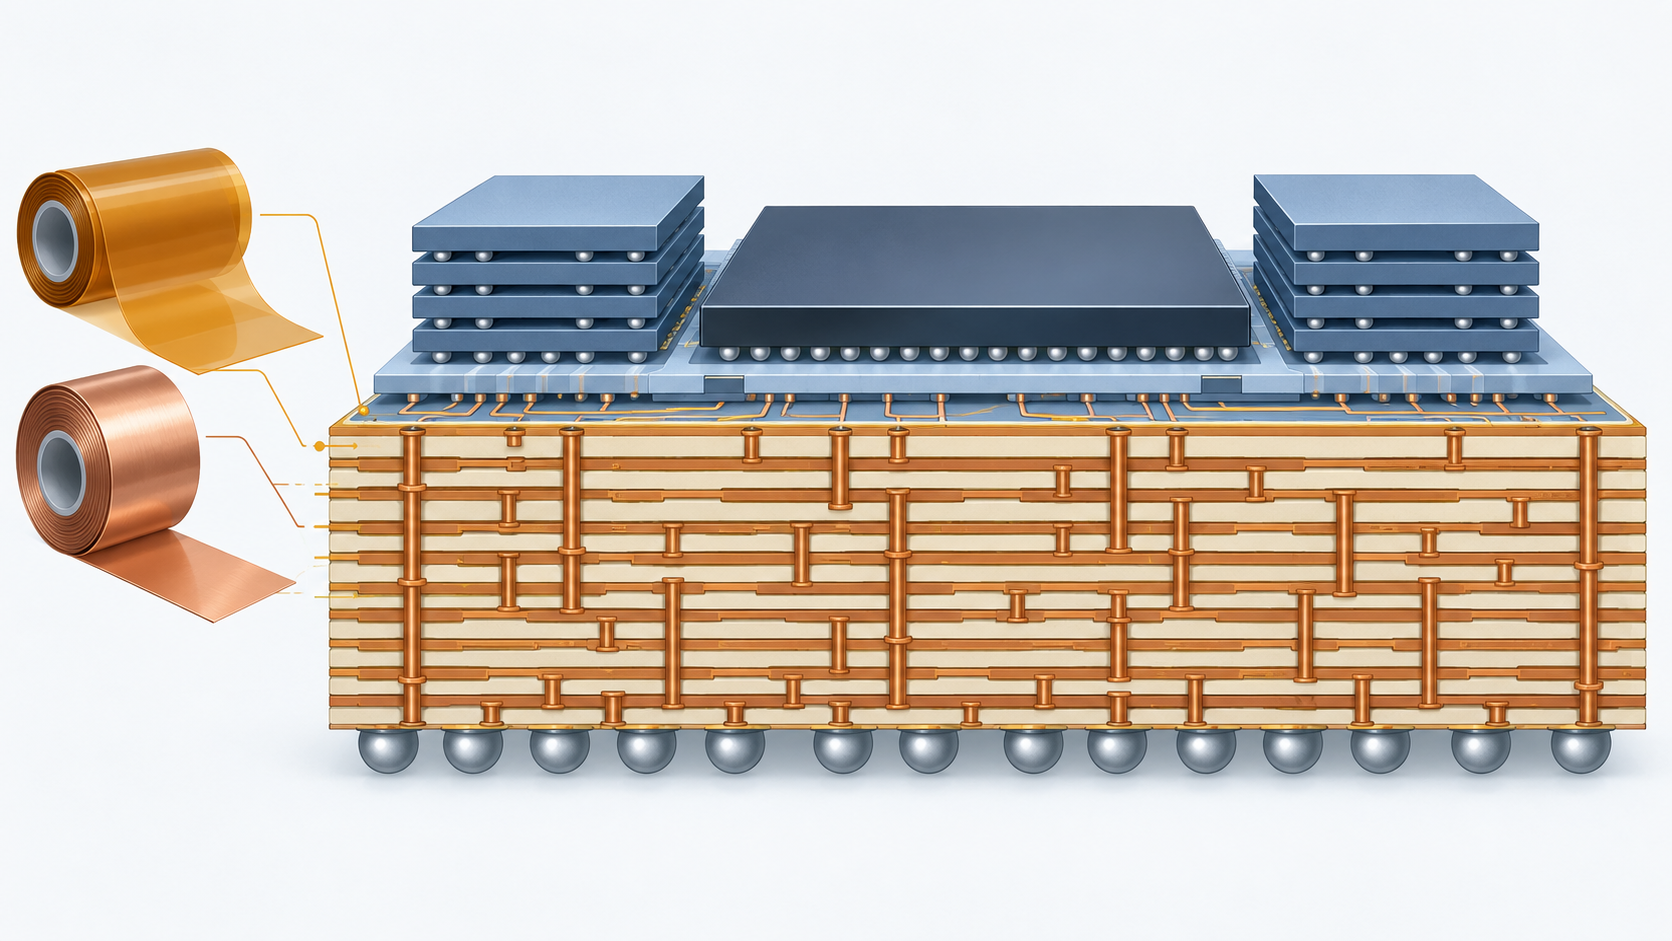
A semiconductor die cannot be soldered straight onto a board. Something has to take electrodes finer than a human hair and fan them out to terminals a machine can handle. That intermediary is the package substrate. It is built by stacking insulating resin layers and copper wiring layers one at a time, the build-up process. Ibiden has kept pace with large AI dies by increasing both the number of those layers and the area of the board.
How far that is going is set out generation by generation in the company's results briefing material Sourced.
| Item | CY2025 | CY2026 | CY2028 | CY2030 onward |
|---|---|---|---|---|
| Die size (in reticles) | 3.5 | 5.0 | 7.5 | over 9 |
| Substrate size (mm) | 80 x 80 | 90 x 90 | 110 x 110 | over 130 x 130 |
| SAP layer count | 9-X-9 | 10-X-10 | 12-X-12 | 14-X-14 |
SAP is the semi-additive process. "9-X-9" means nine layers built up on each side of the core. In the same material the company names glass cores (to control warpage), silicon bridge designs and optical conversion as development items.
Read that table from the materials side. Over five years the area grows about 2.6 times, from 80 x 80 to 130 x 130, and the layer count on each side goes from nine to fourteen. Process steps scale roughly with layer count, and yield falls as a power of the number of steps. So going larger and going to more layers both cut hard into how many good boards a given line can produce. The company expresses this as a production load index: the load per AI server substrate, on an SAP basis, is projected to be 1.8 times the 2024 level in 2026 and 2.5 times in 2028 Sourced. Multiply the line by 1.8 and the number of boards coming out does not go up. When people say substrates are short for AI silicon, this load multiple is usually what they are describing.
4. Scale: five years of revenue
| Fiscal year | Revenue (JPY m) | Ordinary profit (JPY m) | Profit attributable to owners (JPY m) | Employees (consolidated) |
|---|---|---|---|---|
| FY2021 (169th, Mar 2022) | 401,138 | 74,394 | 41,232 | 12,958 |
| FY2022 (170th, Mar 2023) | 417,549 | 76,176 | 52,187 | 12,744 |
| FY2023 (171st, Mar 2024) | 370,511 | 51,140 | 31,490 | 11,375 |
| FY2024 (172nd, Mar 2025) | 369,436 | 47,890 | 33,704 | 11,168 |
| FY2025 (173rd, Mar 2026) | 416,201 | 60,822 | 63,713 | 11,105 |
Headcount excludes temporary staff, of whom there were 2,104 on average in FY2025. Over the five years revenue rose just 3.8% while headcount fell by 1,853 Our calculation.
What stands out in that table is that revenue has barely grown in five years. The peak is still FY2022 at JPY 417.5bn, and FY2025 at JPY 416.2bn has not passed it. The composition, though, has changed completely. Electronics segment revenue went from JPY 197.2bn in FY2024 to JPY 243.3bn in FY2025, up 23.4%, and its operating profit from JPY 26.8bn to JPY 45.2bn, up 68.5% Sourced. What shrank was automotive exhaust ceramics and PC-related work.
The company's guidance for FY2026 is revenue of JPY 550bn and operating profit of JPY 127bn, after the upward revision of 4 August 2026. Electronics is planned at JPY 375bn of revenue and JPY 110bn of operating profit, which would make it 87% of group operating profit Not yet confirmed.
5. Company category and position in the back-end industry
The category is manufacturer, specifically a component maker. This is the point most often misunderstood, so here is the chain in process order.
| Position in the supply chain | What it does | Representative companies |
|---|---|---|
| Materials makers | Supply interlayer dielectrics, copper foil, encapsulants, adhesives and similar | Ajinomoto, Sumitomo Bakelite, Mitsui Kinzoku and others |
| Package substrate makers (Ibiden is here) | Buy those materials and build the substrate itself by stacking insulating layers and copper wiring | Ibiden, Unimicron, Kinsus, Shinko Electric Industries and others |
| OSATs and foundries | Mount the die on the finished substrate, encapsulate it and test it | ASE Group, Amkor, TSMC and others |
| Chip design houses | Design the chip and contract out everything above | NVIDIA, AMD, Intel and others |
In one line: a substrate maker builds the base, an OSAT puts the chip on the base. What an OSAT takes on is the assembly steps: cutting the wafer (dicing), joining the die to the substrate (bonding), covering it in resin (moulding) and checking it electrically (test). The substrate used in that work is not made by the OSAT; it is bought from a substrate maker like Ibiden. So the two are not competitors: the substrate maker sits upstream of the OSAT. Because all of these steps are collectively called the back end they get run together, but the equipment and the way yield behaves are entirely different.
6. Sites and the countries where it manufactures
IC package substrates are made in three countries: Japan, the Philippines and Malaysia Sourced. Everything leading edge is in Gifu Prefecture in Japan.
| Site | Country | Segment | Employees | Book value (JPY m) |
|---|---|---|---|---|
| Ono plant | Japan (Ono, Gifu) | Electronics | 533 | 130,783 |
| Kawama plant | Japan (Ogaki, Gifu) | Electronics | 26 | 36,933 |
| Ogaki Central plant | Japan (Ogaki, Gifu) | Electronics | 1,015 | 27,939 |
| Ogaki plant | Japan (Ogaki, Gifu) | Electronics | 1,003 | 25,469 |
| Aoyagi plant | Japan (Ogaki, Gifu) | Electronics and Ceramics | 647 | 1,865 |
| Ibiden Philippines | Philippines (Batangas) | Electronics | 1,638 | 11,733 |
| Ibiden Electronics Malaysia | Malaysia (Penang) | Electronics | 934 | 24,991 |
| Ceramics sites (3 in Japan, 3 abroad) | Japan, Hungary, Korea, Mexico | Ceramics | 3,074 | 36,158 |
As of 31 March 2026. Book values exclude construction in progress of JPY 111,793m. The ceramics row is our own aggregation of the Ogaki Kita, Kinuura and Godo plants in Japan together with the plants in Hungary, Pohang in Korea, and Mexico Our calculation.
There are subsidiaries in Taiwan, Korea, China, Singapore, the United States and the Netherlands as well, but within Electronics every one of them is a sales company; none manufactures substrates Sourced.
The generations of plants are laid out in the results briefing material. They run from the Ogaki plant (Cell 2 and 3) that started in 1998, through the Central plant (Cell 4 and 5) in 2007 and 2020, to the Ono plant (Cell 8), which started operating in the second quarter of FY2025, with the Kawama plant (Cell 6) next in line Sourced. The company history in the Annual Securities Report records the opening of the Ono plant in October 2025.
In the table above, the Ono plant, opened only in 2025, carries a book value of JPY 130.8bn, 2.4 times the combined JPY 53.4bn of the established Ogaki and Ogaki Central plants Our calculation. And there is a further JPY 111,793m of construction in progress that the table does not include: plant still being built, not yet working as an asset. Seen from a supplier's side, that means a cluster of new lines coming up in Gifu over the next two to three years, and when they do, the specification demanded of dielectrics, copper foil and process chemicals will be set by the generation of the new line, not by the existing one. Having supplied the current line and being designed into the next one are two different things.
7. Leading products and share in semiconductor back-end work
In effect there is one product
The Electronics segment makes IC package substrates and nothing else. By application the company describes four categories Sourced.
- AI servers
- Substrates for GPUs and AI ASICs. Large and heavily layered, and the fastest growing area at present. This is what the Ono plant (Cell 8) is for.
- General-purpose servers
- For ordinary data centre server CPUs. The company describes FY2025 as a gradual recovery.
- Switch ICs
- Substrates for the switch chips that link servers and data centres. Volume production support began in FY2025.
- PCs
- The traditional mainstay. FY2025 came in below plan. Handled by the plant in the Philippines.
On market share, stated plainly
Ibiden publishes no numerical market share for IC package substrates. What the results briefing material contains is a statement of intent, that the company will "maintain the top share in the high-end market" through capacity expansion centred on leading-edge applications. There is no percentage Sourced. Claims of the form "the world share of package substrates is X per cent" are research-firm estimates, and this article does not use them Not yet confirmed. The market size charts in the company's own briefing material carry a note saying they are estimated from outside research sources, so those market figures are not used here either.
There are, however, two pieces of primary material that stand in for a share figure. One is the disclosed revenue by customer (section 9). The other is what management said about how share behaves at a generation change Sourced.
At the results briefing of 12 May 2026, asked about competition in interposer-style products, the company said: "with each generation change, we take close to 100% share at the moment a new generation ramps, and we expect to lose something like 20 to 30 points of share after three to six months". On silicon bridge designs it added that "connecting the back side of a silicon bridge is considerably difficult, and we believe we can hold a technical advantage at least until 2030".
None of this is a disclosed share number, but it is the industry structure described in the words of a participant: the leading-edge generation ramps close to a monopoly, and competitors arrive once volume production settles.
8. Current investment plans
In its release of 3 February 2026 the company states plainly that it "approved an investment plan of about JPY 500bn in total for the electronics business over the three years from FY2026 to FY2028", for the purpose of "expanding production capacity for high-performance IC package substrates for AI servers and high-performance servers" Sourced. That JPY 500bn was made concrete in two steps: 3 February for Kawama, about JPY 220bn, and 26 February for Ono, about JPY 280bn.
The plan for new facilities in the Annual Securities Report covers a wider set of projects Sourced.
| Company and site | Segment | Planned amount (JPY m) | Already paid (JPY m) | Start / completion |
|---|---|---|---|---|
| Ibiden, Ono plant | Electronics | 192,800 | - | March 2026 / June 2029 |
| Ibiden, Kawama plant | Electronics | 179,500 | 56,087 | March 2022 / June 2029 |
| Ibiden Electronics Malaysia | Electronics | 122,700 | - | February 2026 / June 2029 |
| Ibiden, Ogaki plant (started 2026) | Electronics | 36,100 | 0 | February 2026 / June 2029 |
| Ibiden, Ogaki Central plant | Electronics | 32,600 | 1,202 | February 2026 / June 2029 |
| Ibiden, Ogaki plant (started 2023) | Electronics | 12,900 | 4,196 | March 2023 / April 2026 |
| Total | - | 576,600 | 61,485 | - |
As of 31 March 2026. The total is our own addition Our calculation. The company says the added capacity on completion is "omitted because it is difficult to estimate", so how far this investment multiplies capacity is not published Not yet confirmed. The JPY 122.7bn of electronics investment planned for the Malaysian plant is worth noting as a move that runs against the concentration of leading-edge work in Gifu.
Asked at the results briefing how a company with JPY 416.2bn of revenue funds JPY 500bn of investment over three years, Ibiden replied: "in principle we conclude contracts with customers under which they bear an amount equivalent to the investment, part of it received in advance. We are not contemplating additional financing at this point" Sourced. The claim, in other words, is that this expansion is not a bet on a demand forecast but investment underwritten by customer contracts. The counterparties, the amounts and the terms are all undisclosed Not yet confirmed.
9. Major corporate partners, meaning the customers it discloses
Ibiden discloses no capital alliances or joint ventures. What it has instead is unusual for a back-end company: Japanese disclosure rules put its customers' actual names and the revenue from each into the filing, because any counterparty above 10% of total sales has to be identified Sourced.
| Customer | FY2024 (JPY m) | Share | FY2025 (JPY m) | Share |
|---|---|---|---|---|
| NVIDIA Corp. | 75,077 | 20.3% | 122,470 | 29.4% |
| Intel Corp. | 76,709 | 20.8% | 75,319 | 18.1% |
| Advanced Micro Devices Inc. | 40,707 | 11.0% | - | Omitted, below 10% |
All of this is the Electronics segment. The company discloses these three as principal customers and nothing more; contract terms, durations and pricing are not published.
The same shift shows up by customer location. FY2025 revenue into Taiwan was JPY 111,491m, up 90.6% from JPY 58,494m the year before Our calculation, lifting Taiwan from 15.8% to 26.8% of total revenue. That is the concentration of AI chip assembly in Taiwan, seen from the supplier's side of the ledger.
Ibiden buys interlayer dielectric from outside and builds substrates with it. The industry says that dielectric is Ajinomoto's ABF, but neither Ajinomoto nor ABF appears anywhere in Ibiden's Annual Securities Report, its results briefing material or its timely disclosures. As far as the company goes on the record is a risk statement that "for some key raw materials, components and energy we depend on a limited number of suppliers" Sourced. This article therefore does not treat any individual materials maker as a trading relationship Not yet confirmed.
10. Where the company is heading in this field
Anything said here is a forecast, so the facts behind the judgement and the outlook drawn from them are kept apart.
What is established
| Fact | What it implies for the back end |
|---|---|
| Electronics revenue up 23.4% to JPY 243.3bn, operating profit up 68.5% to JPY 45.2bn | AI substrates are showing up in the actual numbers. One segment generates more than 70% of group profit |
| NVIDIA at 29.4% of revenue and Intel at 18.1%, disclosed by name | Documentary proof that it really does supply the substrates of the main AI players |
| About JPY 500bn approved for the electronics business across FY2026 to FY2028 | An expansion larger than a year of revenue. It assumes demand continues |
| The expansion is described as one where "customers bear an amount equivalent to the investment" | Part of the investment risk sits with the customer. Read the other way, the company is tightly bound to customer plans |
| Production load per AI server substrate at 2.5 times the 2024 level by 2028 | Adding capacity does not add units in proportion |
| FY2026 guidance of JPY 550bn revenue and JPY 127bn operating profit, after the upward revision | The company itself expects to set records |
Outlook
Not yet confirmed Read plainly, those facts point to Ibiden's presence in the back end strengthening for now. The reason is that only a handful of companies worldwide can build large, heavily layered AI substrates in volume, and Ibiden leads the Japanese side of that handful. The company's own medium-term target is to double revenue by FY2030 against FY2024, built from growth of +250% in AI servers and +150% in general-purpose servers and ASICs Sourced.
Not yet confirmed There are two ways that picture breaks. One is a design change on the customer side. With 47.5% of revenue in two accounts, if those two choose a different mounting approach for the next generation, a glass core or a connection that bypasses the substrate, the effect lands directly. The other is competitors catching up: as the company itself says, 20 to 30 points of share go within three to six months of a new generation ramping, so the first-mover advantage resets every generation. The FY2030 doubling target assumes clearing both of those, repeatedly.
11. The risks this company carries
What follows is drawn from the risk factors Ibiden sets out in its Annual Securities Report, narrowed to those that matter in a back-end context Sourced.
| Risk | Substance | Supporting figures |
|---|---|---|
| Customer concentration | Under "technological change and transition" the company notes that innovation and shifting product needs in the server and PC markets could change substantially. Having two customers at nearly half of revenue amplifies that | NVIDIA 29.4% plus Intel 18.1% equals 47.5% Our calculation |
| Recovering the capital spend | The company states outright that "if we cannot secure the order volumes originally expected, this could materially affect our results and financial position". FY2026 capex is planned at JPY 210bn, which is 38.2% of planned revenue | Capex divided by planned revenue equals 38.2% Our calculation |
| Impairment | The company names impairment accounting as a risk, and it recorded an impairment loss of JPY 18,587m in the Electronics segment in FY2024 | Impairment loss by segment in the Annual Securities Report |
| Concentrated supply of raw materials | The company states that "for some key raw materials, components and energy we depend on a limited number of suppliers". A delay or stoppage feeds straight into production | Item (4) of "business and other risks" |
| Concentration of production | The leading-edge plants are all in Gifu Prefecture. The company lists major natural disasters and geopolitical risk as separate items | Electronics has five domestic sites, all in Gifu |
| Currency | A high share of revenue is earned abroad, so translation into yen matters. FY2025 assumed JPY 149 to the U.S. dollar; the FY2026 full-year forecast assumes JPY 158 | The rates in the supplementary material to the results release |
Follow Ibiden's results by group revenue and the swings in ceramics and the other businesses will hide the plot. What to watch each quarter is two numbers: Electronics segment revenue and its operating margin. That margin was 18.6% in FY2025, 27.6% in the first quarter of FY2026, and 29.3% in the full-year plan, and it tracks the product mix, meaning how much AI work there is, almost directly Sourced. For a supplier of materials, a rising margin means a rising proportion of difficult products, and that is exactly where the properties demanded of the material change too: lower transmission loss, lower thermal expansion, handling of thinner films. The order backlog is in the filing as well, at JPY 39,070m at the end of March 2026, up 27.8% year on year.
12. Glossary
- IC package substrate
- The small multilayer board that carries a semiconductor die and connects it to the circuit board outside. Its job is to fan the fine electrodes on the die out to terminals large enough to mount.
- Build-up process
- Making a multilayer board by adding insulating and copper wiring layers one at a time. More layers means more process steps, and yield falls accordingly.
- SAP
- Semi-Additive Process. Plating up only the wiring that is needed on top of a thin seed layer. Suited to fine-pitch wiring.
- Reticle
- The maximum area a lithography tool can expose in one shot. "A die size of 3.5 reticles" means a chip of 3.5 times that area.
- Interposer
- An intermediate substrate that carries several dies and wires them to each other. It sits on top of the package substrate.
- Silicon bridge
- Embedding a small piece of silicon only where die-to-die connection is needed, and routing through it. Cheaper than covering the whole area with an interposer, but the connection on the back side is difficult.
- Glass core
- Using glass rather than resin as the core of the substrate, to control the warpage that comes with larger boards. Ibiden names it as a development item.
- OSAT
- Outsourced Semiconductor Assembly and Test. A company that takes on mounting the die on a substrate, encapsulating it and testing it. It sits downstream of the substrate maker.
 AI-generated concept
13. References
- IBIDEN CO.,LTD. Annual Securities Report for the 173rd fiscal year, 1 April 2025 to 31 March 2026 (filed with the Director-General of the Kanto Local Finance Bureau on 18 June 2026). Five years of revenue, ordinary profit, net profit and headcount; company history; subsidiaries; revenue and operating profit by segment; sales to principal customers; information by region; principal facilities; the plan for new facilities; R&D expense; employee data; business and other risks; and production, orders and sales.contents.xj-storage.jp/.../S100YC4B.pdf
- IBIDEN CO.,LTD. Supplementary material to the FY2025 results release (11 May 2026). Consolidated results and segment information, shares and margins, capital expenditure, depreciation, exchange rates and the number of consolidated subsidiaries.contents.xj-storage.jp/.../140120260505517291.pdf
- IBIDEN CO.,LTD. FY2025 consolidated results release under Japanese GAAP (11 May 2026).contents.xj-storage.jp/.../140120260505517290.pdf
- IBIDEN CO.,LTD. Notice regarding capital investment (acquisition of fixed assets) for high-performance IC package substrates (3 February 2026). The three-year plan of about JPY 500bn for FY2026 to FY2028, and the Kawama plant (Cell 6) at about JPY 220bn.contents.xj-storage.jp/.../140120260202544768.pdf
- IBIDEN CO.,LTD. Notice regarding capital investment (acquisition of fixed assets) for high-performance IC package substrates, progress disclosure (26 February 2026). The Ono plant (Cell 8) at about JPY 280bn.contents.xj-storage.jp/.../140120260220566591.pdf
- IBIDEN CO.,LTD. FY2025 full-year results briefing material (12 May 2026). The IC package substrate roadmap (die size, substrate size, SAP layer count), the production load multiple, the breakdown of the JPY 500bn investment and what each site will build, capital expenditure by year, and the shareholder return policy.ibiden.co.jp/ir/items/kessannsetsumeiFY2025.pdf
- IBIDEN CO.,LTD. FY2024 results briefing material (9 May 2025). The plant network (cell numbers, year of start-up, what each builds), the medium-term outlook for FY2030 and the growth rates against FY2024.ibiden.co.jp/ir/items/kessannsetsumeiFY2024.pdf
- IBIDEN CO.,LTD. Principal questions and answers at the FY2025 full-year results briefing (12 May 2026). Funding of the JPY 500bn investment, how share behaves at a generation change, the advantage in silicon bridge designs, and substrates for switch ICs.ibiden.co.jp/ir/items/QA_FY25Q4.pdf
- IBIDEN CO.,LTD. Supplementary material to the first quarter FY2026 results release (4 August 2026). First quarter results and the upward revision to full-year guidance (revenue JPY 550bn, operating profit JPY 127bn), and the Electronics segment margin.contents.xj-storage.jp/.../140120260803507041.pdf
- IBIDEN CO.,LTD. Official website, used to check the corporate profile and the brand mark.https://www.ibiden.co.jp/
14. Claim-to-source audit
| Claim in the article | Category | Source |
|---|---|---|
| Legal name, head office, year established (November 1912), the renaming (November 1982), listing venues, shares issued | Sourced | Reference 1contents.xj-storage.jp/.../S100YC4B.pdf |
| FY2025 revenue of 416,201 JPY m, operating profit of 62,027 JPY m, ordinary profit of 60,822 JPY m | Sourced | Reference 2contents.xj-storage.jp/.../140120260505517291.pdf |
| Five years of revenue, ordinary profit, net profit and consolidated headcount | Sourced | Reference 1, the five-year summary of key financial datacontents.xj-storage.jp/.../S100YC4B.pdf |
| Revenue up 3.8% over five years, headcount down by 1,853 | Our calculation | Derived from the five years of figures in reference 1contents.xj-storage.jp/.../S100YC4B.pdf |
| Revenue and operating profit by segment (Electronics 243,316 and 45,248, Ceramics 82,554 and 7,646, Other 90,330 and 8,964 JPY m) and the 58.5% share | Sourced | References 2 and 1contents.xj-storage.jp/.../140120260505517291.pdf |
| Electronics accounting for 73.0% of operating profit | Our calculation | 45,248 divided by 62,027, from reference 2contents.xj-storage.jp/.../140120260505517291.pdf |
| Electronics revenue up 23.4% and operating profit up 68.5%; order backlog of 39,070 JPY m, up 27.8% | Sourced | Reference 1contents.xj-storage.jp/.../S100YC4B.pdf |
| Revenue by customer (NVIDIA 122,470 JPY m and 29.4%, Intel 75,319 JPY m and 18.1%, AMD omitted below 10%) | Sourced | Reference 1, sales to principal customerscontents.xj-storage.jp/.../S100YC4B.pdf |
| The top two at 47.5%, the 63.1% increase in value of NVIDIA sales, and the Other shares | Our calculation | Derived from the amounts disclosed in reference 1contents.xj-storage.jp/.../S100YC4B.pdf |
| Revenue into Taiwan of 111,491 JPY m against 58,494 JPY m, up 90.6%, and the 26.8% share | Our calculation | Shares derived from the amounts in the regional information of reference 1contents.xj-storage.jp/.../S100YC4B.pdf |
| The site list with headcount and book values, construction in progress of 111,793 JPY m, and the opening of the Ono plant in October 2025 | Sourced | Reference 1, principal facilities and company historycontents.xj-storage.jp/.../S100YC4B.pdf |
| The aggregate for the six ceramics sites, and the comparison that Ono is 2.4 times the two established plants | Our calculation | Our own addition of the book values in reference 1contents.xj-storage.jp/.../S100YC4B.pdf |
| Plant start-up years and cell numbers, what each builds, and the way server mix is framed | Sourced | Reference 7ibiden.co.jp/ir/items/kessannsetsumeiFY2024.pdf |
| The six items in the facilities plan (576,600 JPY m in total, 61,485 JPY m already paid) | Our calculation | Our own addition of the individual amounts in reference 1contents.xj-storage.jp/.../S100YC4B.pdf |
| The three-year approval of about JPY 500bn, Kawama at about JPY 220bn and Ono at about JPY 280bn, with phased start-up from FY2027 | Sourced | References 4 and 5contents.xj-storage.jp/.../140120260202544768.pdf |
| Kawama being for AI ASICs and Ono for AI GPUs | Sourced | Reference 6ibiden.co.jp/ir/items/kessannsetsumeiFY2025.pdf |
| The substrate roadmap (die size, substrate size, SAP layer count) and the production load at 2.5 times the 2024 level by 2028 | Sourced | Reference 6ibiden.co.jp/ir/items/kessannsetsumeiFY2025.pdf |
| "Customers bear an amount equivalent to the investment" and "close to 100% share at ramp, 20 to 30 points lost within three to six months" | Sourced | Reference 8ibiden.co.jp/ir/items/QA_FY25Q4.pdf |
| FY2026 full-year guidance (revenue JPY 550bn, operating profit JPY 127bn, Electronics JPY 375bn and JPY 110bn, capex JPY 210bn) | Not yet confirmed | Reference 9. Company guidance, not actual resultscontents.xj-storage.jp/.../140120260803507041.pdf |
| Capex at 38.2% of planned revenue, and Electronics at 87% of planned operating profit | Our calculation | Derived from the planned figures in reference 9contents.xj-storage.jp/.../140120260803507041.pdf |
| Doubling revenue by FY2030 against FY2024, with AI servers +250% and general-purpose servers and ASICs +150% | Not yet confirmed | Reference 7. A medium-term target, not actual resultsibiden.co.jp/ir/items/kessannsetsumeiFY2024.pdf |
| The risk factors (technological change, concentrated supply of raw materials, geopolitics, natural disaster, currency, capital investment, impairment) | Sourced | Reference 1, business and other riskscontents.xj-storage.jp/.../S100YC4B.pdf |
| A percentage market share for IC package substrates | Not yet confirmed | The company publishes no figure, only the stated aim of maintaining the top share in the high-end market. This article does not use research-firm estimates |
| How far the JPY 500bn investment multiplies production capacity | Not yet confirmed | Omitted by the company as difficult to estimate, and so undisclosed. This article offers no estimate |
| Trading relationships with individual materials makers such as Ajinomoto and its ABF | Not yet confirmed | No company or material name appears in Ibiden's own primary material, so this article does not treat any as a supplier relationship |
| The counterparties, amounts and terms of the contracts behind the expansion | Not yet confirmed | Undisclosed. The company says only that it concludes contracts with customers, and this article offers no estimate |
| The outlook in section 10 | Not yet confirmed | An interpretation by this article, drawn from the six items in the facts table |
Last updated 21 September 2026 / Troy Technical
Every figure in this article comes from statutory filings submitted by IBIDEN CO.,LTD. or from the company's own investor material. No research-firm estimates or press-based figures have been used.