COMPANY PROFILE / SEMICONDUCTOR BACK-END
Micron Technology
The company that makes HBM, the part that goes inside the CoWoS package
Micron designs DRAM and NAND and builds them in its own fabs. It is the only pure-play memory maker headquartered in the United States. It appears so often in back-end coverage because it is one of the few suppliers of HBM, the high bandwidth memory that goes into every AI package. Micron is not the company assembling the package; it is the company whose part goes inside it. This profile sets out that distinction using only the figures in the company's filings with the U.S. SEC.
- Micron in 30 seconds
- The logo and how the name is written
- What the company actually does: the IDM model
- Scale: five years of revenue
- Company category and position in the back-end industry
- Sites and the countries where it manufactures
- Leading products and share in semiconductor back-end work
- Current investment plans
- Major corporate partners
- Where the company is heading in this field
- The risks this company carries
- Glossary, references and claim-to-source audit
1. Micron in 30 seconds
Global Select Market, MUCommon stock with a par value of US$0.10 per share
(IDM, vertically integrated)Design, front end and back end are all held in house
Micron is not a back-end contractor. It does not assemble anyone else's chips; it stacks its own DRAM into a product called HBM and sells that to its customers. In other words, this is the company that makes the part that goes inside a package such as CoWoS. When Micron's name comes up in a back-end context, the question on the table is not who assembles the package but who can supply the HBM that goes into it, and reading it that way keeps the relationships straight.
2. The logo and how the name is written
The Micron logo and the names Micron and Crucial are registered trademarks of the company, as stated in the 10-K.
A note on naming: Micron Memory Japan is a separate legal entity, the successor to Elpida Memory, and the Hiroshima fab belongs to it. When a news report refers to "Micron Hiroshima", it is usually describing the Japanese entity rather than the U.S. parent, which is worth keeping in mind.
Official site: https://www.micron.com/about/our-company3. What the company actually does: the IDM model
Sorted by business model, Micron is an IDM, an integrated device manufacturer. It designs in house, builds in its own wafer fabs, finishes in its own assembly and test sites, and sells under its own brand. It does place work with foundries and OSATs, but only as a supplement Sourced.
| Product | What it is | FY2025 revenue |
|---|---|---|
| DRAM | Fast memory that loses its contents when power is cut. Includes HBM, DDR5, LPDDR and GDDR | US$28.58bn |
| NAND | Storage that keeps its contents without power, used in SSDs and smartphone storage | US$8.50bn |
| NOR and other | Small non-volatile memory holding boot code and similar | The remainder, about US$0.3bn |
The DRAM and NAND figures are stated in the body of the 10-K. NOR and other is the difference against total revenue of US$37,378m Our calculation.
In the fourth quarter of FY2025 the company reorganised itself into four business units defined by customer market Sourced. HBM sits inside CMBU.
- CMBU
- Cloud Memory Business Unit. Memory for the large cloud operators, and all HBM sold to data centre customers.
- CDBU
- Core Data Center Business Unit. Data centre memory for mid-sized clouds, enterprises and OEMs, plus data centre storage.
- MCBU
- Mobile and Client Business Unit. Smartphones and PCs.
- AEBU
- Automotive and Embedded Business Unit. Automotive, industrial and consumer equipment.
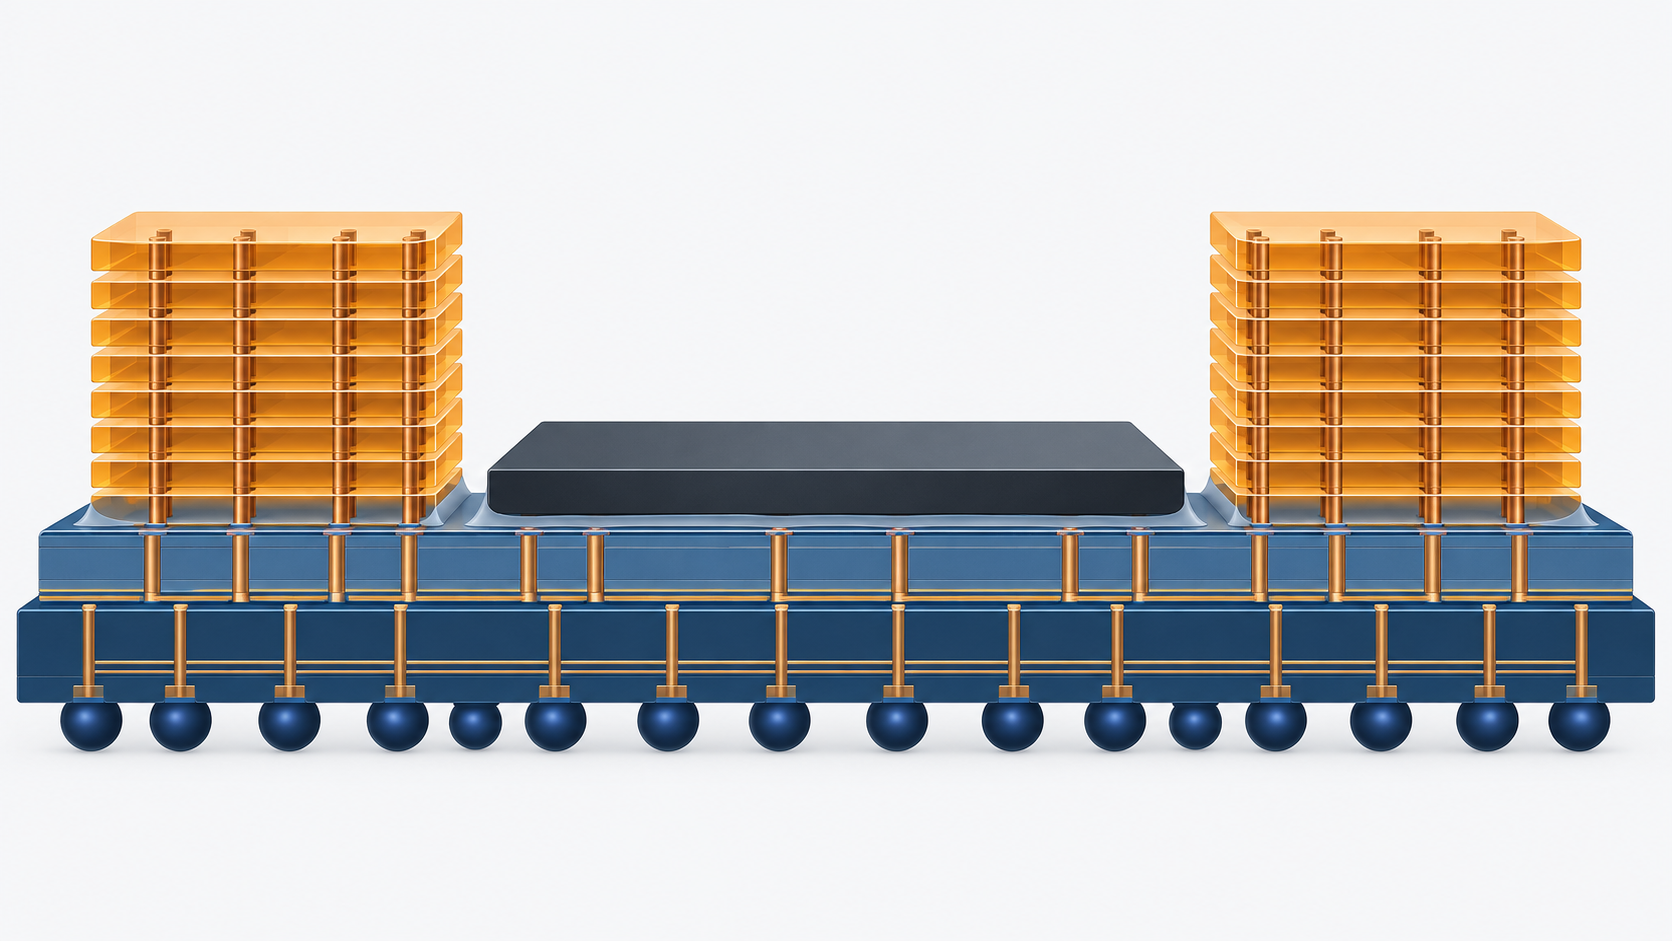
In the company's own words, HBM is a three-dimensional stacked DRAM architecture connected by TSVs, through-silicon vias Sourced. It is therefore not a single die but a small stacked package, several DRAM dies piled up and wired vertically, and Micron performs that assembly at its own back-end sites. From the materials side, what matters here is wafer thinning, TSV fill, the bonding between dies (microbump or hybrid bonding), the underfill that closes the gaps in the stack, and the warpage and heat of the stack as a whole. When people say "HBM yield" they are not only talking about front-end defect density; a great deal of it is the yield of this stacking process. The 10-K says as much, noting that system-level products such as HBM carry higher manufacturing cost per unit and longer cycle times than discrete components Sourced.
4. Scale: five years of revenue
| Fiscal year | Revenue (US$m) | Operating income (US$m) | Capital spending (US$m) | R&D expense (US$m) |
|---|---|---|---|---|
| FY2021 | 27,705 | 6,283 | 10,030 | 2,663 |
| FY2022 | 30,758 | 9,702 | 12,067 | 3,116 |
| FY2023 | 15,540 | minus 5,745 | 7,676 | 3,114 |
| FY2024 | 25,111 | 1,304 | 8,386 | 3,430 |
| FY2025 | 37,378 | 9,770 | 15,857 | 3,798 |
Capital spending is the "expenditures for property, plant and equipment" line of the consolidated cash flow statement, before deducting government incentives received.
The sharp turn since FY2026 began
At the time of writing, September 2026, the annual report for FY2026, which ends in early September 2026, has not yet been filed. Figures through the third quarter have been, and what they show bears no resemblance to the steady picture in sections 1 to 5 Sourced.
| Measure | Q3 FY2025 | Q2 FY2026 | Q3 FY2026 |
|---|---|---|---|
| Revenue (US$m) | 9,301 | 23,860 | 41,456 |
| Gross margin | 37.7% | 74.4% | 84.6% |
| Operating income (US$m) | 2,169 | 16,135 | 33,318 |
| Net income (US$m) | 1,885 | 13,785 | 28,243 |
The third quarter of FY2026 ended on 28 May 2026. The company guides to fourth-quarter revenue of US$50bn plus or minus US$1bn at a gross margin of about 86% Not yet confirmed. Revenue for the first nine months was US$78,959m and capital spending was US$19,602m.
A gross margin of 84.6% is an aberration for a manufacturer. The company attributes it to demand growth driven by advances in AI outrunning its own and the industry's ability to add supply Sourced. Prices are rising; production has not suddenly become cheap. Memory is an industry that has historically produced the opposite as well, collapsing prices and losses, and FY2023 in fact ended with a net loss of US$5.8bn. This article does not assume the margin persists Not yet confirmed.
5. Company category and position in the back-end industry
The category is manufacturer, specifically an IDM and a pure-play memory company. It is not an OSAT, not an equipment maker and not a materials maker. In the back-end supply chain it stands on the side that supplies the parts that go into the package being assembled.
When Micron comes up in back-end coverage, the relationship actually at issue is this one.
6. Sites and the countries where it manufactures
The list of principal facilities in the 10-K sets out which process steps sit in which country Sourced. Notably, five countries carry assembly and test.
| Country | Wafer fabrication (front end) | Assembly and test (back end) | Notes |
|---|---|---|---|
| Taiwan | Yes | Yes, both component and module | DRAM and HBM capacity is being modernised and expanded. The Tongluo fab was acquired from Powerchip for US$1.8bn in March 2026 |
| Singapore | Yes | Yes, both component and module | Construction of an advanced packaging plant for HBM began in January 2025. An additional wafer fab within the NAND campus broke ground in January 2026 |
| United States | Yes | No, though reticle manufacturing is present | Headquarters in Boise, Idaho. Fab projects are under way in Idaho, New York and Virginia |
| Japan | Yes | No | The Hiroshima fab is being modernised for future DRAM nodes and AI memory production |
| Malaysia | No | Yes, both component and module | A back-end only site |
| China | No | Yes, both component and module | A back-end only site |
| India | No | Yes, both component and module | The assembly and test plant in Gujarat has begun commercial shipments, with volume production ramping in 2026 |
The process split is as stated in the 10-K as of 28 August 2025. Plant names, building counts and capacity by site are not disclosed Not yet confirmed.
What is easy to miss in that table is that the United States has no assembly and test site at all. The front end has real depth there, in Idaho, Virginia and New York, but the stacking process that makes HBM exists only in Taiwan, Singapore, Malaysia, China and India. The company does write in its 10-Q that it has announced plans to bring advanced HBM packaging capability to the United States, but gives no location, timing or amount Not yet confirmed. For anyone supplying materials or equipment, that means HBM-related enquiries will keep coming from the Asian back-end sites at least until the first quarter of 2027.
7. Leading products and share in semiconductor back-end work
What HBM is
The 10-K defines HBM, high bandwidth memory, as follows Sourced.
A three-dimensional stacked DRAM architecture using through-silicon via connections, which delivers high bandwidth at lower power consumption than other memory, and is therefore suited to applications such as AI and high performance computing that demand high data throughput and energy efficiency.
Ordinary DRAM is laid out flat on a board. HBM stacks the DRAM dies vertically and connects them with electrodes that pass straight through the silicon. Shorter wiring means more data moved at once and lower power. The price of that is taking on the whole difficulty of the back end, stacking and bonding.
Where the product generations stand
| Generation | Status as announced by the company on 24 June 2026 | Underlying DRAM node |
|---|---|---|
| HBM4 | Shipping in volume for a major customer's platform, with qualification samples shipped to several end customers | 1-beta |
| HBM4E | In development. Volume production planned for calendar 2027 Not yet confirmed | 1-gamma |
| 256GB DDR5 RDIMM | Qualification samples shipped to leading server ecosystem companies, built with advanced three-dimensional die stacking | 1-gamma |
The names of the "major customer" and the "end customers" are not disclosed Not yet confirmed.
On market share, plainly
Micron does not officially disclose HBM revenue, its world share of HBM, or its HBM capacity. Figures of the form "its HBM share is X per cent" or "HBM revenue in 2026 will be US$Y bn" are estimates from research firms or the press, not primary material, and this article does not use them Not yet confirmed. Only three things can be stated with confidence from primary sources.
- CMBU revenue, which contains HBM, rose 3.6-fold from US$3,792m in FY2024 to US$13,524m in FY2025 (though CMBU also contains DDR, LPDDR and GDDR) Our calculation
- One customer accounted for 17% of company revenue in FY2025, chiefly within CMBU, against a largest-customer share of 10% in FY2024 and no customer above 10% in FY2023 Sourced
- Construction of an advanced packaging plant for HBM began in Singapore in January 2025, with capacity ramping from the first half of calendar 2027 Sourced
The second is understated but important. Going from "no customer above 10%" to "one customer at 17%" in two years means the company has itself recognised, as an accounting concentration risk, that HBM as a product is tightly bound to particular customers Our calculation.
The competitors the company names
The 10-K names the following six companies as competitors in the memory market Sourced. Only some of them can build HBM, but the company does not list HBM competitors separately.
| Company | Headquarters |
|---|---|
| Samsung Electronics Co., Ltd. | South Korea |
| SK hynix Inc. | South Korea |
| Kioxia Holdings Corporation | Japan |
| Sandisk Corporation | United States |
| ChangXin Memory Technologies, Inc. (CXMT) | China |
| Yangtze Memory Technologies Co., Ltd. (YMTC) | China |
8. Current investment plans
Projects under way, as the company lists them
| Location | Substance | Timing |
|---|---|---|
| Singapore | An advanced packaging plant for HBM, materially increasing total advanced packaging capacity | Broke ground January 2025; capacity ramps from the first half of calendar 2027 |
| Singapore | An additional wafer fab, more cleanroom space, within the existing NAND campus | Broke ground January 2026; operational in the second half of calendar 2028 |
| Taiwan | Acquisition of the Tongluo wafer fab in Miaoli County from Powerchip for US$1.8bn. A second cleanroom of similar size is under construction alongside the existing building | Acquisition completed March 2026; meaningful output from the middle of calendar 2027 |
| India | The assembly and test plant in Gujarat | Commercial shipments have begun, with volume production ramping in 2026 |
| Japan | Modernisation of the Hiroshima fab for future DRAM nodes and AI memory production | Under way |
| United States, Idaho | A first fab, broke ground October 2023, and a second announced in June 2025 | First DRAM output from the first fab is expected in the second half of calendar 2027 |
| United States, New York | Up to four fabs at Clay, built out over more than 20 years. The first broke ground in January 2026 | Supplying from 2030 onwards |
Of everything above, only the HBM packaging plant in Singapore and the assembly and test plant in India are back-end capacity. The rest are wafer fabs, that is, the front end. Even as Micron nearly triples its capital spending, how much of it goes to HBM stacking capacity is not published Not yet confirmed. It is therefore impossible to say from primary sources that Micron's HBM capacity will multiply by any particular factor. What can be said is only the timing: it increases in the first half of calendar 2027.
Long-term customer contracts, new in FY2026
In the third and fourth quarters of FY2026 Micron began signing multi-year agreements it calls Strategic Customer Agreements Sourced. The company describes them as follows.
- Take-or-pay in form, with an obligation to pay whether or not the volume is collected, binding quantities over several years
- Prices are usually fixed, or set with a ceiling and a floor. In the largest agreements the ceiling on existing products is set roughly at market prices in the second quarter of calendar 2026
- On the agreements signed so far the company expects to receive US$22bn of cash deposits and related funding commitments, of which about US$18bn is cash deposits
- As of 28 May 2026 the transaction price allocated to remaining performance obligations was about US$5bn, on a minimum-volume and minimum-price basis
The US$22bn is not booked revenue; it is the total of deposits and funding commitments. The company states that the remaining performance obligation disclosure is based on minimum volumes and minimum prices and is not indicative of future revenue under those agreements Sourced. The counterparties are not named Not yet confirmed.
9. Major corporate partners
This is the section that has to be written most plainly of all.
Neither Micron's FY2025 Form 10-K nor its Q3 FY2026 Form 10-Q mentions NVIDIA, TSMC, or any other customer or partner by name, anywhere. Both documents were searched in full for this article. The only companies the filings name are the competitors listed in section 7, the counterparties to patent litigation, and government bodies. This article therefore does not record any relationship of the form "Micron HBM goes into this AI chip" as a partnership Not yet confirmed.
The relationships that can be stated from primary sources come to this table and no more.
| Kind | Counterparty | Substance | Primary source |
|---|---|---|---|
| Government | U.S. Department of Commerce | CHIPS Act direct funding agreement, signed December 2024 and amended June 2025, for up to US$6.4bn | Stated in the 10-K and 10-Q Sourced |
| Government | State of New York | Support of up to US$5.5bn, still at the stage of a non-binding term sheet | Stated in the 10-Q Sourced |
| Government | The Government of India and the State of Gujarat | Support for the assembly and test plant, shown as a separate line in the government incentives note of the 10-K | Stated in the 10-K Sourced |
| Corporate transaction | Powerchip | Acquisition of the Tongluo wafer fab in Taiwan for US$1.8bn, completed March 2026. An asset purchase, not a partnership | Stated in the 10-Q Sourced |
| Customer | Not disclosed; one customer at 17% of revenue | In FY2025, sitting chiefly within CMBU, the unit that contains HBM | Note 28 to the 10-K Sourced |
10. Where the company is heading in this field
Anything said here is a forecast, so the established facts and the outlook drawn from them are kept apart.
What is established
| Fact | What it implies for the back end |
|---|---|
| HBM4 is shipping in volume to a major customer; HBM4E is due in volume production in calendar 2027 | Stack heights and bonding methods keep advancing, so back-end requirements are rewritten each generation |
| The Singapore HBM advanced packaging plant ramps from the first half of calendar 2027 | The company's own investment confirms that the HBM constraint lies in the stacking process |
| FY2026 capital spending is about US$27bn, net of incentives | The company itself is assuming demand will hold |
| One customer was 17% of FY2025 revenue and the top ten were roughly half | HBM demand tracks the design decisions of a small number of customers |
| Take-or-pay multi-year agreements have started to be signed | A structural shift towards containing price swings by contract, which may also smooth orders for materials and equipment |
| Plans to bring advanced HBM packaging to the United States have been announced, without detail | Geographic dispersal of the back end exists as a plan |
Outlook
Not yet confirmed Read plainly, the facts above point towards Micron's weight in the back end growing further, as a supplier of HBM. The reason is simple: for anyone building an AI accelerator HBM is a component with no substitute, and only a handful of companies in the world can produce it in volume. HBM is also not a product the front end can deliver alone; it carries the back-end capabilities of stacking and bonding with it.
Not yet confirmed Two developments could break that pattern. One is supply catching up with demand. The extraordinary margins of FY2026 are being carried by price, so they are the first thing to go once supply arrives; the losses of FY2023 are the historical precedent. The other is a change in how HBM itself is stacked. If Micron's current stacking approach, whose generation-by-generation details are not disclosed, falls out of line with the industry standard, the capacity it has built stops translating into advantage. For anyone selling back-end materials or equipment, the point is to keep "HBM volumes growing" and "Micron's volumes growing" as two separate questions.
11. The risks this company carries
What follows is drawn from the risk factors Micron sets out in its own statutory filings, narrowed to those that matter in a back-end context Sourced.
| Risk | Substance | Supporting figures |
|---|---|---|
| Cyclicality | Memory prices move sharply with supply and demand, and the company names industry supply and demand as a determinant of its results | FY2022 30,758 falling to FY2023 15,540, minus 49.5%, with the operating result going from plus 9,702 to minus 5,745 Our calculation |
| Customer concentration | One customer was 17% of FY2025 revenue and the top ten were roughly half. The concentration deepened as HBM grew | As disclosed in Note 28 to the 10-K |
| The cost of system products | The company states that system-level products such as HBM carry higher manufacturing cost per unit and longer cycle times, and require development tailored to a customer, which deepens dependence on that customer | Stated in the Risk Factors of the 10-K |
| Recovering capital spending | FY2026 capital spending is planned at about US$27bn. Another FY2023 would leave fixed costs weighing heavily | Capital spending of US$19,602m over the first nine months |
| Conditions on the incentives | CHIPS Act funding is subject to milestones and compliance requirements and can be reduced, terminated or clawed back | Stated in the 10-K and 10-Q |
| Trade rules and geopolitics | Export controls, tariffs and Chinese regulatory action, including by the CAC, are listed as risks. Some back-end sites are in China | The risk factor list in the 10-K |
| Patent litigation | Netlist has brought patent infringement claims that include HBM products. In a separate matter a jury returned verdicts of US$425m and US$20m, which Micron has appealed | Note 10 to the 10-Q |
For anyone supplying materials or equipment, the number to follow at Micron is not revenue. It is CMBU revenue and operating margin each quarter, together with capital spending. CMBU is the unit that contains HBM, and the quarterly earnings release gives revenue, gross margin and operating margin for each of the four business units. The other thing worth watching would be how much of capital spending goes to the back end, and that is not disclosed. The available proxy is how the back-end sites, Singapore and India, are described in the "investments under way" passages of the 10-K and 10-Q. That wording is refreshed each quarter: between the FY2025 10-K and the Q3 FY2026 10-Q the Singapore entries went from one to two.
12. Glossary
- HBM
- High Bandwidth Memory. DRAM dies stacked vertically and joined by TSVs to gain bandwidth, placed beside an AI accelerator.
- TSV
- Through-Silicon Via. An electrode passing straight through a die, connecting stacked dies by the shortest possible path.
- IDM
- Integrated Device Manufacturer. A vertically integrated maker that holds design, front end and back end in house, such as Micron, Samsung or Intel.
- DRAM
- Fast memory that loses its contents when power is cut, holding data by continuous refresh.
- NAND
- Storage that keeps its contents without power, used in SSDs and smartphone storage.
- 1-beta and 1-gamma
- Names of Micron's DRAM process generations. 1-gamma is the first generation for which the company used EUV lithography, with shipments beginning in FY2025.
- Take-or-pay
- A contract under which the buyer owes payment whether or not it takes delivery, fixing volumes for the seller.
- Form 10-K and 10-Q
- The annual and quarterly reports a U.S.-listed company files with the Securities and Exchange Commission, carrying legal liability for their contents.
 AI-generated concept
13. References
- Micron Technology Form 10-K for the fiscal year ended August 28, 2025 (filed with the U.S. SEC on 3 October 2025). Revenue, operating income, R&D expense, capital spending, headcount, the business unit structure and results by unit, DRAM and NAND revenue, the list of principal facilities by country, customer concentration, named competitors, the CHIPS Act terms, risk factors and the definition of HBM. https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm
- Micron Technology Form 10-Q for the quarterly period ended May 28, 2026 (filed with the U.S. SEC on 25 June 2026). Third-quarter and nine-month results, the FY2026 capital spending projection of about US$27bn, the Strategic Customer Agreements, the investment projects in Singapore, Taiwan, India, Japan and the United States, the CHIPS Act and New York State support, and the status of patent litigation. https://www.sec.gov/Archives/edgar/data/723125/000072312526000015/mu-20260528.htm
- Micron Technology Third quarter FY2026 earnings release (Form 8-K, Exhibit 99.1, 24 June 2026). Quarterly revenue and margins by business unit, fourth-quarter guidance of US$50bn plus or minus US$1bn, volume shipment of HBM4 and the production timing of HBM4E, and product progress. https://www.sec.gov/Archives/edgar/data/723125/000072312526000013/a2026q3ex991-pressrelease.htm
- U.S. SEC EDGAR XBRL company facts API (CIK 0000723125). Revenue, operating income, net income, capital spending and R&D expense for FY2021 to FY2025, as tagged in each year's Form 10-K. https://data.sec.gov/api/xbrl/companyfacts/CIK0000723125.json
- Micron Technology Official website, "Our Company", used to check the year of founding and how the company began. https://www.micron.com/about/our-company
14. Claim-to-source audit
| Claim in the article | Category | Source |
|---|---|---|
| Legal name, head office address, listing (Nasdaq, MU) and Delaware incorporation | Sourced | References 1 and 2 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| Founded in 1978, starting with four people in the basement of a Boise dental office | Sourced | Reference 5, the official site https://www.micron.com/about/our-company |
| FY2025 revenue US$37,378m, operating income US$9,770m, net income US$8,539m | Sourced | References 1 and 4 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| Revenue, operating income, capital spending and R&D expense for FY2021 to FY2024 | Sourced | Reference 4, from each year's 10-K https://data.sec.gov/api/xbrl/companyfacts/CIK0000723125.json |
| The 48.9% increase, the 49.5% FY2023 decline and the NOR and other revenue taken as a difference | Our calculation | Derived from the figures in references 1 and 4 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| About 53,000 employees as of 28 August 2025 | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| The fourth-quarter FY2025 reorganisation and the definitions of the four business units | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| FY2025 revenue by business unit (CMBU 13,524, CDBU 7,229, MCBU 11,859, AEBU 4,753, other 13) | Sourced | Reference 1, Note 27 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| The business unit shares (36.2% and so on), CMBU's 3.6-fold rise and its 63% of operating income | Our calculation | Derived from the figures in reference 1 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| DRAM revenue of US$28.58bn and NAND revenue of US$8.50bn in FY2025 | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| The definition of HBM (three-dimensional stacked DRAM using TSVs) and the cost characteristics of system products | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| Customer concentration (one customer at 17% in FY2025, chiefly CMBU, top ten roughly half) | Sourced | Reference 1, Note 28 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| The six named competitors (Samsung, SK hynix, Kioxia, Sandisk, CXMT, YMTC) | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| Principal facilities by country and the process steps at each (front end in four countries, back end in five) | Sourced | Reference 1 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| Q3 FY2026 results (revenue 41,456, gross margin 84.6%, net income 28,243, US$m) and the nine-month totals | Sourced | References 2 and 3 https://www.sec.gov/Archives/edgar/data/723125/000072312526000015/mu-20260528.htm |
| Q4 FY2026 guidance (revenue US$50bn plus or minus US$1bn, gross margin about 86%) | Not yet confirmed | Reference 3, company guidance https://www.sec.gov/Archives/edgar/data/723125/000072312526000013/a2026q3ex991-pressrelease.htm |
| FY2026 capital spending of about US$27bn, net of government incentives | Not yet confirmed | Reference 2, company projection https://www.sec.gov/Archives/edgar/data/723125/000072312526000015/mu-20260528.htm |
| CHIPS Act direct funding of up to US$6.4bn, the 35% investment tax credit and up to US$5.5bn from New York State | Sourced | Reference 2 https://www.sec.gov/Archives/edgar/data/723125/000072312526000015/mu-20260528.htm |
| The Singapore HBM advanced packaging plant (ground broken January 2025, ramping in the first half of calendar 2027) and the additional building in the NAND campus | Sourced | Reference 2 https://www.sec.gov/Archives/edgar/data/723125/000072312526000015/mu-20260528.htm |
| The acquisition of the Tongluo fab in Taiwan from Powerchip for US$1.8bn, completed March 2026 | Sourced | Reference 2 https://www.sec.gov/Archives/edgar/data/723125/000072312526000015/mu-20260528.htm |
| The Gujarat assembly and test plant, the Hiroshima modernisation and the Idaho and New York fab plans | Sourced | References 1 and 2 https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| Volume shipment of HBM4 and volume production of HBM4E planned for calendar 2027 | Sourced, with the production timing not yet confirmed | Reference 3 https://www.sec.gov/Archives/edgar/data/723125/000072312526000013/a2026q3ex991-pressrelease.htm |
| The Strategic Customer Agreements (take-or-pay, US$22bn of deposits and commitments, about US$18bn in cash, about US$5bn of remaining performance obligations) | Sourced | Reference 2 https://www.sec.gov/Archives/edgar/data/723125/000072312526000015/mu-20260528.htm |
| The Netlist patent litigation covering HBM products and the US$425m and US$20m verdicts | Sourced | Reference 2, Note 10 https://www.sec.gov/Archives/edgar/data/723125/000072312526000015/mu-20260528.htm |
| World share of HBM, HBM revenue on its own, and HBM capacity | Not yet confirmed | None of it is disclosed. No primary source exists, so this article states no figure |
| Relationships with named customers and partners such as NVIDIA or TSMC | Not yet confirmed | No company name appears anywhere in references 1 or 2, so this article does not treat any as a partnership https://www.sec.gov/Archives/edgar/data/723125/000072312525000028/mu-20250828.htm |
| Location, timing and scale of advanced HBM packaging in the United States | Not yet confirmed | Reference 2 records only that the plan exists; no details are published https://www.sec.gov/Archives/edgar/data/723125/000072312526000015/mu-20260528.htm |
| Capacity by site, plant names, and the share of capital spending allocated to the back end | Not yet confirmed | None of it is disclosed, so this article states no figure |
| The outlook in section 10 | Not yet confirmed | An interpretation by this article, drawn from the six items in the facts table |
Last updated 21 September 2026 / Troy Technical
Every figure in this article comes from Micron Technology, Inc.'s statutory filings with the U.S. Securities and Exchange Commission or from the company's own announcements. No research-firm estimates or press-based figures have been used.