COMPANY PROFILE / SEMICONDUCTOR BACK-END
Powertech Technology
The company that packages memory, reaching for the panel
Powertech Technology, usually written PTI, is a Taiwanese OSAT, a contractor for semiconductor back-end work. Founded in 1997, it started life testing DRAM and flash memory, and packaging and testing memory is still its main business. Yet for the last few years what the company has pushed hardest is FOPLP, fan-out panel level packaging, which builds packages on a large rectangular panel instead of a round wafer. This profile separates what is settled from what is the company's own claim, using published material only.
- Powertech in 30 seconds
- The logo and how the name is written
- What the company actually does: contract back-end work
- Scale: five years of revenue
- Company category and position in the back-end industry
- Sites and the countries where it manufactures
- Leading products and share in semiconductor back-end work
- Current investment plans
- Major corporate partners
- Where the company is heading in this field
- The risks this company carries
- Glossary, references and claim-to-source audit
1. Powertech in 30 seconds
(OSAT, contract back-end work)No products of its own; it assembles and tests other companies' chips
Hsinchu Science Park, December 2025To expand advanced packaging. The price is not disclosed
PTI neither designs chips nor makes wafers. It takes in a customer's wafers, dices them, mounts the dies, encapsulates them, tests them and hands them back. Most of its revenue comes from packaging and testing memory, DRAM and NAND flash. What matters in this profile is that a company which was close to a pure memory house is now trying to widen its footing into large packages for logic. In the 2025 report to shareholders, the chairman said FOPLP capacity was far below customer demand and that a large capital programme had begun Sourced.
2. The logo and how the name is written
The Powertech Technology logo is a trademark of the company.
A note on style: the English name is Powertech Technology Inc. and the short form is PTI. The company also has a Chinese-language legal name, which is the one that appears on its Taiwanese filings. It is unrelated to the similarly named company in South Korea, and to the various power-supply makers that also trade as Powertech. Its ticker is 6239 on the Taiwan Stock Exchange, and its GDRs were delisted from the Luxembourg Stock Exchange on 16 December 2024.
Official site: https://www.pti.com.tw/en/3. What the company actually does: contract back-end work
Making a semiconductor splits broadly into the front end and the back end. The front end runs to the point where the circuits are built into the wafer. The back end is everything after that.
| What PTI takes on | What happens |
|---|---|
| IC assembly | The wafer is diced into individual dies, mounted on a substrate or lead frame, connected by wire or bump, and sealed in resin to become one component |
| Final test | The part is exercised at room, high and low temperature, and sorted to the customer's conditions |
| Burn-in | The part is driven hard under severe conditions so that early failures surface before shipment |
| Laser marking | The company name and part number are marked on the surface of the product |
PTI's selling point is taking all four together as a turnkey Sourced. From the customer's side, handing over wafers and getting tested product back removes both the work of splitting the job across several suppliers and the transport cost between them.
The company was incorporated in May 1997. By its own account, it began memory IC test services that August, after winning test orders for Powerchip's DRAM and Macronix's flash memory Sourced. It was a memory company from the first day, and that origin still shows in the revenue mix.
PTI's annual report names its principal raw materials and the suppliers of each Sourced. Few back-end companies go that far. The 2025 edition lists the following.
Lead frames: Shinko Electric Industries, Chang Wah Technology and Nichiden Precision Industry. Substrates: Kinsus, Shinko Electric Industries, Simmtech and Samsung Electro-Mechanics among others. Die attach film: Resonac Semiconductor Materials Taiwan, Nitto Denko, Lintec and Henkel Korea. Gold wire: Nippon Micrometal and Tanaka Kikinzoku Kogyo. Encapsulants: Chao Young, Resonac, Kyocera and Chang Wah Technology.
Laid out like that, the list is dominated by Japanese and South Korean materials makers, with a Japanese supplier in every one of lead frames, die attach film, gold wire and encapsulant. For anyone selling materials, an OSAT's procurement list is a way of reading which generation of materials that company is on. That live suppliers of gold wire and lead frames sit side by side here says that conventional wire-bonded packages are still the mainstay by volume.
4. Scale: five years of revenue
| Year | Consolidated revenue (NT$m) | Change year on year |
|---|---|---|
| 2021 | 83,794 | +9.99% |
| 2022 | 83,927 | +0.16% |
| 2023 | 70,441 | -16.07% |
| 2024 | 73,315 | +4.08% |
| 2025 | 74,929 | +2.20% |
Profit, meanwhile, went the other way
| Item (NT$ thousand) | 2024 | 2025 | Change |
|---|---|---|---|
| Revenue | 73,315,042 | 74,929,320 | +2.20% |
| Gross profit | 13,991,440 | 12,729,191 | -9.02% |
| Operating income | 9,382,266 | 8,131,839 | -13.33% |
| Pre-tax income | 10,677,286 | 8,792,152 | -17.66% |
| Net income, consolidated | 8,499,407 | 7,220,542 | -15.05% |
| Net income to owners of the parent | 6,788,000 | 5,536,000 | -18.45% |
| Earnings per share | NT$9.09 | NT$7.48 | -17.7% Our calculation |
Net income to owners of the parent is the company's own NT$5,536m and NT$6,788m, restated here in thousands. The company attributes the decline to a change in product mix and continued investment in advanced technology. A dividend of NT$4.50 per share, about 62% of earnings, has been proposed for 2025.
Research and headcount
| Item | 2024 | 2025 | As of 31 March 2026 |
|---|---|---|---|
| R&D expense | not given | NT$2,807m (3.74% of revenue) | planned at the 2025 level |
| Managers | 606 | 600 | 603 |
| Technical staff | 2,915 | 2,877 | 3,171 |
| Clerical staff | 425 | 412 | 435 |
| Operators (shop floor) | 7,412 | 7,294 | 8,460 |
| Total | 11,358 | 11,183 | 12,669 |
What stands out is the hiring since the start of 2026. From 11,183 at the end of 2025 the headcount reached 12,669 by the end of March 2026, a gain of 1,486 in three months Our calculation. Nearly all of the increase is shop-floor operators, up 1,166, which says plants are being brought up. By education the split was 8.26% master's degrees and 72.93% bachelor's in 2025, a long way from the research-led profile of a company like TSMC Sourced. An OSAT remains a business where the tools are lined up and people run them.
5. Company category and position in the back-end industry
The category is manufacturer, an OSAT. It has no branded semiconductors of its own, does no front-end work, and takes on the back end only.
PTI does not name its customers, but it does publish the share each of the top three takes Sourced. In 2025 the first was 21.08%, the second 19.88% and the third 10.04%, coming to 51.0% together Our calculation. The second is further marked as a related party, so a fifth of revenue comes from a counterparty in which there is a shareholding relationship. The company itself lists as a risk factor that the more concentrated the upstream memory IC market becomes, the more concentrated revenue becomes for the packaging and test firms downstream.
6. Sites and the countries where it manufactures
Every plant is in the Hsinchu area of Taiwan Sourced. The overseas production subsidiaries were wound down across 2023 and 2024.
| Site | Location | Role |
|---|---|---|
| Head office and plant 3 | Nos. 10, 15 and 26 Datong Rd. and others, Hsinchu Industrial Park, Hukou, Hsinchu County | Head office functions and the lead plant. The head office moved to the new 3C plant in 2013 |
| Plant 1 | Wenshan Rd., Xinpu Township, Hsinchu County | The original plant, completed in June 2000 |
| Plants 2, 9 and 10 | Hsinchu Industrial Park (Sanmin Rd., Wenhua Rd. and Xinxing Rd.) | Volume assembly and test |
| Science park plants 1, 2 and 3 | Hsinchu Science Park, Lixing 3rd Rd. and Lixing 4th Rd. | The advanced packaging sites. Science park plant 3, known as P11, is being expanded |
| Science park plant 5 | No. 23, Lixing Rd., Hsinchu Science Park | Acquired in December 2025. By the chairman's account it was formerly AUO's L3C plant |
| Group companies | Taiwan | Greatek Electronics, Tera Probe and TeraPower Technology |
PTI once had production in China and in Japan, and both have been wound down Sourced.
For the Suzhou subsidiary, the board resolved in June 2023 to sell a 70% interest, citing the intensification of trade friction between the United States and China; the transaction contributed NT$3.5 to earnings per share in 2023. The subsidiary at Xi'an had been set up under a contract with Micron Technology, and the transfer of its assets completed on 28 June 2024 when the contract ran its course and Micron exercised its purchase right. The plant in Akita, Japan, had been bought from Micron; the board decided in August 2020 to end the business because of poor results, and the liquidation completed in September 2024. As a result, PTI's capacity is now concentrated in Taiwan.
Fig. 3 looks dramatic, but it needs reading carefully. All of PTI's plants are in Taiwan, so this is not production moving, it is the billing address, the country where the customer is registered Our calculation. Singapore falling from NT$18.4bn to NT$2.8bn while a similar amount appears in domestic Taiwan suggests the contracting entity on the customer's side changed. But the company gives no explanation for the swap Not yet confirmed. For anyone delivering materials, the important thing is not to mistake a movement in revenue by region for a movement in plants. The actual logistics, and the delivery addresses for tools and materials, are still concentrated in Hsinchu.
7. Leading products and share in semiconductor back-end work
The product families
- Memory packages
- TSOP, BGA in its wBGA and FBGA forms, MCP, SD and USB cards, SSDs, eMMC, eMCP and UFS, and stacked DRAM. Where PTI began, and still its mainstay.
- FOPLP
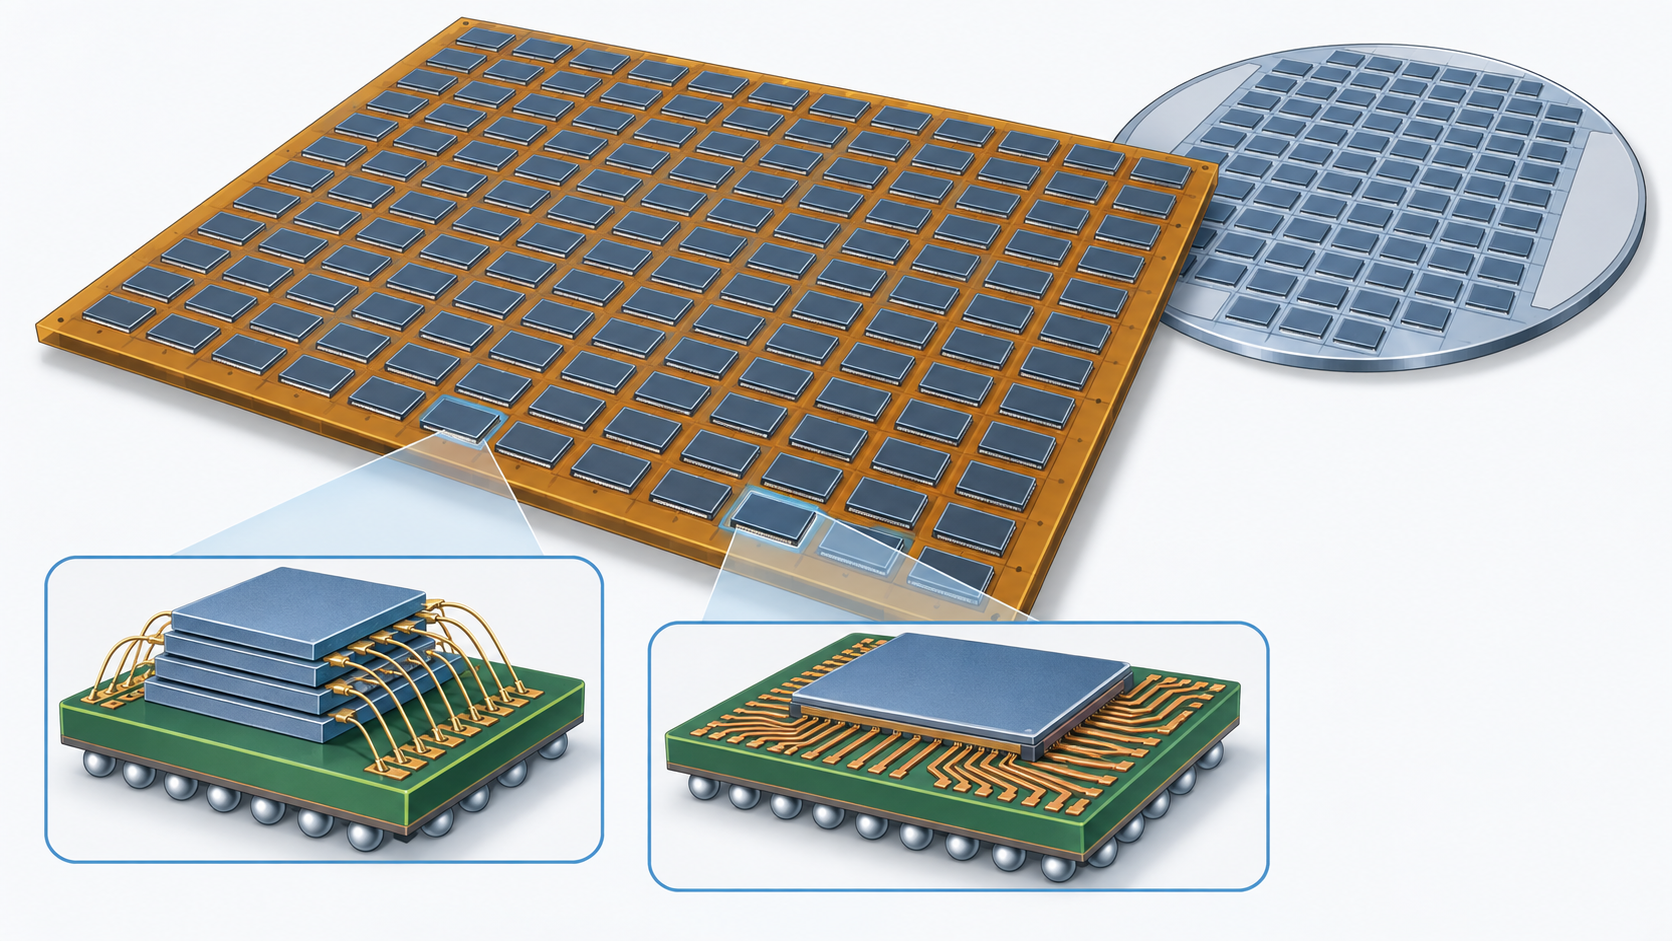
- Fan-Out Panel Level Packaging. Redistribution layers are built on a large rectangular panel and the dies embedded in it. PTI claims to run the most mature volume line in the world.
- Flip chip families
- Copper pillar bump, FCCSP and FCBGA. It also handles large FCBGA above 100mm by 100mm, and FCLGA using metal conductive adhesive for heat dissipation.
- TSV applications
- Through-silicon vias. The company states it applies them to HBM stacking, CMOS image sensors and the optical engines for co-packaged optics.
- SiP and modules
- System-in-package, putting several components into one, and module assembly for SSDs and the like. 10.77% of revenue.
- Wafer test (CP)
- Testing at the wafer stage, before dicing. Its subsidiary Tera Probe works in this area too.
On market share, plainly
PTI publishes no figure for its market share. The annual report says only, qualitatively, that its share among the world's leading packaging and test companies may keep rising, and that it expects share to rise again in 2026. No percentage appears Not yet confirmed. Rankings of the form "number X in the world for memory back-end work" are not used here either. The market-size figures that do appear in that report, from WSTS, IEK, Gartner, IDC and others, are all outside estimates, so they are not used here.
What is practical instead is to look at the volume plan the company publishes itself. PTI gives its expected 2026 production and sales volumes as follows Sourced.
| Process | Expected volume in 2026 |
|---|---|
| Assembly | 11.8 billion units |
| Final test | 7.8 billion units |
| Wafer-level packaging | 1.11 million wafers |
| Wafer test (CP) | 1.39 million wafers |
| SSD and SiP | 293 million units |
What PTI pushes hardest is its FOPLP volume line Sourced. The company's case is that, against FOWLP, which builds fan-out on a round wafer, the panel gives more area at lower cost, and so offers a route to cheaper AI silicon. Among the technical results it published in 2025 are achieving 3µm line and 3µm space redistribution layers in FOPLP and applying them to ICs for high performance computing, and integrating an SoC with HBM in FOPLP at the chip-middle stage.
From the materials side, going to a panel changes the properties under question wholesale: the resolution and thickness uniformity of the photosensitive dielectric in the redistribution layers, the warpage and the mismatch in thermal expansion that come with the larger format, the filler dispersion and cure shrinkage of the moulding compound used to embed the dies, and adhesion to the copper seed layer. A formulation that qualified on a wafer is not guaranteed to qualify on a panel. That said, PTI publishes neither FOPLP revenue nor FOPLP capacity Not yet confirmed. What can be established today goes only as far as the company saying this is where it is investing first.
8. Current investment plans
December 2025The board resolved on the purchase in November 2025. The price is not disclosed
Investing cash flow in 2025 was minus NT$26,023m, far exceeding the year's operating cash flow of plus NT$16,698m Sourced. The gap was filled with bank borrowing, financing cash flow of plus NT$4,197m. Property, plant and equipment rose in one year from NT$56,588m to NT$70,412m, up 24.43%, and long-term liabilities from NT$19,142m to NT$28,113m, up 46.86%. This is a company borrowing to add plants.
In the 2025 report to shareholders the chairman wrote as follows Sourced. The company's existing FOPLP technology leads the world, and its capacity falls far below customer demand; a large capital programme has therefore begun, with the purchase of science park plant 5 in Hsinchu Science Park, formerly AUO's L3C plant, and an acceleration of the capacity expansion at science park plant 3, the P11 plant. The goal for the year is to complete the plant expansion plan on schedule by year end.
Neither the purchase price nor the total investment is published Not yet confirmed. The plant expansion section of the annual report states that there is no material expansion plan as of the printing date, and then records only the board resolution of November 2025 and the transfer of title in December. Amounts that have appeared in the press are not used here.
9. Major corporate partners
In PTI's case, what is published as a relationship is mostly shareholdings and group companies. Technology partners are almost never named.
| Kind | Counterparty | Substance | Primary source |
|---|---|---|---|
| Major shareholder | Kingston Technology Corporation (United States) | Holds 29,875,000 shares, or 3.94%, through an investment account. The company names it among its notable shareholders | Stated in the 2025 annual report Sourced |
| Major shareholder | Taiwan Toshiba Semiconductor | Named by the company as a notable corporate holder. Its stake does not appear in the top ten table | Stated in the 2025 annual report Sourced |
| Institutional holders | Various ETFs, Cathay Life Insurance, the Labor Pension Fund | The largest is the Capital Tip Customized Taiwan Select High Dividend ETF at 5.55% | Stated in the 2025 annual report Sourced |
| Group company | Greatek Electronics | 44% acquired through a tender offer in February 2012. Greatek in turn holds 2.68% of PTI, a cross-shareholding | The company history and the shareholder list Sourced |
| Group company | Tera Probe, Inc. (Japan) | Shares acquired from Micron Technology in April 2017. Wafer test | The company history Sourced |
| Group company | TeraPower Technology | Named by the company as one of its three group companies | The official website Sourced |
| Former counterparty | Micron Technology (United States) | A December 2014 agreement to invest in semiconductor manufacturing at Xi'an. The contract ran its course, the assets transferred on 28 June 2024, and the relationship ended | Stated in the 2025 annual report Sourced |
In PTI's annual report the major customers appear only as A, B and C Sourced. Amounts and percentages are disclosed; the names are withheld. The second customer is footnoted as a related party, which tells you there is a shareholding relationship, but this article does not guess at the names Not yet confirmed.
10. Where the company is heading in this field
Anything said here is a forecast, so the facts that ground the judgement and the outlook drawn from them are kept apart.
What is established
| Fact | What it implies for the back end |
|---|---|
| Revenue for January to August 2026 totalled NT$61,258m, up 30.83% year on year | A clear turn to growth after the flat years through 2025 |
| Headcount reached 12,669 at the end of March 2026, up 1,486 in three months | The capacity build-out is showing in people as well as tools |
| Title to science park plant 5 transferred in December 2025 | A building for advanced packaging has been secured |
| Investing cash flow in 2025 was minus NT$26,023m | Investment beyond operating cash flow, funded by borrowing |
| It reports achieving 3µm line and space redistribution in FOPLP and applying it to high performance computing ICs | The technology is being extended beyond memory |
| The 2026 assembly volume plan is 11.8 billion units | By unit volume this is still a mass-production business |
| The top three customers are 51.0% of revenue, one of them a related party | The customer base is not spread out |
Outlook
Not yet confirmed Confined to the back end, PTI's standing comes down to one question: can an OSAT that is close to a pure memory house get inside large packages for logic? The growth since the start of 2026, above 30% year on year, the capital spending funded by borrowing, and nearly 1,500 extra people in three months are all figures that say the company is acting on a conviction that demand is rising.
Not yet confirmed The same documents give reasons for caution. In 2025 revenue rose 2.20% while operating income fell 13.33%, and the company put that down to a change in product mix and investment in advanced technology. While a company is investing in a new technology, profit gets cut before revenue grows, which is an ordinary enough pattern. And as long as neither FOPLP revenue nor FOPLP capacity is published, there is no basis in today's primary material for writing that PTI is about to redraw the map with panel level packaging.
11. The risks this company carries
What follows is drawn from the risk factors PTI itself sets out in its annual report, narrowed to those that matter in a back-end context Sourced.
| Risk | Substance | Supporting figures |
|---|---|---|
| Customer concentration | The top three customers are 51.0% of revenue. The company itself writes that the more the upstream memory market concentrates, the more the downstream concentrates too | 21.08% plus 19.88% plus 10.04% Our calculation |
| The memory cycle | Revenue fell 16.07% in 2023. The heavier the memory weighting, the wider the swing | NT$83,927m down to NT$70,441m |
| Capital intensity and interest rates | The company writes that its industry is capital intensive and that its main source of funds is bank borrowing. Rate movements feed straight into profitability | Long-term liabilities up 46.86% in one year |
| Currency | Exports are 58.99% of revenue, while tools and raw materials are bought chiefly in U.S. dollars and Japanese yen | A foreign exchange loss of about NT$82m in 2025 |
| Labour shortage | Listed by the company as a risk factor, to be met by automation, work with universities and training of skilled foreign workers | 1,486 people added by the end of March 2026 Our calculation |
| New entrants to the back end | The company writes that foundries and PCB makers are entering packaging together | The risk analysis in the annual report |
| Falling margins | Revenue rose in 2025 while gross profit fell 9.02% and operating income 13.33% | Figures disclosed by the company |
| Geographic concentration | Every plant is in the Hsinchu area of Taiwan. The overseas sites were wound down in 2023 and 2024 | The plant list and the statements on investment policy |
12. Glossary
- OSAT
- Outsourced Semiconductor Assembly and Test. A company that takes on back-end work, assembly and test, on contract. PTI is one of them.
- Turnkey
- Taking assembly, test and packing together under a single order, so the customer need not split the work between suppliers.
- FOPLP
- Fan-Out Panel Level Packaging. Redistribution layers are built on a large rectangular panel and the dies embedded in it.
- FOWLP
- Fan-Out Wafer Level Packaging. The same idea carried out on a round wafer, with poorer area efficiency than a panel.
- TSV
- Through-Silicon Via, wiring that runs vertically through a die. Used for HBM stacking among other things.
- DAF
- Die Attach Film, the film adhesive that bonds a die to a substrate or to another die.
- CP (chip probing)
- Testing each die with probe needles before the wafer is diced, to judge it good or bad.
- MOPS
- Market Observation Post System, the official platform through which listed companies in Taiwan make their statutory disclosures.
 AI-generated concept
13. References
- Powertech Technology Inc. 2025 Annual Report, English edition, printed 28 April 2026 and published on Taiwan's MOPS and the company's IR site. Revenue, profit and EPS, the report to shareholders, the revenue split by service and by region, the shares taken by the major customers, the principal raw materials and their suppliers, headcount and education mix, the list of plants and offices, capital and shares, major shareholders, dividends, cash flow, capital expenditure, the wind-down of the overseas subsidiaries, the 2026 volume plan and the risk analysis. https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261
- Powertech Technology Inc. Monthly Revenue. Consolidated monthly and cumulative revenue for January to August 2026, with the year-on-year comparisons. https://www.pti.com.tw/en/ir/financial/monthly
- Powertech Technology Inc. PTI's Milestone (the company history). Incorporation in May 1997 and the first memory IC test orders that August, the over-the-counter listing of April 2003 and the Taiwan Stock Exchange listing of November 2004, the completion of the Xinpu plant in 2000, the 3C plant and head office move of 2013, the Greatek shares of 2012 and the Tera Probe shares of 2017. https://www.pti.com.tw/en/about/histories
- Powertech Technology Inc. IR financial information (fact sheet). The three-way 2025 split of packaging, test and SiP and modules, and consolidated revenue from 2020 to 2025. https://www.pti.com.tw/en/ir/financial
- Powertech Technology Inc. Annual report index page, used to locate each year's report. https://www.pti.com.tw/en/ir/financial/annual
- Powertech Technology Inc. Official website, used to check the corporate profile, the group companies and the brand mark. https://www.pti.com.tw/en/
14. Claim-to-source audit
| Claim in the article | Category | Source |
|---|---|---|
| Legal name, head office address, incorporation in May 1997 with paid-in capital of NT$600m, ticker 6239 | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The over-the-counter listing of April 2003 and Taiwan Stock Exchange listing of November 2004, the years the plants were completed, and the Greatek and Tera Probe share acquisitions | Sourced | Reference 3 https://www.pti.com.tw/en/about/histories |
| Consolidated revenue and year-on-year change, 2021 to 2025 | Sourced | The revenue table in reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| Gross profit, operating income, pre-tax income, net income and EPS for 2024 and 2025 | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The 17.7% fall in EPS, the 51.0% top-three customer total, and the 1,486 people added by the end of March 2026 | Our calculation | Derived from the figures disclosed in reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The 2025 revenue split by service, with packaging at 61.76% and the rest | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The three-way split on the IR fact sheet: packaging 67%, test 22%, SiP and modules 11% | Sourced | Reference 4 https://www.pti.com.tw/en/ir/financial |
| Revenue by region for 2024 and 2025, covering domestic Taiwan, Japan, Singapore, North America and the rest | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The "other" category in Fig. 3, being Europe, China and Hong Kong and the rest combined | Our calculation | Summed from the regional revenue table in reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The named suppliers of the principal raw materials: lead frames, substrates, die attach film, gold wire and encapsulants | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| Headcount by job type and education, and R&D expense of NT$2,807m, 3.74% of revenue | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The list of plants and offices and their locations | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The sale of 70% of the Suzhou subsidiary in 2023, the asset transfer at Xi'an completed on 28 June 2024, and the liquidation of the Akita subsidiary completed in September 2024 | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| 2025 cash flow: operating plus NT$16,698m, investing minus NT$26,023m, financing plus NT$4,197m, and the 2026 estimate | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The acquisition of science park plant 5, resolved in November 2025 with title transferred in December, and the chairman's remarks on FOPLP | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The 2026 volume plan: 11.8 billion units of assembly, 7.8 billion units of final test and the rest | Sourced | Reference 1. This is the company's plan, not a result https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| Cumulative revenue of NT$61,258m for January to August 2026, up 30.83% year on year | Sourced | Reference 2 https://www.pti.com.tw/en/ir/financial/monthly |
| The major shareholders, including Kingston Technology at 3.94%, the various ETFs and Greatek at 2.68% | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| The three group companies: Greatek, Tera Probe and TeraPower Technology | Sourced | Reference 6 https://www.pti.com.tw/en/ |
| The proposed 2025 dividend of NT$4.50 per share, about 62% of earnings, and the GDR delisting of 16 December 2024 | Sourced | Reference 1 https://www.pti.com.tw/Handlers/CompanyAnnualReportDownload.ashx?lang=en&id=e76204b6-f4bd-4549-8abe-d6f37f7a0261 |
| PTI's market share, in memory back-end work and in FOPLP alike | Not yet confirmed | Not disclosed. The company offers only qualitative statements, and this article does not use research-firm estimates |
| FOPLP revenue, capacity and yield | Not yet confirmed | Absent from the published material, so this article states no figure |
| The price of science park plant 5 and the total capital investment | Not yet confirmed | Absent from the published material, and this article does not use amounts reported in the press |
| The names of the customers recorded as A, B and C | Not yet confirmed | The annual report gives letters only, and this article does not guess at the names |
| Why Singapore fell away and domestic Taiwan roughly doubled in the regional revenue | Not yet confirmed | The company gives no explanation, and this article asserts no interpretation |
| The outlook in section 10 | Not yet confirmed | An interpretation by this article, drawn from the seven items in the facts table |
Last updated 21 September 2026 / Troy Technical
Every figure in this article comes from Powertech Technology's published annual report, its monthly revenue announcements and its investor relations pages. No research-firm estimates or press-based figures have been used.