COMPANY PROFILE / SEMICONDUCTOR BACK-END
Samsung Electro-Mechanics
The company that makes the board a chip sits on has become part of the AI supply constraint
Samsung Electro-Mechanics does not make semiconductors. It is an electronic components maker, producing MLCCs, multilayer ceramic capacitors, camera modules and package substrates. It enters any discussion of the back end because it supplies the FC-BGA substrates that carry AI accelerator and server CPU dies. This profile follows not the contents of a package but the vessel it sits in, using only the figures the company has published.
Several Korean semiconductor companies carry the Samsung or SK name, and in any discussion of the back end three of them tend to appear at once. All three are separate legal entities, with different owners and different businesses.
1. Samsung Electro-Mechanics (the subject of this profile) = an electronic components maker producing package substrates such as FC-BGA, and MLCCs. It makes no semiconductors of its own.
2. Samsung Electronics = an IDM with memory, logic and a foundry. It belongs to the same Samsung Group but is a separately listed company, with its own business and its own accounts.
3. SK hynix = a memory specialist belonging to the SK Group, and a leading supplier of HBM. It is not part of the Samsung Group.
Companies 1 and 2 use the same SAMSUNG mark but are different legal entities; companies 2 and 3 are competitors. This profile deals only with company 1.
- Samsung Electro-Mechanics in 30 seconds
- The logo and how the name is written
- What the company actually does: three businesses combined
- Scale: five years of revenue
- Company category and position in the back-end industry
- Sites and the countries where it manufactures
- Leading products and share in semiconductor back-end work
- Current investment plans
- Major corporate partners
- Where the company is heading in this field
- The risks this company carries
- Glossary, references and claim-to-source audit
1. Samsung Electro-Mechanics in 30 seconds
(electronic components)Makes no chips; makes the substrates chips sit on, and passive components
The word packaging carries two meanings. One is the work of dicing, stacking and encapsulating chips. The other is the board those chips sit on, the package substrate. Samsung Electro-Mechanics makes the second, so it sells a component, not a service Sourced.
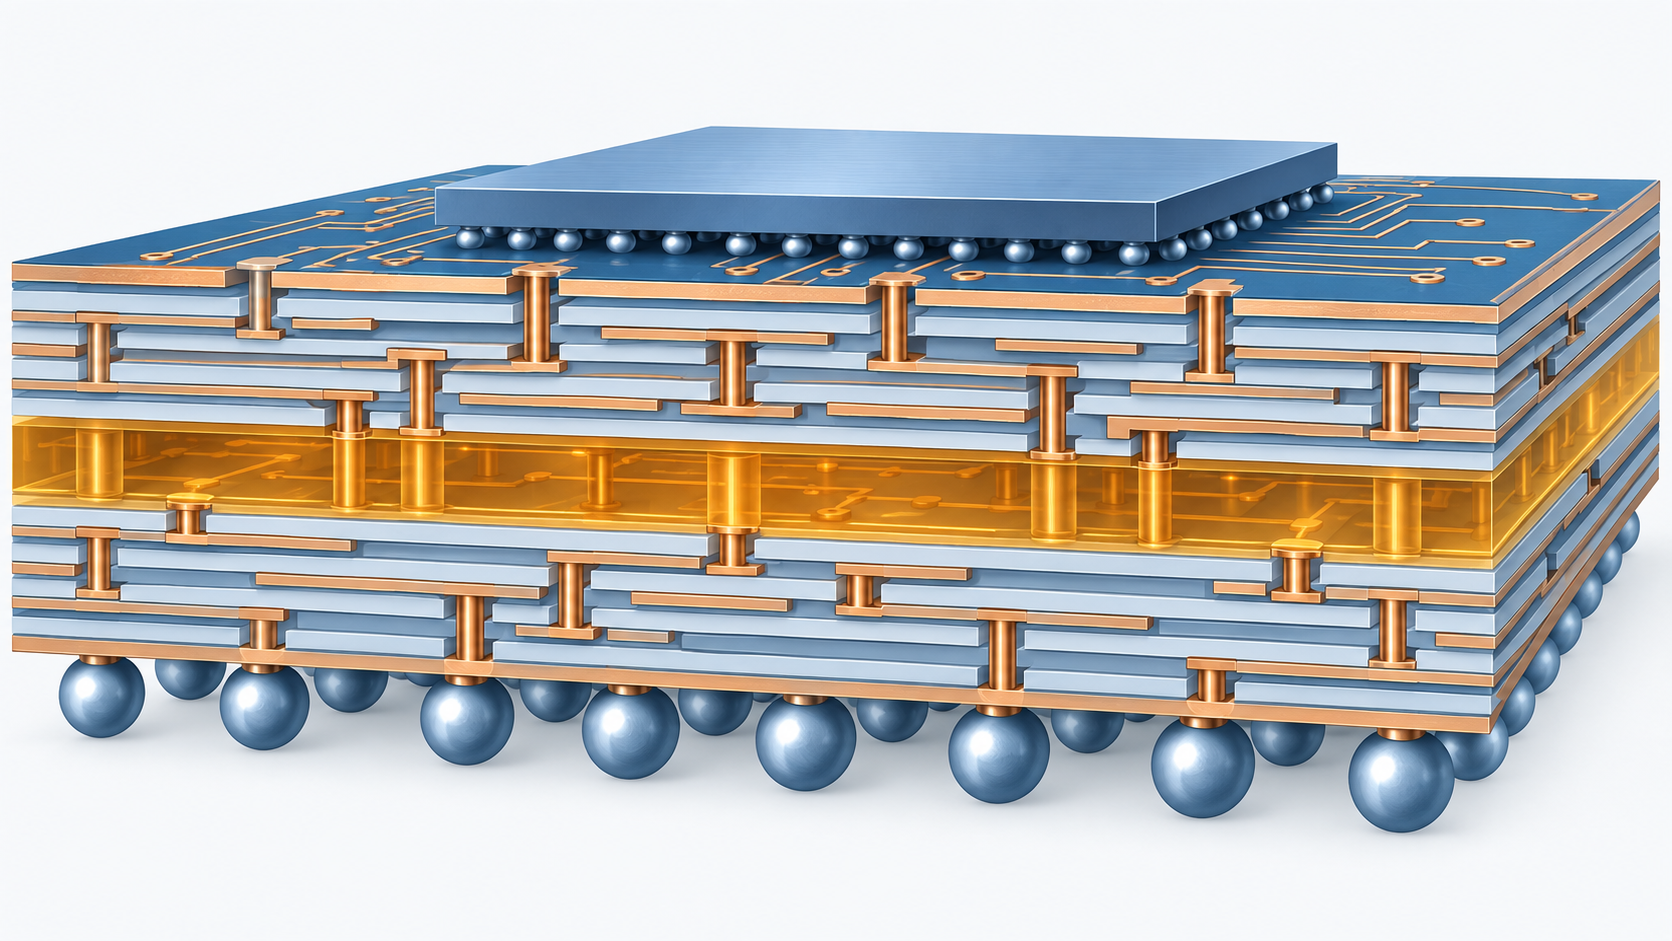
The distinction matters. Under the silicon interposer of an advanced package such as TSMC's CoWoS there is always a large resin substrate. That substrate is the FC-BGA, and the AI accelerator versions are so large in area and so numerous in layers that very few companies anywhere can build them. Which is to say that this company sits in the bottleneck on the materials side of the back end rather than in the back-end process itself.
2. The logo and how the name is written
The SAMSUNG logo is a registered trademark. This article reproduces no generated or illustrated version of it; where the mark is shown, the frame above must hold the genuine logo file taken from the official site. A logo redrawn by an AI to look approximately right is wrong both as a trademark and as a matter of fact.
A note on style: this company is separately listed from Samsung Electronics. They share the SAMSUNG brand and are constantly confused, but they have different tickers and different accounts. Internal and English-language material often uses the short form SEMCO. In English the safest habit is to write the name out in full, since Electro-Mechanics and Electronics are easy to mistake for one another at a glance.
Official site: https://www.samsungsem.com/global/about-us/company/overview.do3. What the company actually does: three businesses combined
The company is organised into three businesses Sourced.
| Business | Main products | 2025 revenue (KRW 100m) | Share |
|---|---|---|---|
| Components | MLCCs (multilayer ceramic capacitors), silicon capacitors, inductors, chip resistors, tantalum capacitors | 51,985 | 45.95% |
| Optics Solutions | Camera modules, for smartphones and for vehicles | 38,142 | 33.71% |
| Package Solutions | Semiconductor package substrates (FC-BGA and BGA) | 23,018 | 20.34% |
| Total | - | 113,145 | 100% |
Korean disclosure counts in units of KRW 100 million, so KRW 1tn is written as 10,000. The shares are the figures the company publishes in its sustainability report.
The back-end business is Package Solutions, whose products the company describes as follows Sourced.
- BGA (Ball Grid Array)
- A substrate used with the core chips of mobile devices and PCs. It carries electrical signals between the chip and the main board and shields the chip from its surroundings. The main product, FCCSP, joins chip to substrate with ball-shaped bumps instead of wire bonds, and is a highly integrated type in which the chip occupies more than 80% of the package area.
- FC-BGA (Flip Chip Ball Grid Array)
- A highly integrated package substrate joined to the chip by bumps, with better electrical and thermal behaviour. The company writes that as CPU substrate circuitry grows denser the layer count rises, making fine layer-to-layer registration accuracy and the ability to build a thin substrate steadily more important.
- Where the technology is going
- The company names four development axes: thinning, meaning coreless construction; embedding passive components; larger area with more layers; and finer line and space. Its own diagram ties larger area and more layers to servers and networking, and thinning to notebook PCs.
Read a profile of a chipmaker and materials look like a bit player somewhere in the process. For a package substrate maker, the product itself is a laminate of materials. Resin insulating layers, copper wiring layers, via fill, surface finish: stack dozens of those and you have an FC-BGA. The development axes the company names, thinning, larger area with more layers, and finer geometry, translate directly into materials questions: how thin can a layer be made, and how far can warpage be held down.
On the large, many-layered substrates for servers and AI in particular, warpage from the thermal history of curing and lamination goes straight to yield. That the company records in its own history that it signed a memorandum of understanding with the Sumitomo Chemical group in November 2025 on glass cores for package substrates is primary evidence that it is exploring a move from a resin core to a glass one in response Sourced.
4. Scale: five years of revenue
| Year | Revenue (KRW 100m) | Operating profit (KRW 100m) | Operating margin | R&D expense (KRW m) |
|---|---|---|---|---|
| 2021 | 96,750 | 14,869 | 15.4% | 567,194 |
| 2022 | 94,066 | 12,058 | 12.8% | 577,140 |
| 2023 | 88,924 | 6,605 | 7.4% | 555,756 |
| 2024 | 102,941 | 7,350 | 7.1% | 666,310 |
| 2025 | 113,145 | 9,133 | 8.1% | 786,951 |
The operating margins are derived from the revenue and operating profit the company discloses Our calculation; only the 8.1% for 2025 is stated by the company itself. R&D expense is as published in the sustainability report, and its ratio to revenue has risen from 5.9% in 2021 to 7.0% in 2025. The 2023 figures have been restated because part of the business was reclassified as discontinued.
What the 36,500 employees represent
| Region | People | Share of the total |
|---|---|---|
| Korea | 12,176 | 33.4% |
| Asia outside Korea | 24,229 | 66.4% |
| Americas | 59 | 0.2% |
| Europe | 36 | 0.1% |
| Total | 36,500 | 100% |
The percentages are ours Our calculation. Two thirds of the workforce sits in Asia outside Korea because the manufacturing subsidiaries are in China (Tianjin and Gaoxin), Vietnam and the Philippines. Note that the company's own "Company Information" page gives headcount as 36,490 rather than the 36,500 in the sustainability report. The reference dates presumably differ, but the company does not explain the discrepancy.
5. Company category and position in the back-end industry
The category is a manufacturer of electronic components. It is not a chipmaker, not a foundry and not an OSAT. It does not build semiconductors; it builds the parts that carry and support them.
Neither TSMC nor Samsung Electronics nor SK hynix discloses back-end revenue separately. Samsung Electro-Mechanics does: the package substrate business is stated at KRW 2.3018tn, because supplying back-end components is one of its core businesses.
One caveat. That KRW 2.3018tn covers not only FC-BGA for AI accelerators and servers but BGA for smartphone application processors as well. The company publishes no split between FC-BGA and BGA, so how much it earns from AI package substrates cannot be determined from primary sources Not yet confirmed.
6. Sites and the countries where it manufactures
Production sits in five countries: Korea, China, Vietnam, the Philippines and Mexico Sourced. The company describes this as seven production sites across five countries.
| Country | Site | Role |
|---|---|---|
| Korea | Suwon, the head office | Production, R&D, marketing and administration in one place. The research centre is here too |
| Korea | Sejong | A core domestic production site. The company describes it as manufacturing next-generation semiconductor package substrates, MLCCs and other high value-added products. A multilayer PCB plant was completed here in November 1991 |
| Korea | Busan | Likewise a core domestic site, making next-generation semiconductor package substrates and MLCCs. It has also signed a solar power purchase agreement |
| China | Tianjin (TEDA) | A manufacturing subsidiary established in January 1994 |
| China | Gaoxin (Xiqing District, Tianjin) | A manufacturing subsidiary established in May 2001 |
| Vietnam | Pho Yen, Thai Nguyen province | A manufacturing subsidiary established in September 2013 |
| Philippines | Calamba, Laguna | A manufacturing subsidiary established in July 1997, with a new plant completed in April 2017 |
| Mexico | Queretaro | A manufacturing subsidiary, listed by the company with its address as a production site |
| India | Bengaluru | A research and development subsidiary, not a production site |
Beyond these there are 18 sales offices across ten countries in the Americas, Europe and Asia. Research centres number two, in two countries: Suwon and Bengaluru.
In its sustainability report the company states that, of the three domestic sites, Busan and Sejong produce next-generation semiconductor package substrates and MLCCs Sourced. The natural reading is that the main FC-BGA production runs inside Korea.
What is not published is which FC-BGA line sits at which site. The industry talks freely about the Vietnamese plant building FC-BGA, but no statement in the company's own material supporting that could be found for this article Not yet confirmed. For a materials supplier, then, the candidate delivery addresses are Busan and Sejong in Korea, and that is as far as primary sources go.
7. Leading products and share in semiconductor back-end work
The evidence that this company is involved in AI silicon
The company's history and earnings material carry a run of statements about AI package substrates, year by year Sourced.
| When | What the company published |
|---|---|
| September 2006 | Volume production of flip chip CSP substrates began |
| November 2022 | Volume production of high-performance server package substrates (FC-BGA) began, a first in Korea |
| July 2024 | Collaboration with AMD to supply high-performance substrates for hyperscale data centres |
| June 2025 | Volume production of substrates for AI accelerators began |
| November 2025 | A memorandum of understanding with the Sumitomo Chemical group on glass cores for package substrates |
| Fourth quarter 2025 | "Expanded supply of large, multilayer substrates for major big tech customers' server CPUs and AI accelerators" and "supplied new products for a new big tech customer's AI accelerators and networking on schedule" |
| Second quarter 2026 | "FC-BGA revenue grew, led by substrates for AI, servers and vehicles" and "began full supply of new products for a new customer's AI data centre and networking applications" |
On market share, plainly
Samsung Electro-Mechanics publishes no FC-BGA world share, no FC-BGA revenue on its own, and no capacity figure. Revenue for the package substrate business as a whole, KRW 2.3018tn, is disclosed, but there is no split between FC-BGA and BGA within it Not yet confirmed. Figures of the form "FC-BGA world share is X per cent" are estimates from research firms or the press, and this article does not use them.
The only customer the company has named is AMD, in the July 2024 collaboration. Who the "major big tech customers" and "new big tech customer" of the earnings material are has never been published Not yet confirmed.
Only three things can be stated with confidence from primary sources.
- Package substrate revenue was KRW 2.3018tn in 2025, or 20.34% of the group (section 5 and Fig. 2) Sourced
- Volume production of substrates for AI accelerators began in June 2025, and full supply to a new customer began in the second quarter of 2026 Sourced
- The company itself says it expects the FC-BGA lines to run at full capacity in the second half of 2026, and is studying capacity expansion and preparing to invest at the right moment, which is primary evidence that supply has not caught up with demand Sourced
Where the revenue goes
8. Current investment plans
Samsung Electro-Mechanics does not disclose an annual capital expenditure figure on its own in its English investor material. What appears is the cash flow line for additions to tangible and intangible assets, quarter by quarter Not yet confirmed. This article uses those quarterly figures, and the trend in the book value of tangible assets, as the nearest available proxy.
For reference, additions to tangible and intangible assets in the first half of 2026, the first and second quarters together, come to KRW 868.9bn Our calculation. The fourth quarter of 2025 alone was KRW 568.6bn. The quarter-to-quarter swing is wide, so these should not be read as an annual figure.
Recent results: the package business is growing fastest
| Measure | Full year 2024 | Full year 2025 | Second quarter 2026 |
|---|---|---|---|
| Group revenue | KRW 10.2941tn | KRW 11.3145tn | KRW 3.4572tn |
| Group operating profit | KRW 735.0bn | KRW 913.3bn | KRW 440.4bn |
| Operating margin | 7.1% | 8.1% | 12.7% |
| Package Solutions revenue | KRW 2.0347tn | KRW 2.3018tn | KRW 771.6bn |
Package Solutions revenue of KRW 771.6bn in the second quarter of 2026 was up 37% year on year, the fastest growth of the three businesses. The group operating margin of 12.7% is also the highest in five years so far as this article could verify Our calculation.
9. Major corporate partners
Few counterparties are named in the company's English-language material.
| Kind | Counterparty | Substance | Primary source |
|---|---|---|---|
| Customer collaboration | AMD | The company's history records a July 2024 collaboration to supply high-performance substrates for hyperscale data centres. Terms and amounts are not disclosed | The history page of the official site Sourced |
| Materials collaboration | Sumitomo Chemical group | A memorandum of understanding signed in November 2025 on glass cores for package substrates, aimed at replacing the resin core material of the next generation with glass | The history page of the official site Sourced |
| University partnership | Seoul National University | An advanced materials industry-academia centre was established in September 2025 | The history page of the official site Sourced |
| University partnership | POSTECH (Pohang University of Science and Technology) | A memorandum of understanding signed in November 2022 on developing people in materials and components | The history page of the official site Sourced |
| Investment | Alba Industries | An equity investment made in December 2025 in a specialist in small electric motors | The history page of the official site Sourced |
The earnings material repeatedly describes expanding supply of substrates for major big tech customers' server CPUs and AI accelerators, and supplying new products for a new big tech customer's AI accelerators, yet no customer name is ever published. AMD is the only one that can be confirmed. These trading relationships are discussed in counterparties' own disclosure and in trade coverage, but they cannot be confirmed from the company's primary material, so this article does not treat them as partnerships Not yet confirmed.
10. Where the company is heading in this field
Anything said here is a forecast, so the established facts and the outlook drawn from them are kept apart.
What is established
| Fact | What it implies for the back end |
|---|---|
| Volume production of server FC-BGA began in November 2022, a first in Korea, and of AI accelerator substrates in June 2025 | As a supplier of AI substrates, the company has only recently reached volume production |
| The company states that it expects the FC-BGA lines to be fully utilised in the second half of 2026 | Capacity has continued to fall short of demand |
| Package Solutions revenue grew 37% year on year in the second quarter of 2026, the fastest of the three businesses | Group growth is being led by components destined for the back end |
| A glass core memorandum of understanding was signed with the Sumitomo Chemical group in November 2025 | A move to replace the core material of next-generation substrates has begun |
| Larger area with more layers is named explicitly as a development axis and tied to servers and networking | The company has itself identified the technical problem in AI substrates |
| R&D expense rose from 5.9% of revenue in 2021 to 7.0% in 2025 | Research was not cut even while margins were falling |
| An operating margin of 12.7% in the second quarter of 2026 | The capacity to invest is recovering |
Outlook
Not yet confirmed Read plainly, those facts point to Samsung Electro-Mechanics growing in importance in the back end as one of the few companies able to build FC-BGA for AI. Large, many-layered FC-BGA cannot be made unless materials, process and yield all line up at once, which makes it a field new entrants cannot join quickly. As long as the company itself expects full utilisation in the second half of 2026, the supply side will keep the upper hand for a while yet.
Not yet confirmed Two developments could change that. One is capacity expansion arriving too late: the company says only that it is studying expansion, and has published neither an amount nor a timetable. The other is a real shift to glass cores, which could reset the manufacturing advantage built up on resin cores as the material generation turns over. The memorandum with the Sumitomo Chemical group can be read as the company preparing for that shift, but nothing beyond the memorandum itself, no investment figure, no volume production date, no target product, has been published.
11. The risks this company carries
What follows is narrowed to the published figures that matter in a back-end context Sourced.
| Risk | Substance | Supporting figures |
|---|---|---|
| Margin volatility | Revenue moves in a narrow band, yet operating profit fell 56%, from KRW 1.4869tn in 2021 to KRW 660.5bn in 2023 | Operating margin went from 15.4% to 7.4% Our calculation |
| Dependence on China for sales | Of 2025 revenue by region, China was the largest at KRW 4.4418tn, or 39.3%. Two manufacturing subsidiaries, Tianjin and Gaoxin, are in China as well | China at 39.3% of revenue Our calculation |
| Capacity constraint | The company itself expects the FC-BGA lines to be fully utilised in the second half of 2026. If demand persists that means lost orders; expand too far and utilisation falls | Package Solutions revenue up 37% year on year in the second quarter of 2026 |
| Opaque customers | Neither the names of the "major big tech customers" that recur in the earnings material nor the degree of dependence on them is published, so customer concentration cannot be assessed from outside | AMD is the only name disclosed |
| Opaque investment plans | Neither an annual capital expenditure figure nor the amount and timing of FC-BGA expansion is published | Only quarterly additions to tangible and intangible assets are disclosed |
| Divergence between the three businesses | While Package Solutions grew 37%, Optics Solutions fell 4% quarter on quarter in the second quarter of 2026. The businesses are not moving in step | Quarter-on-quarter change by business, second quarter 2026 |
At the centre of an FC-BGA is a core, with build-up layers stacked on both faces. That core has conventionally been resin, an insulating board filled with glass fibre, but the larger and more layered the substrate becomes for AI, the more warpage and dimensional stability become the wall. Use glass for the core and the coefficient of thermal expansion moves closer to silicon, holding warpage down. That is what a glass core is for.
That Samsung Electro-Mechanics itself announced a memorandum with the Sumitomo Chemical group in November 2025 matters decisively to materials makers. Replace a resin core with glass and the prepreg used in lamination, the method of forming vias and the surface finish all change together.
Which products this memorandum applies to, when, and at what scale of investment has not been published, and could not be confirmed for this article Not yet confirmed. What can be said from primary sources, for now, is only that the memorandum was signed.
12. Glossary
- Package substrate
- The board a semiconductor die sits on, carrying signals between the die and the main board while supporting the die mechanically. It is the central component of back-end assembly.
- FC-BGA
- Flip Chip Ball Grid Array. A highly integrated package substrate in which the die is turned over and joined to the substrate by bumps. Used for server CPUs and AI accelerators, it is large in area and rich in layers.
- BGA and FCCSP
- Ball Grid Array, a package form with a grid of solder balls on the underside. FCCSP is the highly integrated variant in which the die occupies more than 80% of the package area, used for smartphone application processors.
- Coreless
- A construction that dispenses with the core of a package substrate. It allows a thinner substrate and is used in slim devices such as notebook PCs. One of the company's development axes.
- Glass core
- A next-generation construction using glass as the core of a package substrate. Its coefficient of thermal expansion is closer to silicon, which is said to hold warpage down. The company signed a memorandum with the Sumitomo Chemical group in November 2025.
- MLCC
- Multilayer Ceramic Capacitor. A chip component of alternating dielectric and electrode layers that steadies the current in a circuit and suppresses electromagnetic interference between parts. It is this company's largest business.
- Embedded passives
- A technique that buries passive components such as capacitors inside the package substrate, saving mounting area and improving electrical behaviour. One of the company's development axes.
- Sustainability report
- An annual report in which a company sets out its environmental, social and governance activity together with the related data. This company discloses headcount, R&D expense and revenue by region in it.
 AI-generated concept
13. References
- Samsung Electro-Mechanics Q4 2025 Earnings Result (23 January 2026). Full-year and fourth-quarter 2025 revenue, revenue by business, operating profit and net profit; financial position; cash flow; the dividend plan; FC-BGA supply and demand and the outlook for 2026. https://www.samsungsem.com/resources/file/global/ir/earnings_release/4Q25_Earnings_Release_eng.pdf
- Samsung Electro-Mechanics Q2 2026 Earnings Result. Second-quarter 2026 revenue of KRW 3.4572tn, operating profit of KRW 440.4bn and a 12.7% operating margin; revenue by business; cash flow; the state of the package business. https://www.samsungsem.com/resources/file/global/ir/earnings_release/2Q26_Earnings_Release_eng.pdf
- Samsung Electro-Mechanics Q4 2024 Earnings Result. Full-year 2024 revenue of KRW 10.2941tn, revenue by business and operating profit of KRW 735.0bn. https://www.samsungsem.com/resources/file/global/ir/earnings_release/4Q24_Earnings_Release_eng.pdf
- Samsung Electro-Mechanics Official investor relations site, "Financial Information". Summary financial statements for 2021 to 2025: revenue, cost of sales, operating profit, net profit, total assets and tangible assets. https://www.samsungsem.com/global/about-us/investor-relations/financial-information.do
- Samsung Electro-Mechanics 2025-2026 Sustainability Report. Headcount and its regional split; revenue by region; revenue by business and the shares; R&D expense and its ratio to revenue for 2021 to 2025; the roles of the three domestic sites; the number of production, sales and research sites; and the product descriptions of BGA, FC-BGA and the development axes. https://www.samsungsem.com/resources/file/global/sustainability/report/SEM_SR2025_EN.pdf
- Samsung Electro-Mechanics Official site, "Company Information". Year of foundation (1973), headcount, total assets, revenue and the business areas. https://www.samsungsem.com/global/about-us/company/overview.do
- Samsung Electro-Mechanics Official site, "History & Awards". Foundation in August 1973; the February 1979 listing; the February 1987 change of name; the founding years of the overseas manufacturing subsidiaries; flip chip CSP substrate volume production in 2006; the start of server FC-BGA volume production in November 2022; the AMD collaboration of July 2024; the start of AI accelerator substrate volume production in June 2025; and the glass core memorandum with the Sumitomo Chemical group in November 2025. https://www.samsungsem.com/global/about-us/company/history.do
- Samsung Electro-Mechanics Official site, "Global Network". The locations and addresses of the production, sales and research sites. https://www.samsungsem.com/global/about-us/company/location.do
- Samsung Electro-Mechanics Official investor relations site, "Stocks". Ticker 009150, 74,693,696 shares issued, par value KRW 5,000. https://www.samsungsem.com/global/about-us/investor-relations/stock.do
- Samsung Electro-Mechanics Newsroom, "Samsung Electro-Mechanics Announces 2025 Q4 Business Performance" (23 January 2026). Full-year 2025 revenue of KRW 11.3145tn, a record, and operating profit of KRW 913.3bn; fourth-quarter results by business; and the direction set for 2026. https://www.samsungsem.com/global/newsroom/news/view.do?id=10042
14. Claim-to-source audit
| Claim in the article | Category | Source |
|---|---|---|
| Foundation in August 1973, the February 1979 listing, the February 1987 change of name, and the founding years of the overseas manufacturing subsidiaries | Sourced | Reference 7 https://www.samsungsem.com/global/about-us/company/history.do |
| Ticker 009150 and 74,693,696 shares issued | Sourced | Reference 9 https://www.samsungsem.com/global/about-us/investor-relations/stock.do |
| 2025 revenue of KRW 11.3145tn (up 10%), operating profit of KRW 913.3bn (up 24%) and an 8.1% margin | Sourced | References 1 and 10 https://www.samsungsem.com/global/newsroom/news/view.do?id=10042 |
| Revenue, operating profit, total assets and the book value of tangible assets for 2021 to 2025 | Sourced | Reference 4 https://www.samsungsem.com/global/about-us/investor-relations/financial-information.do |
| Operating margins for 2021 to 2024 (15.4%, 12.8%, 7.4%, 7.1%) and the 56% fall in operating profit from 2021 to 2023 | Our calculation | Derived from the revenue and operating profit in reference 4 https://www.samsungsem.com/global/about-us/investor-relations/financial-information.do |
| 2024 revenue of KRW 10.2941tn, revenue by business and operating profit of KRW 735.0bn | Sourced | Reference 3 https://www.samsungsem.com/resources/file/global/ir/earnings_release/4Q24_Earnings_Release_eng.pdf |
| Revenue by business (Components KRW 5.1985tn, Optics KRW 3.8142tn, Package KRW 2.3018tn) and the shares | Sourced | Reference 5 https://www.samsungsem.com/resources/file/global/sustainability/report/SEM_SR2025_EN.pdf |
| 36,500 employees and the regional split (Korea 12,176, Asia 24,229, Americas 59, Europe 36), and R&D expense and its ratio to revenue for 2021 to 2025 | Sourced | Reference 5 https://www.samsungsem.com/resources/file/global/sustainability/report/SEM_SR2025_EN.pdf |
| The regional shares of headcount (Korea 33.4% and the rest) | Our calculation | Derived from the headcount in reference 5 https://www.samsungsem.com/resources/file/global/sustainability/report/SEM_SR2025_EN.pdf |
| Revenue by region (China KRW 4.4418tn, Korea KRW 3.6268tn, South-east Asia KRW 2.3688tn, Americas KRW 422.3bn, Europe KRW 371.1bn, Japan KRW 83.7bn) | Sourced | Reference 5 https://www.samsungsem.com/resources/file/global/sustainability/report/SEM_SR2025_EN.pdf |
| The regional shares of revenue (China 39.3% and the rest) | Our calculation | Derived from the amounts in reference 5 https://www.samsungsem.com/resources/file/global/sustainability/report/SEM_SR2025_EN.pdf |
| The product descriptions of BGA and FC-BGA, the four development axes, the roles of the three domestic sites, and seven production sites across five countries | Sourced | Reference 5 https://www.samsungsem.com/resources/file/global/sustainability/report/SEM_SR2025_EN.pdf |
| The locations of the production, sales and research sites | Sourced | Reference 8 https://www.samsungsem.com/global/about-us/company/location.do |
| Server FC-BGA volume production in November 2022, a first in Korea; the AMD collaboration of July 2024; AI accelerator substrate volume production from June 2025; the glass core memorandum with the Sumitomo Chemical group in November 2025 | Sourced | Reference 7 https://www.samsungsem.com/global/about-us/company/history.do |
| The expectation of full FC-BGA utilisation in the second half of 2026 and the study of capacity expansion, and the fourth-quarter expansion of supply to big tech customers | Sourced | Reference 1 https://www.samsungsem.com/resources/file/global/ir/earnings_release/4Q25_Earnings_Release_eng.pdf |
| Second-quarter 2026 revenue of KRW 3.4572tn, operating profit of KRW 440.4bn, a 12.7% margin, and Package Solutions revenue of KRW 771.6bn, up 37% year on year | Sourced | Reference 2 https://www.samsungsem.com/resources/file/global/ir/earnings_release/2Q26_Earnings_Release_eng.pdf |
| Additions to tangible and intangible assets in the first half of 2026 totalling KRW 868.9bn | Our calculation | The cash flow figures in reference 2, KRW 265.0bn in the first quarter plus KRW 603.9bn in the second, added together https://www.samsungsem.com/resources/file/global/ir/earnings_release/2Q26_Earnings_Release_eng.pdf |
| Additions to tangible and intangible assets of KRW 568.6bn in the fourth quarter of 2025 | Sourced | Reference 1 https://www.samsungsem.com/resources/file/global/ir/earnings_release/4Q25_Earnings_Release_eng.pdf |
| Foundation in 1973, headcount of 36,490, total assets and revenue as given on the company information page | Sourced | Reference 6 https://www.samsungsem.com/global/about-us/company/overview.do |
| FC-BGA revenue on its own, and its split against BGA | Not yet confirmed | Not disclosed. Only the package business as a whole is published, and this article shows the KRW 2.3018tn as a ceiling |
| FC-BGA world share and production capacity | Not yet confirmed | No primary source exists, so this article states no figure |
| The names of the "major big tech customers" and the "new big tech customer", and the degree of dependence on them | Not yet confirmed | Not disclosed. AMD is the only name that can be confirmed, and this article does not fill the gap by inference |
| Whether the Vietnamese plant produces FC-BGA | Not yet confirmed | No supporting statement could be found in the company's published material, so this article makes no claim |
| Annual capital expenditure, and the amount and timing of FC-BGA expansion | Not yet confirmed | The company publishes no annual figure in its English investor material, so this article gives quarterly figures only |
| The target products, timing and investment scale of the glass core memorandum with the Sumitomo Chemical group | Not yet confirmed | Only the signing of the memorandum is published, and this article goes no further |
| Why headcount is given as 36,490 in one place and 36,500 in another | Not yet confirmed | The reference dates presumably differ, but the company offers no explanation, so this article carries both numbers |
| The outlook in section 10 | Not yet confirmed | An interpretation by this article, drawn from the seven items in the facts table |
Last updated 21 September 2026 / Troy Technical
Every figure in this article comes from the earnings releases Samsung Electro-Mechanics publishes, the summary
financial data on its official investor relations site, its sustainability report, and its official company
information and history pages. No research-firm estimates or press-based figures have been used. Won amounts are given
in won, because the company publishes no U.S. dollar translation of them.