Background
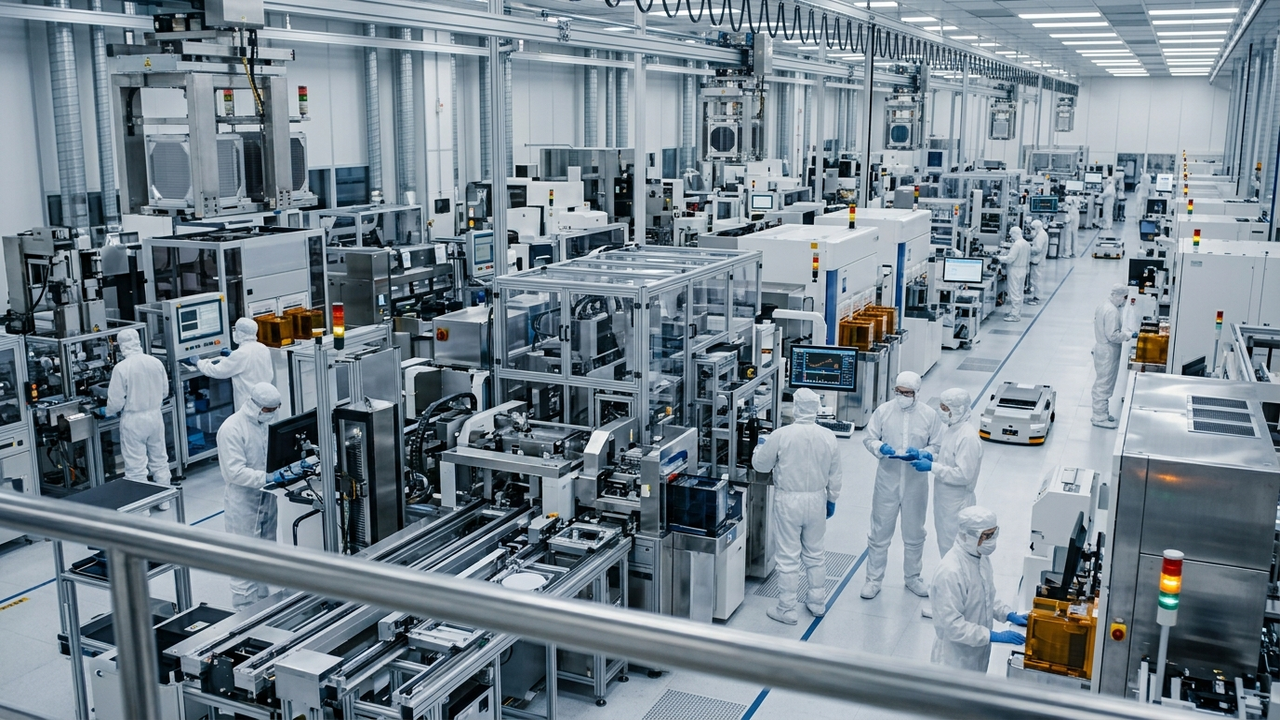
The recent geographical shift in semiconductor equipment investment is rooted in a confluence of evolving technological demands and significant geopolitical factors. Intensifying trade tensions and technological competition between the United States and China have initiated a profound restructuring of the global semiconductor supply chain. This environment has prompted an acceleration of investments in reliable partners, particularly for strategically crucial AI-related technologies. South Korea and Taiwan, leveraging their established positions as central hubs for global semiconductor manufacturing and their advanced technological prowess, are key beneficiaries of this realignment. Fundamentally, this investment pivot is deeply intertwined with these nations’ broader economic security strategies in the burgeoning AI era.
Key Findings
In the first half of 2026, global semiconductor equipment sales experienced a decisive geographical pivot, with South Korea and Taiwan emerging as the primary growth catalysts, shifting focus from China. South Korea’s sales surged by 32.4%, while Taiwan recorded a robust 24.0% increase. Of the total global sales increase of $11.96 billion, South Korea contributed $4.41 billion and Taiwan $3.80 billion, together accounting for 68.6% of the growth. This significant trend is strongly driven by substantial investments in leading-edge logic and advanced packaging capabilities in Taiwan, alongside aggressive expansions in High Bandwidth Memory (HBM) and advanced DRAM in South Korea.
Technical and Market Analysis
The burgeoning demand for artificial intelligence (AI) is profoundly reshaping capital expenditure strategies across the semiconductor industry. To meet the demanding performance specifications of AI chips, advancements are required not only in miniaturized logic manufacturing but also in sophisticated memory solutions like High Bandwidth Memory (HBM) and advanced packaging technologies, including 2.5D/3D stacking. Consequently, fabs in South Korea and Taiwan, which have established leadership in these critical technologies, are seeing their capital expenditure priorities significantly elevated. Illustratively, SK Hynix, a dominant HBM supplier, has unveiled substantial advanced packaging investments both within South Korea and in Indiana, USA. Concurrently, Taiwanese foundries, exemplified by TSMC, underpin AI chip production with their state-of-the-art logic and pioneering advanced packaging solutions such as CoWoS. This concentrated investment in South Korea and Taiwan signifies not just a geographical reallocation but also the definitive future direction of semiconductor technology evolution in the AI era.
Future Outlook
Provided the AI and high-performance computing (HPC) markets sustain their growth trajectory, semiconductor equipment investments in South Korea and Taiwan are projected to remain robust. This sustained investment will further solidify both regions’ pivotal roles in global semiconductor production capacity. However, this also anticipates intensified global competition, particularly as other regions, notably the United States and Europe, actively pursue strategies to bolster their domestic semiconductor manufacturing capabilities. The contest for leadership in HBM and advanced packaging technologies is thus expected to persist as a central and defining theme within the semiconductor industry for the foreseeable future.
Source: https://drrobertcastellano.substack.com/p/the-semiconductor-equipment-boom
Get our weekly technology intelligence — free
Receive an infographic that lets you judge at a glance whether each field’s analysis report is worth reading.
Subscribe Free — Weekly Tech Intelligence
By subscribing, you’ll receive Troy-Technical’s weekly technology intelligence newsletter.
- Your email and selected fields are used only to deliver the newsletter.
- We never share your information with third parties.
- You can unsubscribe anytime via the link in each email.
See our Privacy Policy for details.
Takes about a minute · Unsubscribe anytime

Comments